Average Property Insurance Claim Hits Record £10,000 in the UK
UK property insurance claims have reached an unprecedented average of £10,000, driven by extreme weather, subsidence, and soaring rebuild costs.
Pexels - GOWTHAM AGM · original
In this article
Key Takeaway: The average UK property insurance claim has reached a record £10,000, driven primarily by extreme weather events, subsidence linked to climate patterns, and sharply rising rebuild costs. This trend means higher premiums for homeowners and a greater risk of underinsurance if your buildings sum insured has not kept pace with construction inflation. Review your policy’s rebuild cost estimate annually and consider whether your excess remains affordable at claim time.
Introduction
Property insurance claims in the United Kingdom have hit an unprecedented average of £10,000, marking a significant milestone that reflects the mounting pressures on both homeowners and insurers. According to the Association of British Insurers, this record figure represents a steep climb from previous years, when the typical buildings insurance claim sat closer to £6,000 to £7,000 (ABI, 2026). The surge is not the result of a single catastrophic event but rather a convergence of factors: more frequent and severe weather damage, widespread subsidence exacerbated by drought and flood cycles, and a dramatic rise in the cost of materials and labour required to repair or rebuild damaged properties. For UK homeowners, understanding what drives these record-high claims is essential, both to ensure adequate cover and to grasp why premiums continue to rise.
What’s Driving Record-High Property Insurance Claims in the UK
Several interconnected forces have pushed the average property insurance claim to £10,000, and each warrants close attention.
Extreme Weather and Storm Damage
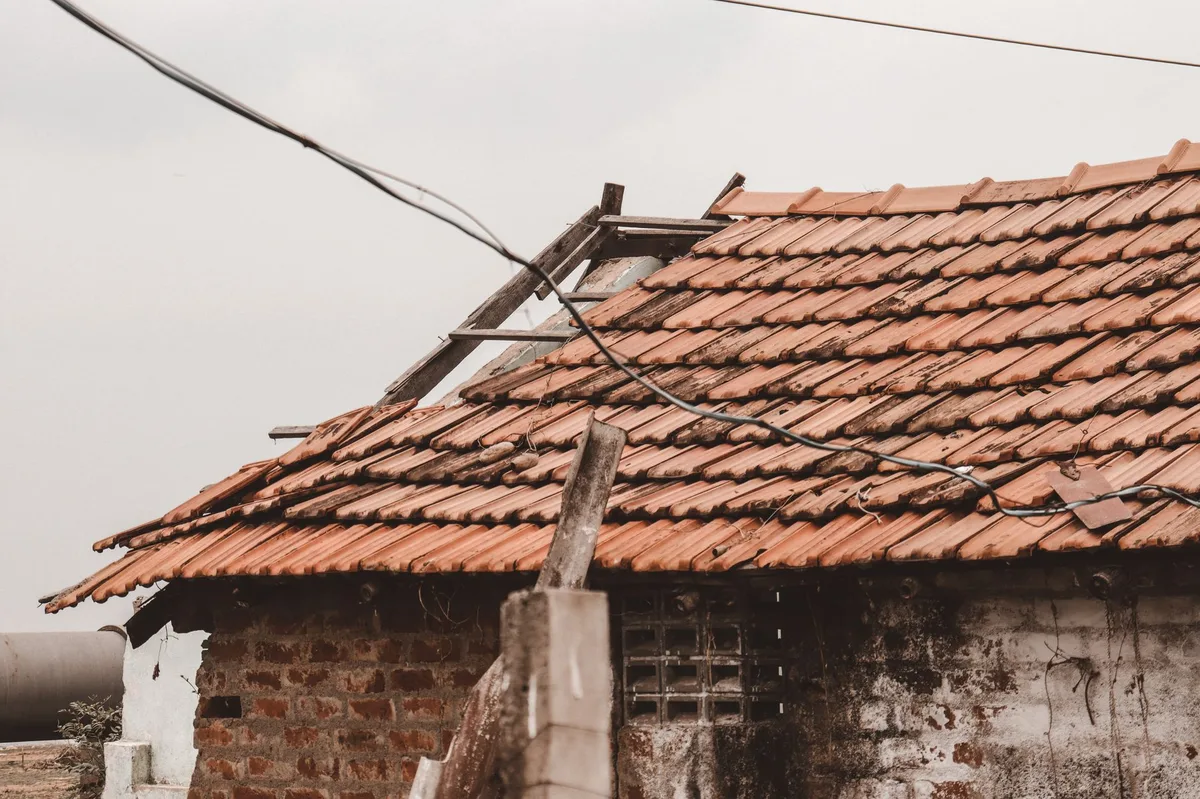
The UK has experienced a noticeable increase in the frequency and intensity of storms, flooding, and wind damage over recent years. Events that once qualified as one-in-a-decade occurrences now arrive with greater regularity, straining the insurance system. Storm damage to roofs, windows, and structural elements can easily run into thousands of pounds, particularly when emergency repairs and temporary accommodation are factored in. Flooding, whether from rivers, surface water, or coastal surges, often results in claims well above the average as entire ground floors require drying, replastering, and replacement of fixtures and fittings.
Subsidence and Ground Movement
Subsidence claims, historically among the costliest for insurers, have become more common as soil conditions fluctuate between prolonged dry spells and sudden heavy rainfall. Clay soils, prevalent across southern England, expand and contract with moisture levels, causing structural movement that cracks foundations and walls. Repairing subsidence typically involves underpinning or other specialist groundwork, pushing individual claims to £15,000 or more. The increased frequency of these claims pulls the overall average upward.
Soaring Rebuild Costs and Supply Chain Pressures
Construction costs in the UK have risen sharply, fuelled by post-pandemic supply chain disruption, Brexit-related import tariffs, skilled labour shortages, and general inflation. According to industry indices, the cost to rebuild a typical UK home has increased by roughly 30 to 40 per cent since 2020. Timber, cement, roof tiles, and energy-intensive materials such as bricks have all seen sustained price hikes. When a buildings insurance claim is settled, the insurer pays the current cost to repair or rebuild, not the historical cost, so even a modest roof repair that might have cost £4,000 in 2019 can now exceed £6,000. As the principles covered in foundational texts such as Principles of Finance explain, insurance operates on the principle of indemnity, restoring the policyholder to their pre-loss position at current replacement cost, which directly ties claim payouts to prevailing market prices.
Increased Awareness and Claim Frequency
Homeowners are also more aware of their rights and quicker to claim for damage that might previously have been absorbed as routine maintenance. Accidental damage cover, now a common optional add-on, broadens the scope of claimable incidents, from spilled paint on carpets to DIY mishaps. While individual accidental damage claims tend to be smaller, their growing frequency contributes to the overall average.
What This Means for UK Homeowners
The £10,000 average claim figure carries practical implications for anyone holding buildings or contents insurance.
Rising Premiums
Insurers price policies based on anticipated claim costs. When the average claim rises by several thousand pounds, premiums must adjust upward to maintain solvency and meet regulatory capital requirements set by the Prudential Regulation Authority. Homeowners renewing policies in 2026 and beyond should expect continued premium increases, particularly in regions prone to flooding or subsidence. The Financial Conduct Authority recommends that consumers shop around annually and compare cover on a like-for-like basis, as loyalty rarely yields the best price (FCA, 2026).
Underinsurance Risk
A buildings sum insured set three or four years ago may no longer reflect the true rebuild cost in today’s market. If your policy limit is £250,000 but the actual rebuild cost has climbed to £350,000, you are underinsured by £100,000. Many policies include an average clause, meaning the insurer will only pay a proportionate share of any claim if you are underinsured. For a £20,000 claim on a property underinsured by 30 per cent, you might receive only £14,000, leaving a painful shortfall. MoneyHelper advises using a professional rebuild cost calculator or surveyor’s assessment rather than relying on the property’s market value, which includes land and location factors irrelevant to rebuild cost (MoneyHelper, 2026).
Excess Considerations
As claims grow larger, so too can the excess you agree to pay. A voluntary excess of £500 might have seemed reasonable when the average claim was £6,000, but with claims now averaging £10,000, insurers may encourage higher excesses to reduce premiums. Ensure any excess remains affordable in the event you need to claim: a £1,000 excess saves money on the premium but must be found upfront when a loss occurs.
How to Protect Yourself Against Underinsurance
Review your buildings sum insured at every renewal. Use the Association of British Insurers’ online rebuild cost calculator or commission a surveyor’s rebuild valuation, particularly for older or non-standard properties. Rebuild cost is not the same as market value: a £400,000 house in a desirable postcode might cost only £280,000 to rebuild, while a large detached home in a less expensive area could require £500,000 to reconstruct.
Check whether your policy includes index-linking, which automatically adjusts the sum insured each year in line with the House Rebuild Cost Index published by the Royal Institution of Chartered Surveyors. Index-linking helps your cover keep pace with construction inflation without manual intervention, though you should still verify the base figure is correct.
Read also: Does Your Home and Car Insurance Cover Winter Weather Damage in the UK?
Consider whether accidental damage cover is worthwhile. For an additional premium, it extends your policy to mishaps such as cracked sinks, carpet stains, or damaged TVs, reducing the risk of out-of-pocket repair bills.
Common Mistakes to Avoid
Confusing Market Value with Rebuild Cost
The price you paid for your home, or its current sale value, bears little relation to the cost of rebuilding it from foundations upward. Always base your sum insured on rebuild cost.
Setting the Excess Too High to Save Premium
A £2,000 excess might cut your annual premium by £150, but if you cannot afford £2,000 at claim time, the saving is false economy. Balance premium reduction against realistic affordability.
Failing to Declare Home Improvements
Extensions, loft conversions, and conservatories increase rebuild cost. Notify your insurer of any structural changes so the sum insured can be adjusted upward; otherwise, you risk underinsurance.
Ignoring Subsidence Exclusions
Some policies exclude subsidence to certain structures, such as boundary walls, gates, or driveways, unless the main building is also affected. Read the policy wording to understand what is and is not covered.
Frequently Asked Questions
Why has the average property insurance claim reached £10,000?
The record average reflects a combination of extreme weather events, increased subsidence claims, and sharply higher rebuild costs driven by inflation, supply chain issues, and skilled labour shortages.
Does the £10,000 average mean my claim will be that large?
No. The £10,000 figure is an average across all claims, which range from minor repairs of a few hundred pounds to total rebuilds exceeding £100,000. Your individual claim depends on the nature and extent of the damage.
How can I avoid underinsurance?
Use a professional rebuild cost calculator or surveyor to set your buildings sum insured, and review it annually. Ensure the figure reflects current construction costs, not the property’s market value.
Will my premium keep rising?
Premiums are likely to increase as long as claim costs continue to climb. Shopping around at renewal, increasing your voluntary excess, and improving home security or flood defences may help contain premium growth.
What should I do if I cannot afford the excess at claim time?
Contact your insurer before making a claim. Some may allow you to pay the excess in instalments, though this is not guaranteed. If the excess is unaffordable, consider reducing it at the next renewal, accepting that your premium will rise.
Conclusion
The average UK property insurance claim hitting £10,000 is a clear signal that homeowners must reassess their cover, particularly the buildings sum insured and the affordability of any excess. Driven by extreme weather, subsidence, and soaring rebuild costs, this trend shows no sign of reversing. Review your policy annually, use a rebuild cost calculator, and ensure your cover keeps pace with construction inflation. For personalised advice on your own circumstances, consider speaking to an FCA-authorised insurance adviser who can assess your specific risks and recommend appropriate cover levels.
Financial Disclaimer: This article provides general information only and does not constitute regulated financial advice. We are not authorised by the Financial Conduct Authority. Insurance needs, cover limits, exclusions, and premiums vary by insurer, property, and individual circumstances. Always read the policy wording, key facts document, and statement of demands and needs, and consider consulting an FCA-authorised insurance adviser for guidance tailored to your personal situation before purchasing or renewing cover.
Sources
- Products and Issues (accessed )
- Consumer Guidance (accessed )
- Insurance (accessed )
- Principles of Finance (accessed )
Related articles
Does Your Home and Car Insurance Cover Winter Weather Damage in the UK?
Learn what winter weather damage is covered by UK home and car insurance, including storm damage, flooding, and frost, plus key exclusions.
How to Make a Successful Home Insurance Claim in the UK
Understand how to successfully file and settle a home insurance claim in the UK with this step-by-step guide to the claims process.
How a Claim Affects Your UK Insurance Premium at Renewal
Learn how making a claim impacts your UK insurance premium at renewal, including no-claims bonus protection and how long claims stay on record.
