Insurance
Autumn Car Insurance Review in Canada: Preparing for Winter Driving
Review your auto insurance this fall to ensure you have the right coverage for winter road conditions and avoid coverage gaps.
UmbrellaOwl / Insurance
Review your auto insurance this fall to ensure you have the right coverage for winter road conditions and avoid coverage gaps.
Protect your home insurance coverage this winter with essential maintenance steps that prevent costly claims and keep your policy valid.
Learn what to examine in your employer's life, disability, and health coverage during open enrollment to make informed decisions for the year ahead.
Provincial health plans offer limited or no coverage outside Canada. Snowbirds heading south need emergency medical travel insurance to cover hospital stays, medical evacuation, and treatment costs that can reach hundreds of thousands of dollars.
Autumn renewal season is here. Before you sign, compare coverage limits, deductibles, premiums, exclusions, and discounts to make sure your policy still fits your needs and budget.
Critical illness insurance pays a lump sum if you are diagnosed with a covered serious illness. Learn which conditions qualify and whether this coverage fits your financial protection plan.
Understanding the factors that drive your car insurance costs is the first step to reducing your premium and keeping more money in your pocket.
Home insurance protects your dwelling, personal property, and liability, but excludes flood damage, earthquakes, and wear and tear unless you add endorsements.
Auto insurance in Canada varies dramatically by province, with some operating public systems and others relying on private markets, each with different mandatory coverages and cost structures.
Term and permanent life insurance serve different needs. Learn how to evaluate coverage duration, premium costs, and cash value features to pick the right policy for your situation.
Learn the key steps to compare home insurance quotes accurately across Canadian insurers and find the best coverage for your needs.
Major life changes often mean your insurance needs have shifted. Learn which life events should trigger a coverage review and what to update.
Compare essential business insurance coverage options for small businesses and self-employed professionals in Canada, from general liability to cyber protection.
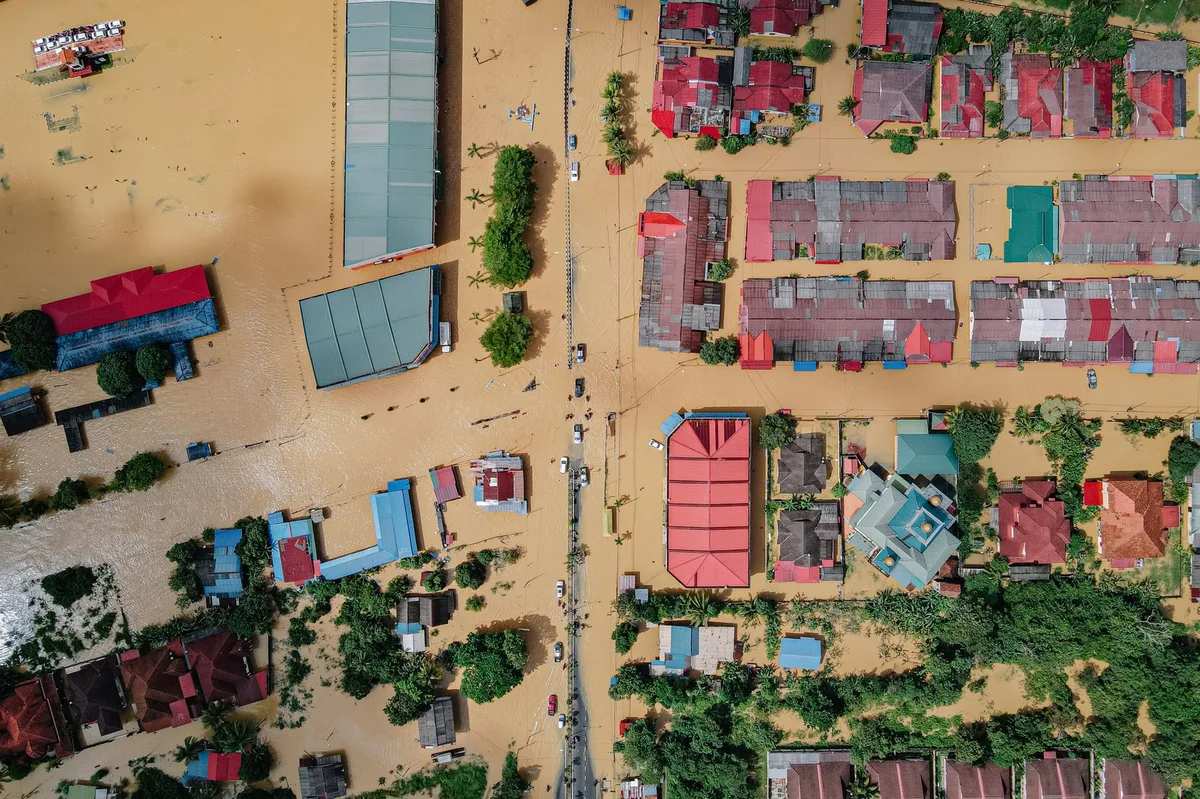
Understanding the difference between standard home insurance exclusions and optional overland water coverage can save Canadian homeowners from unexpected financial losses.
Bundling home and auto insurance can save Canadian drivers 10 to 25 percent on premiums, but separate policies sometimes offer better coverage or lower total cost.
Learn how to calculate the right amount of life insurance coverage for your family's needs using proven Canadian financial planning methods.
Understand what your employer's group benefits package covers and where gaps may exist in your life, disability, and health insurance protection.
Learn how to challenge a denied or reduced insurance claim in Canada, including your rights, the appeal process, and when to escalate to your provincial regulator.
Pet insurance can cost C$30 to C$150 per month, but a single emergency can run thousands. Find out when coverage pays off and when you're better saving on your own.
Provincial health plans offer limited coverage abroad. Learn what travel insurance should include and where your provincial plan falls short.
Tenant insurance protects your belongings and liability as a renter. Learn what's covered, how much you need, and how to get the right policy in Canada.
Most Canadian life insurance policies include a terminal illness benefit at no extra cost, but understanding how it compares to standalone critical illness coverage can help you make informed decisions about your protection.
Learn how mid-term cancellation fees work across Canadian provinces and how to calculate whether switching insurers will save you money despite the penalties.
Learn when to name a person as beneficiary versus your estate on Canadian life insurance, and understand the probate, tax, and timing implications of each choice.
Under-insuring your home triggers the coinsurance clause, which can slash your claim payout even for partial losses. Here's what every Canadian homeowner needs to know.
Compare workers' compensation coverage across Canadian provinces, understand which provincial board covers you, and learn when mandatory workplace injury insurance applies to your employment.
Using your personal car for business purposes can void your auto insurance coverage, leaving you exposed to claim denials and out-of-pocket costs.
A practical checklist to understand how filing an insurance claim affects your premium when your policy renews, including fault rules, accident forgiveness, and provincial differences.
E&O insurance covers professional mistakes and advice, while CGL protects against bodily injury and property damage. Most Canadian freelancers need one or both depending on their work.
Learn how joint first-to-die life insurance compares to separate policies for Canadian couples, including cost differences, coverage trade-offs, and when each option makes sense for your family.
Key person insurance protects Canadian businesses from the financial impact of losing a critical owner or executive. Learn what it covers, how it works, and whether your business needs it.
Non-owner car insurance provides liability coverage when you regularly drive vehicles you don't own, though most Canadians are already covered under the owner's policy.
Learn how scheduling protects valuables beyond standard policy sub-limits and why professional appraisals matter for home insurance claims in Canada.
Compare low, medium, and high deductible options to understand the trade-off between upfront premium savings and out-of-pocket claim costs across Canadian provinces.
Compare traditional auto insurance with usage-based programs in Canada. Understand how telematics discounts work, the privacy trade-off, and which option fits your driving profile.
A claims-free discount rewards drivers who avoid filing auto insurance claims. One at-fault accident can erase years of savings.
Understand the key differences between term and permanent life insurance to choose the right coverage for your family and financial goals in Canada.
Group disability insurance through your employer offers convenient coverage but may have gaps, while individual policies provide portable, customizable protection you control directly.
Learn the key differences between term and permanent life insurance to choose the right coverage for your family's financial protection in Canada.
Calculate the landlord insurance coverage you need for your rental property in Canada with our interactive tool that factors in property damage, liability, and loss of rent protection.
Learn how the calculator method helps you estimate the life insurance coverage needed to replace your income and protect your family's financial future in Canada.
Learn how to determine the right amount of dwelling, liability, and loss-of-rental-income coverage for your rental property in Canada.
Understand what drives pet insurance costs in Canada and use our calculator to estimate your premium based on your pet's age, breed, location, and coverage choices.
Income protection replaces lost earnings when illness or injury stops you from working. Long-term care insurance pays for custodial care when you need help with daily activities. Each fills a distinct financial gap.
Long-term care insurance helps Canadians cover the gaps in provincial care programs when you need assisted living or nursing home care.
Learn how to calculate the monthly disability insurance benefit you need to protect your salary and maintain your standard of living if illness or injury prevents you from working.
Learn how trip length, age, destination, and coverage type determine your travel insurance premium, and use our calculator to estimate costs for snowbird stays or international trips.
Mortgage life insurance and term life insurance both protect your family if you pass away, but they work differently and offer different value. Term life usually provides more flexibility, lower premiums, and better coverage for your money.
Provincial health plans offer limited or no coverage outside Canada. Learn what travel insurance covers, when OHIP and other provincial plans are not enough, and how to estimate the right coverage for your trip.
Learn how to determine the right amount of critical illness insurance coverage for your situation using key financial factors and family needs.
Standard home policies exclude flood and sewer backup. Here's what you need to know about adding this optional coverage in Canada.
Compare disability and critical illness coverage to decide which protection fits your financial needs and family situation in Canada.
Provincial health plans cover hospital and physician services, but extended health insurance fills critical gaps in prescription drugs, dental, vision, and paramedical care across Canada.
Your condo corporation's master policy covers the building structure, but not your personal belongings, improvements, or liability. Here's what coverage you need as a Canadian condo owner.
Compare employer group life insurance and individual policies to understand which provides better protection for Canadian families.
Compare term and permanent life insurance to find the best coverage for your family's needs and budget in Canada.
Understand the key differences between group and individual supplementary health and dental coverage in Canada and how to choose the right plan for your situation.
Understand the key differences between employer-sponsored group disability coverage and individual disability insurance policies in Canada, and learn which option best protects your income.
Learn exactly what standard home insurance covers in Canada, common exclusions, and how to identify gaps in your coverage.

Compare Canada's leading home insurance providers by coverage options, customer service, and value to find the right policy for your property.
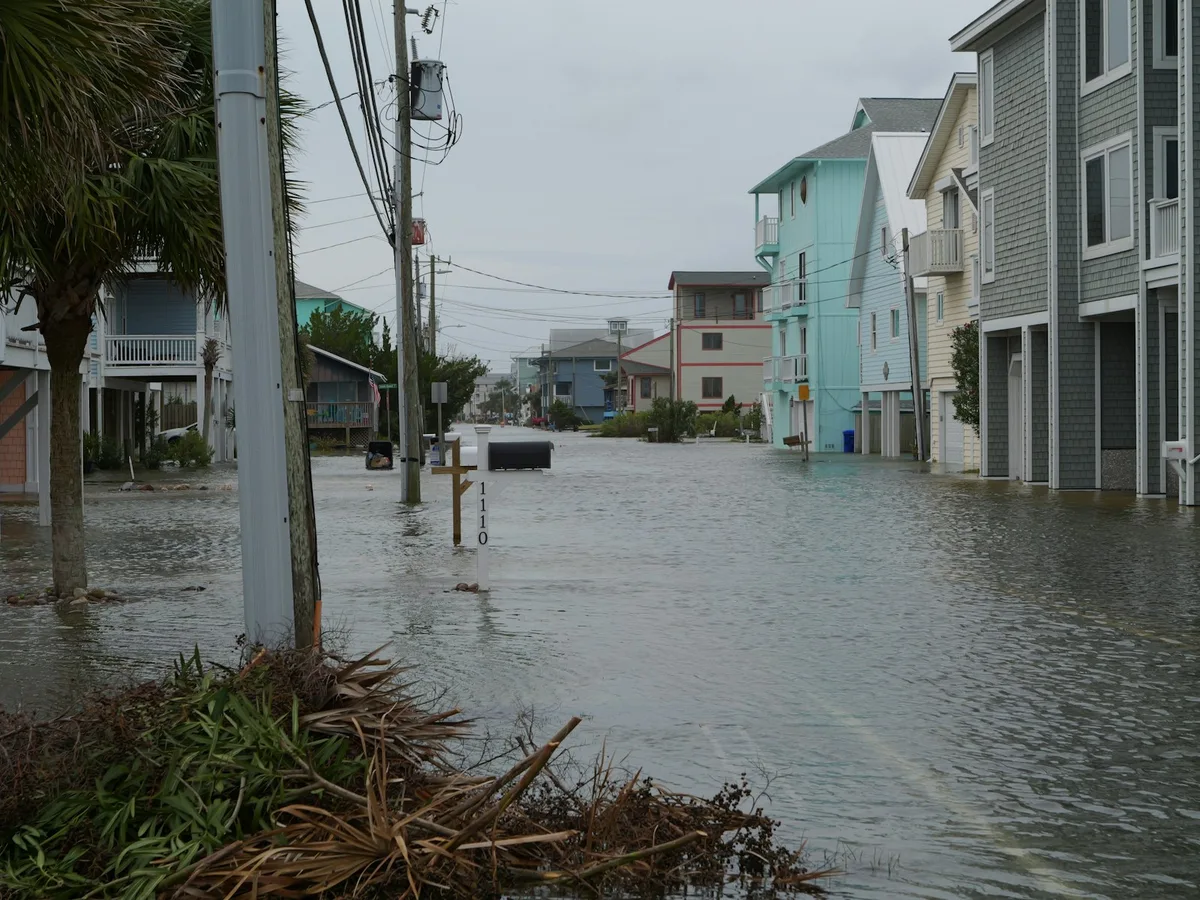
Standard home insurance in Canada covers wildfire damage but typically excludes overland flooding - you need separate coverage for floods and other climate risks.
Canada's record insured disaster losses are putting pressure on home insurance renewals. Here is what homeowners should check before accepting a higher premium.
Wildfire damage is typically covered under standard home insurance in Nova Scotia, but coverage limits, deductibles, and claim documentation requirements vary by policy and insurer.
High claims satisfaction is encouraging, but Canadian drivers should still compare price, coverage, service, and provincial rules before renewing.
A higher renewal is not automatically the best price available. Compare equivalent quotes, correct outdated details, and adjust coverage carefully before your policy renews.
Kin's U.S. auto insurance launch is not a Canadian product update, but the bundling idea is relevant for Canadian homeowners. Compare the total price, coverage wording, deductibles, and provincial rules before moving home and car insurance to one provider.
A BMO Insurance life insurance claim usually starts with confirming the policy, contacting the insurer, and submitting proof of death plus beneficiary documents. This checklist explains what to prepare before relying on a payout.
A ruling against Blue Cross Life may influence how Canadian insurers price and administer long-term disability coverage. For most workers, any effect would likely appear through future group benefit renewals.
Climate change is driving home insurance premiums higher across Canada as insurers face mounting claims from floods, wildfires, and severe weather events.
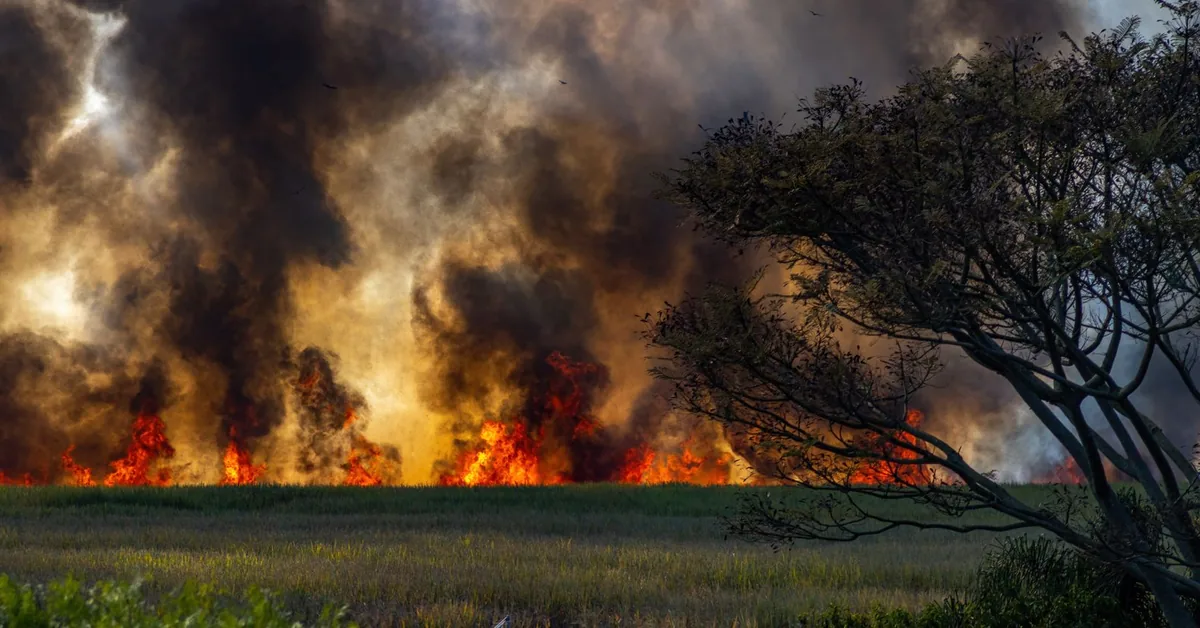
Wildfires are increasing property claim costs, changing underwriting, and putting pressure on home insurance availability in parts of Canada. Here is what that means for insurers and households.
Income replacement insurance can help replace part of your paycheque if illness or injury keeps you from working. The right monthly benefit starts with your real after-tax spending, not just your gross salary.
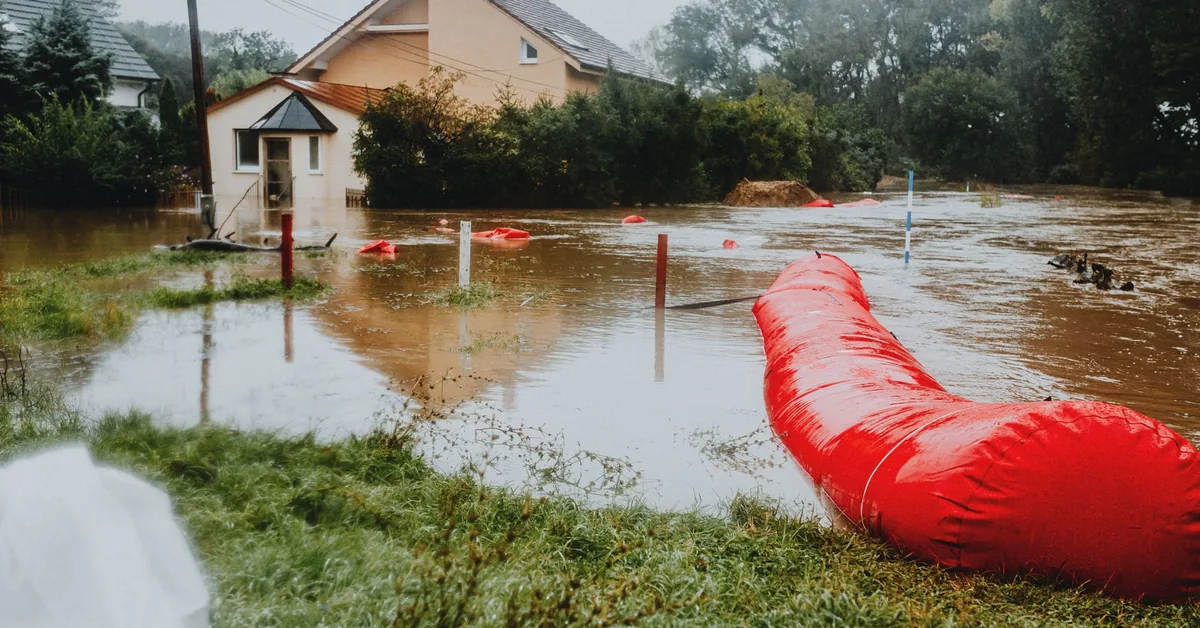
Canada does not have a U.S.-style federal flood insurance policy for homeowners. Most Canadians need to confirm whether overland water, sewer backup, and related flood damage are covered by their own home insurance policy.
While weather forecasts and disaster predictions inform long-term risk modeling, they do not directly reduce home insurance premiums in Canada; rates are primarily set using historical claims data and actuarial analysis.
Canadian homeowners face increasing flood risk from spring melt, heavy rain, and coastal storms. Here's when to buy overland flood coverage and why timing matters.
Canadian extended health insurance enrollment has hit an all-time high, with over 2.3 million individuals enrolling in supplementary coverage plans in 2026, driven by rising healthcare costs and expanded employer benefits.
Rising premiums driven by floods, wildfires, and severe weather are pushing some Canadian homeowners to reduce or drop insurance coverage, leaving them exposed to major financial losses.
As severe weather risks increase across Canada, homeowners face important decisions about overland water and flood coverage.
Canadian families face rising extended health insurance premiums, but provincial and federal assistance programs can help reduce costs for those who qualify.
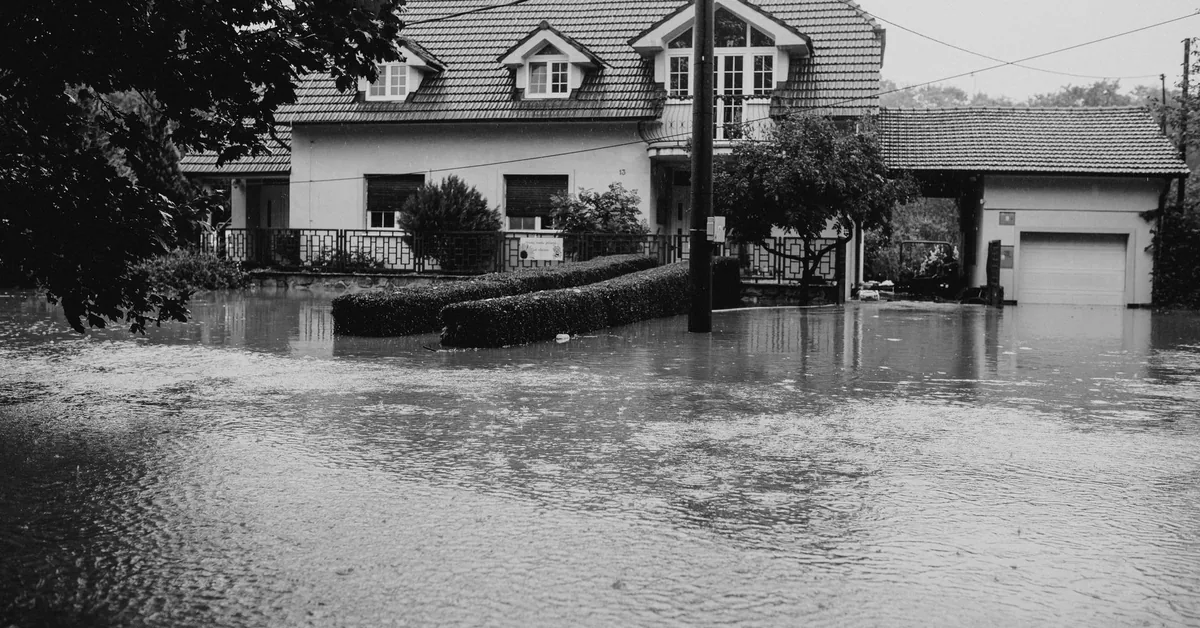
Standard home insurance does not cover overland flooding in Canada. Learn what overland water coverage protects, how to get it, and what limits apply.
Standard home insurance has limits on jewelry and valuables. Learn how to protect high-value items with riders and scheduled personal property endorsements.
CTP (third-party liability) coverage is the mandatory component of auto insurance in Canada that pays for damage and injuries you cause to others.
Overland water coverage protects Canadian homeowners from flood damage that standard home insurance excludes. Learn how to secure flood insurance before spring runoff and storm season begins.
Tenant insurance is not legally required in Canada, but many landlords now include it as a lease condition.
Third party liability insurance covers bodily injury and property damage you cause to others in a car accident, and it is mandatory in every Canadian province and territory.
Learn how insurance deductibles work in Canada, how they affect your premiums, and how to choose the right deductible for your home and auto coverage.

Professional liability insurance protects Canadian small businesses and self-employed professionals from claims of negligence, errors, or omissions in their professional services.

Learn how to select the right auto insurance coverage in Canada by understanding mandatory and optional coverages, comparing provincial requirements, and matching protection to your driving situation.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
