Insurance
ACA Open Enrollment 2027 in the US: Deadlines and How to Compare Plans
Learn the critical deadlines for ACA open enrollment 2027 and how to compare health plans to find the best coverage and savings for your needs.
UmbrellaOwl / Insurance
Learn the critical deadlines for ACA open enrollment 2027 and how to compare health plans to find the best coverage and savings for your needs.
The ACA open enrollment period for 2027 coverage is now open. Learn about the key changes, deadlines, and what to review before selecting your health insurance plan.
Compare COBRA continuation and ACA marketplace plans to find the most affordable health coverage after losing your job.
Learn how to save money by bundling auto, home, and business insurance before your January renewal deadline.
The Medicare Annual Enrollment Period ends December 7. Review this checklist to verify your coverage, compare plans, and submit any changes before the deadline.
Federal subsidy rules and income thresholds determine how much help you get with marketplace premiums. Understanding the changes for 2027 can save you hundreds of dollars a month.
Compare Medicare Advantage and Original Medicare to decide which coverage fits your health needs, budget, and provider preferences for 2027 enrollment.
Medicare Annual Enrollment Period runs through December 7, 2026. Review five critical coverage and cost decisions that lock in your 2027 benefits.
Medicare Open Enrollment runs from October 15 through December 7 each year, giving you a chance to review and change your Medicare Advantage and Part D prescription drug coverage for the following year.
Cyber risk insurance protects US businesses from financial losses caused by data breaches, ransomware attacks, and other digital threats. This guide explains what coverage includes, who needs it, and how to choose the right policy.
Medicare's annual Open Enrollment period runs October 15 through December 7. Learn how to review your coverage, compare plans, and make informed changes for the year ahead.
Compare Medicare Part D prescription drug plans for 2027 by evaluating premiums, formularies, coverage gaps, and pharmacy networks to find the best fit for your medication needs.
Medicare's Annual Enrollment Period runs from October 15 through December 7 each year, giving beneficiaries a critical window to review and change their coverage for the following year.
Health insurance premiums climbed 9% for 2026, leaving millions of Americans struggling to afford coverage and expanding the ranks of the uninsured.
Understanding what the $28,000 threshold for employer health insurance premiums means for American workers and families.
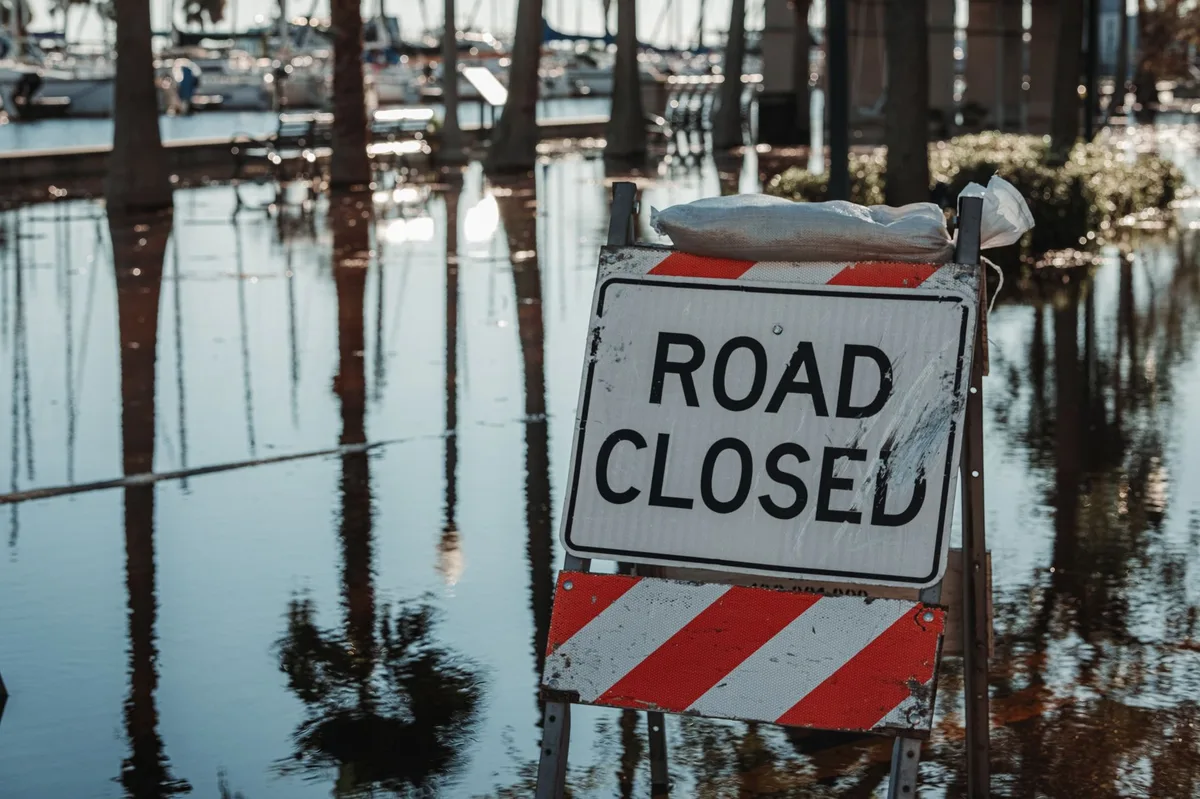
Hurricane season brings flooding risk that standard homeowners policies do not cover. Learn why federal flood insurance matters and how to secure coverage before the next storm.
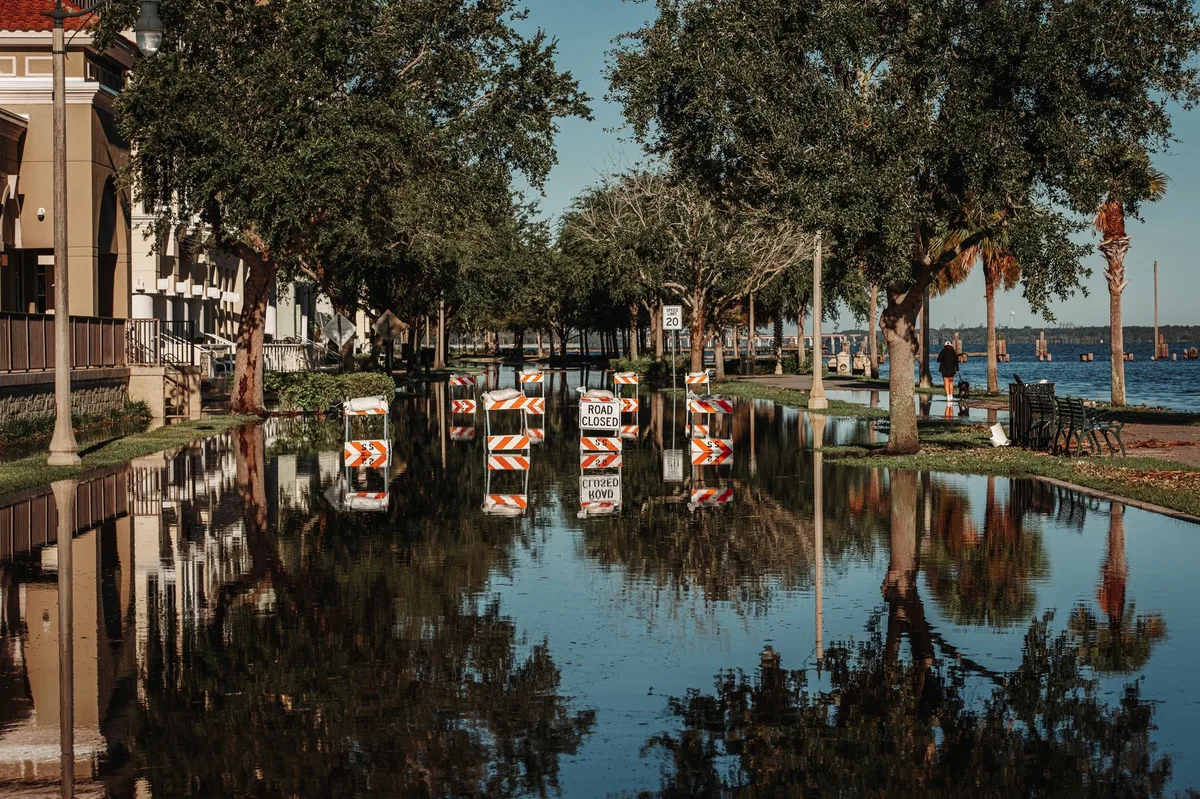
Florida homeowners can buy insurance during hurricane season, but coverage availability depends on whether a named storm is approaching and the type of policy you need.
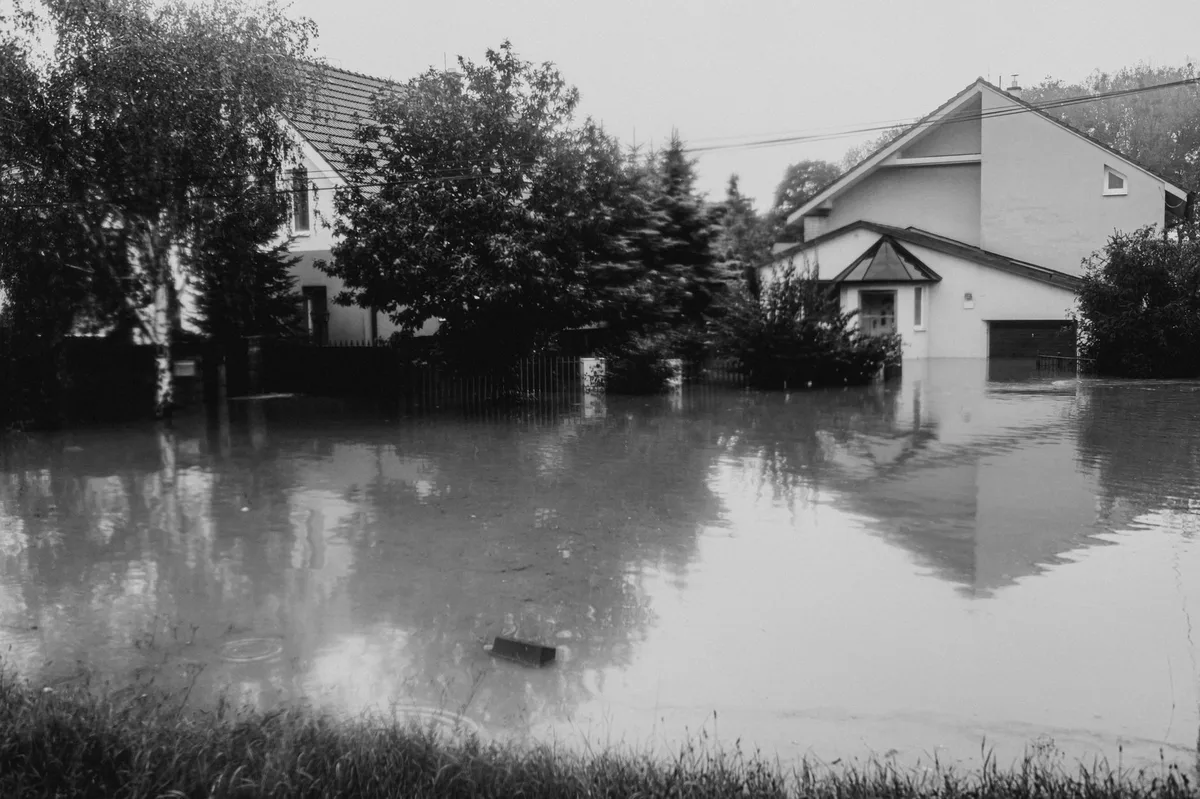
A step-by-step guide to getting flood insurance coverage before hurricane season, including waiting periods, NFIP vs private options, and essential coverage decisions for US homeowners.
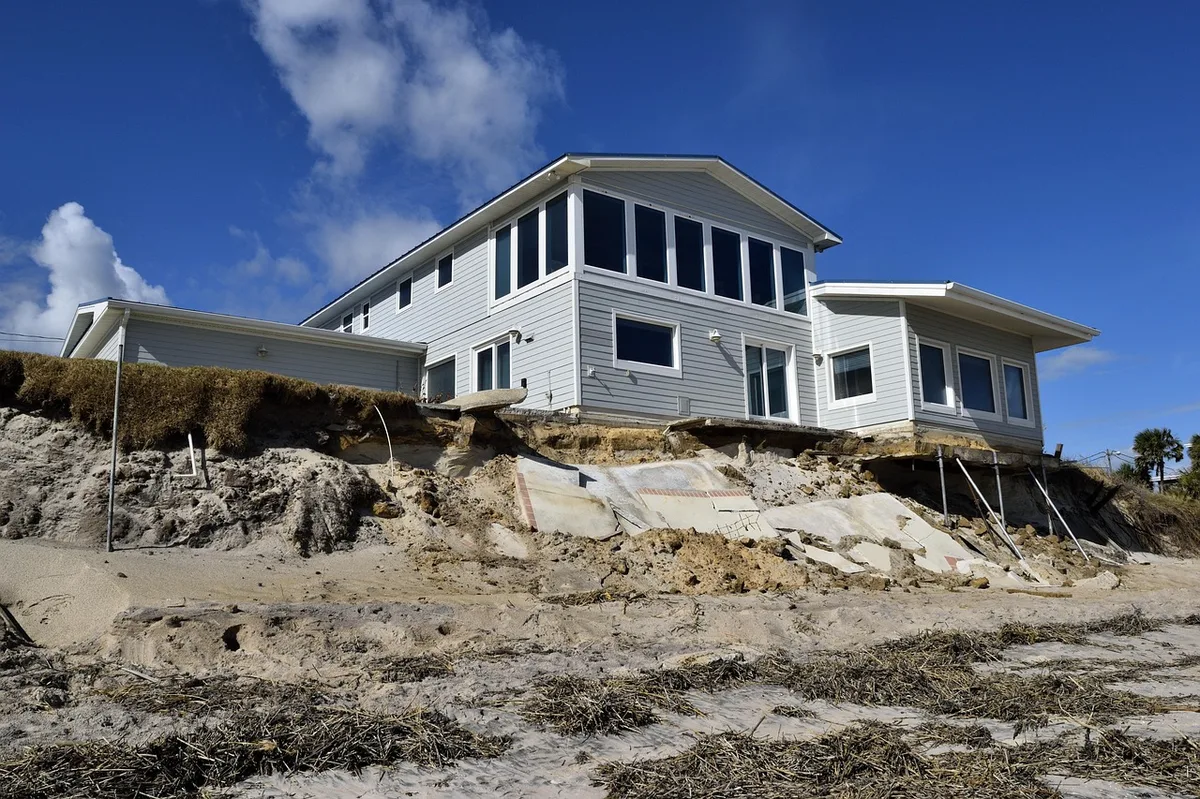
Claims about a mandatory $1,000 hurricane tax on Florida homeowners insurance have circulated widely. We fact-check the proposal and explain what it actually means for policyholders.
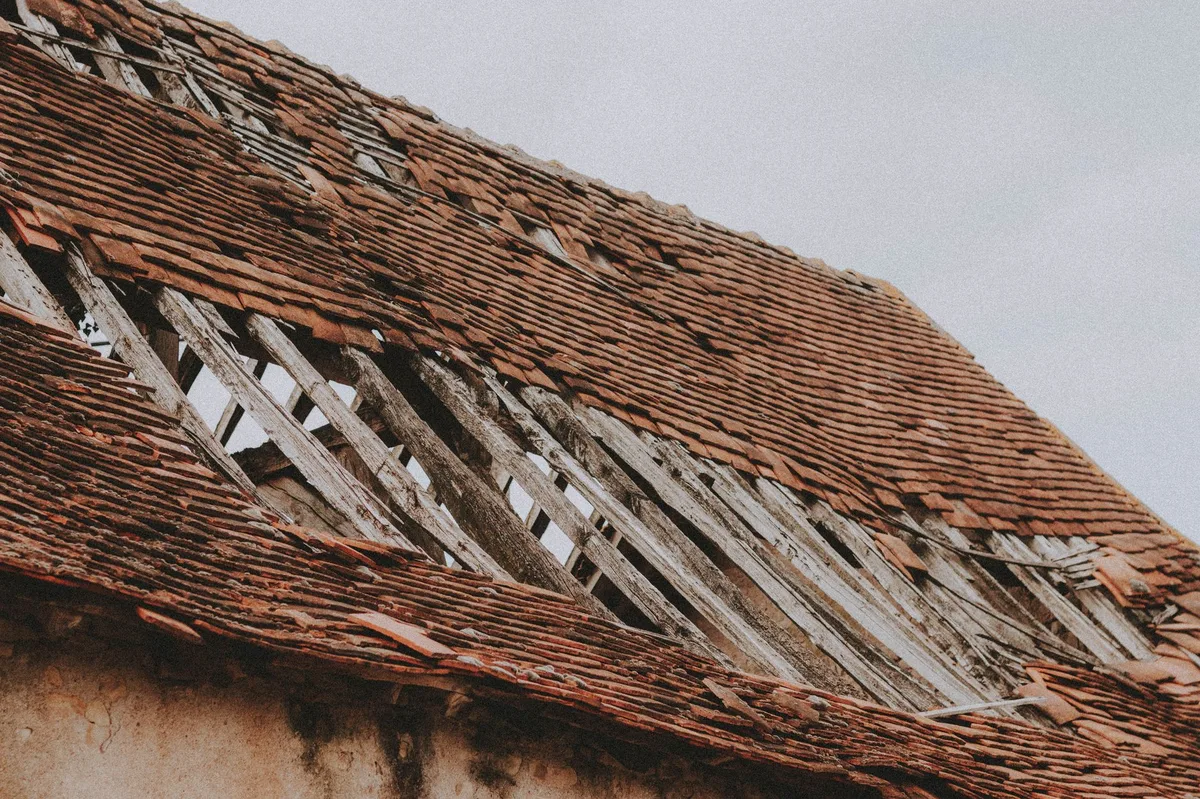
Learn what severe weather damage your homeowners insurance covers and how to file a successful claim after a storm, hurricane, or hail event.
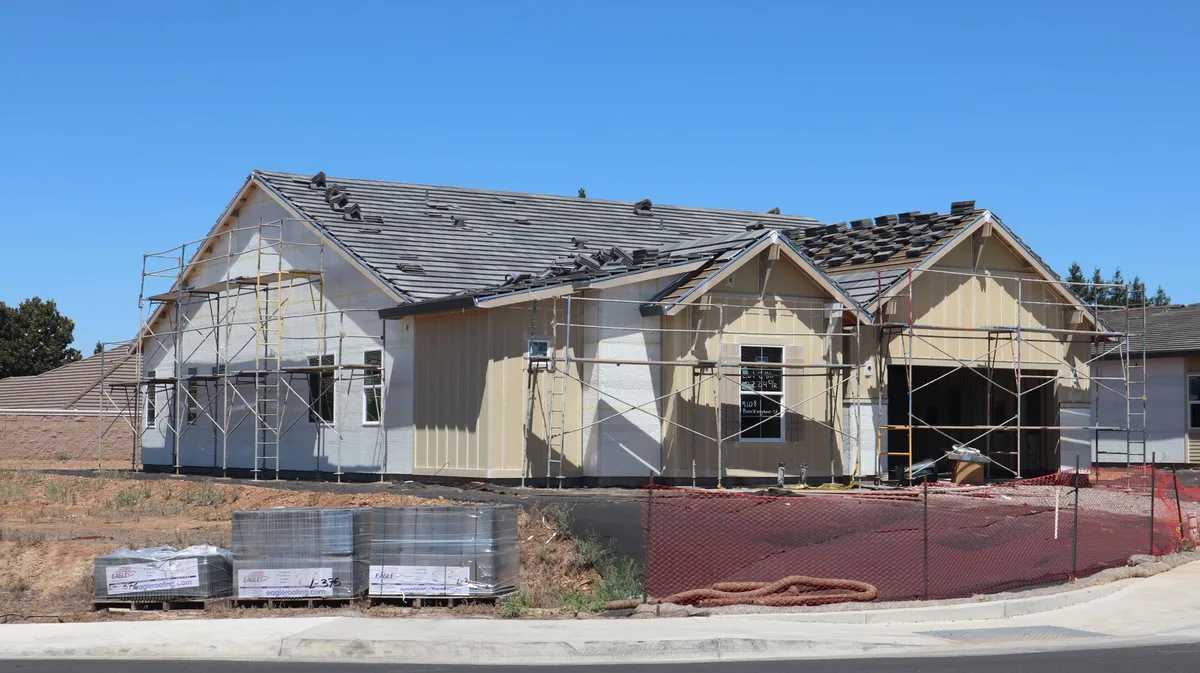
California homeowners face historic insurance cost increases as carriers respond to escalating wildfire exposure and catastrophic loss patterns across the state.
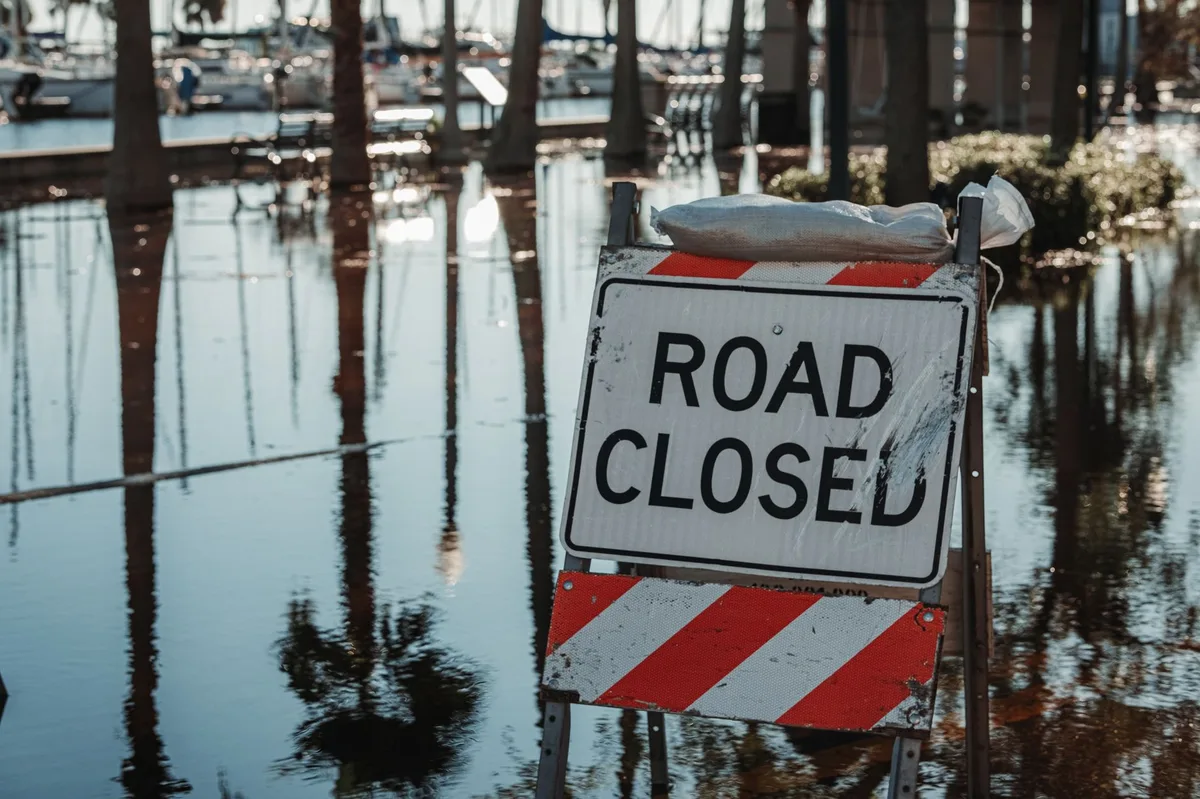
Hurricane season brings heightened flood risk to Florida. Learn who is required to carry flood insurance, who should consider it, and how to assess your risk in the Sunshine State.
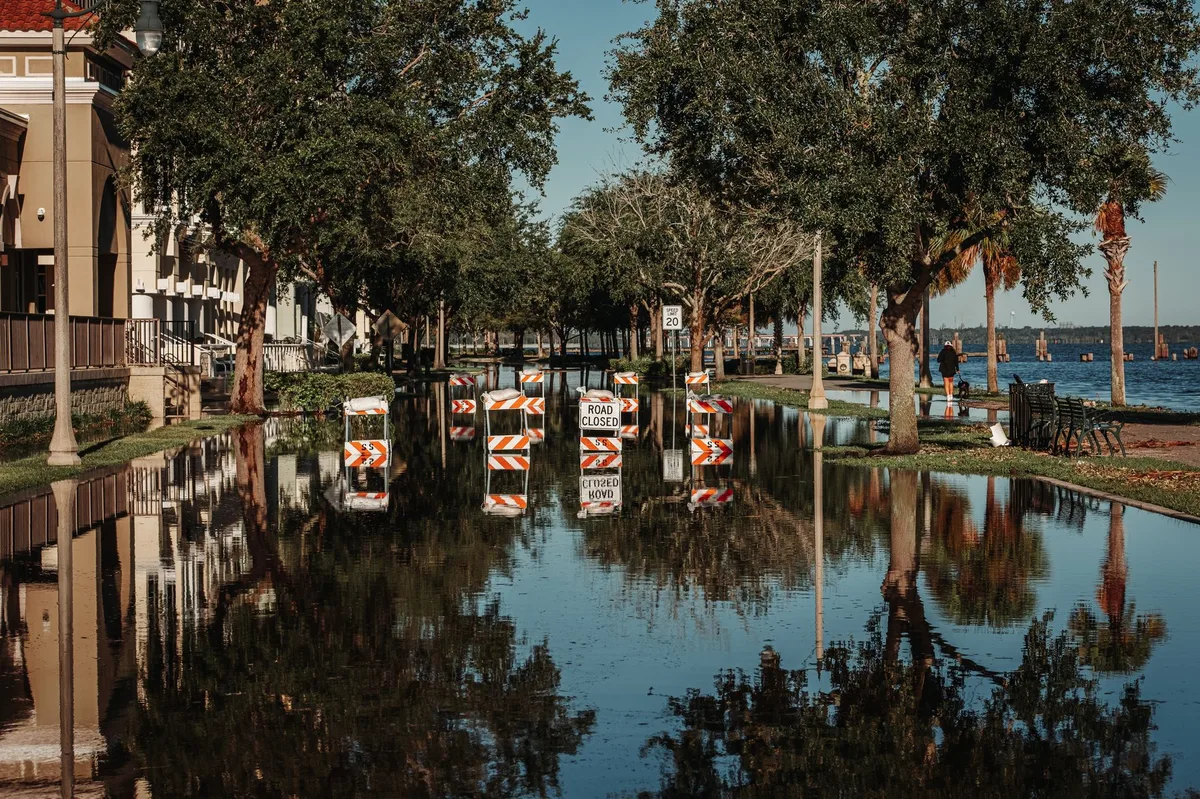
Rising costs and federal rate changes drive record flood policy cancellations in Texas, leaving homeowners exposed ahead of hurricane season.
Understanding what your homeowner's insurance covers when trick-or-treaters visit your property during Halloween, from liability claims to property damage.
A quiet hurricane season does not eliminate flood risk. Understand when flood coverage is essential and how NFIP policies protect against damage standard homeowners insurance excludes.
Marketplace enrollment has declined as premium costs surge beyond affordability for many households, particularly those earning too much to qualify for subsidies.
Soaring premiums and insurer exits are forcing thousands of Florida homeowners to drop coverage or turn to the state's last-resort insurer as hurricane risk reshapes the market.
Hurricane season brings storm risks and costly coverage misconceptions. Learn which common homeowners insurance myths about hurricane and flood protection could leave you financially exposed.
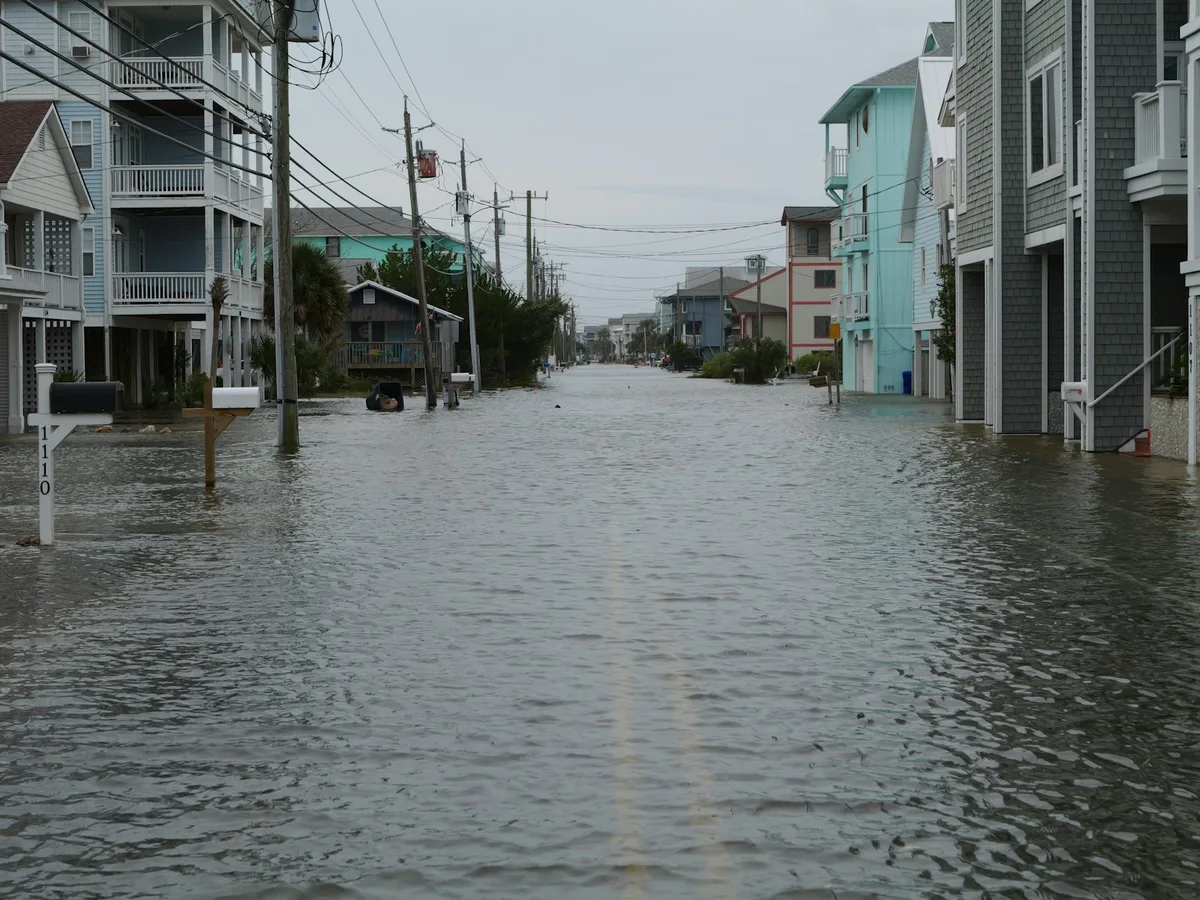
Learn about the 30-day waiting period for flood insurance, exceptions during hurricane season, and critical timing rules Houston homeowners must understand before storm season arrives.
Learn about critical hurricane insurance coverage gaps that leave homeowners and businesses exposed, and how to protect your property from storm-related financial losses.
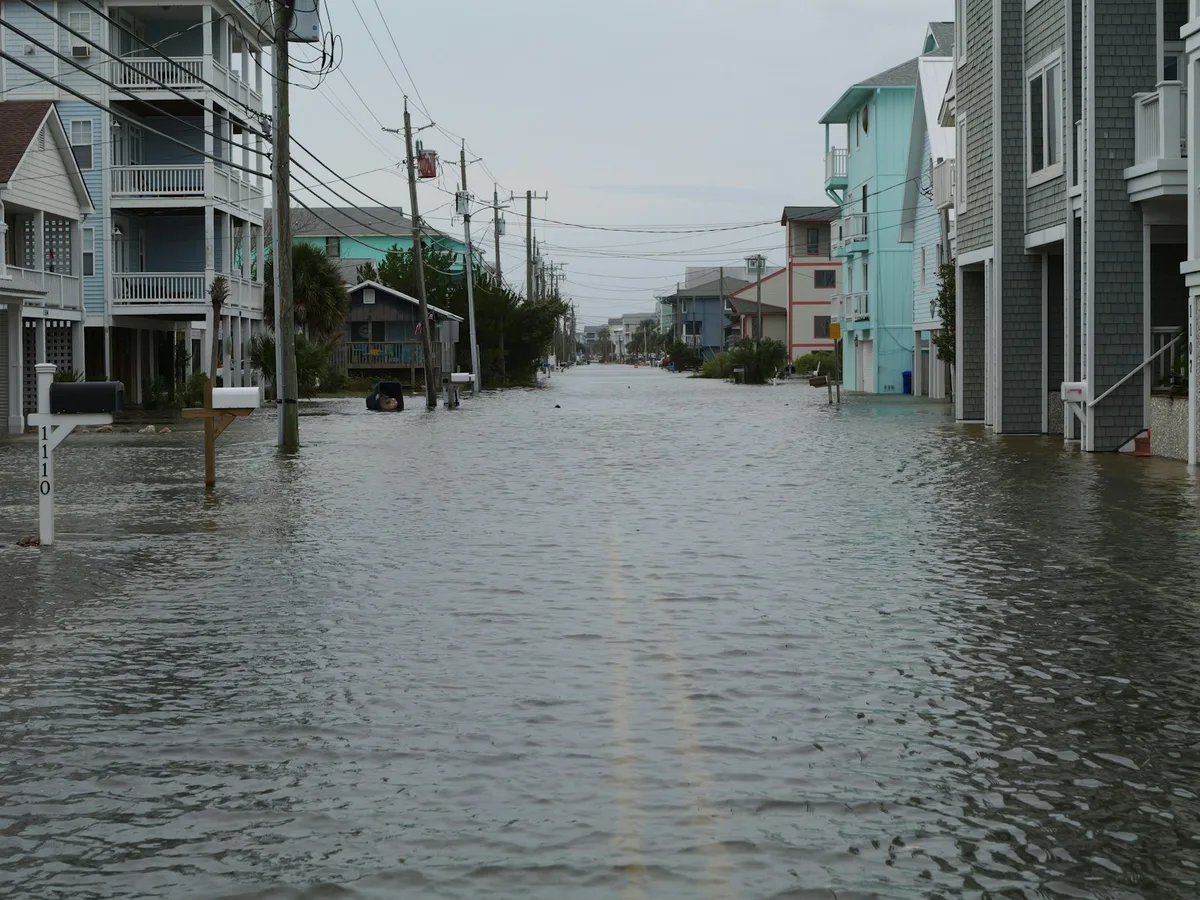
Florida homeowners face potential changes to the National Flood Insurance Program as hurricane season approaches, with reforms and rate adjustments that could affect coverage costs and availability.
Houston homeowners face a critical deadline: NFIP flood insurance policies have a 30-day waiting period, and hurricane season starts June 1.
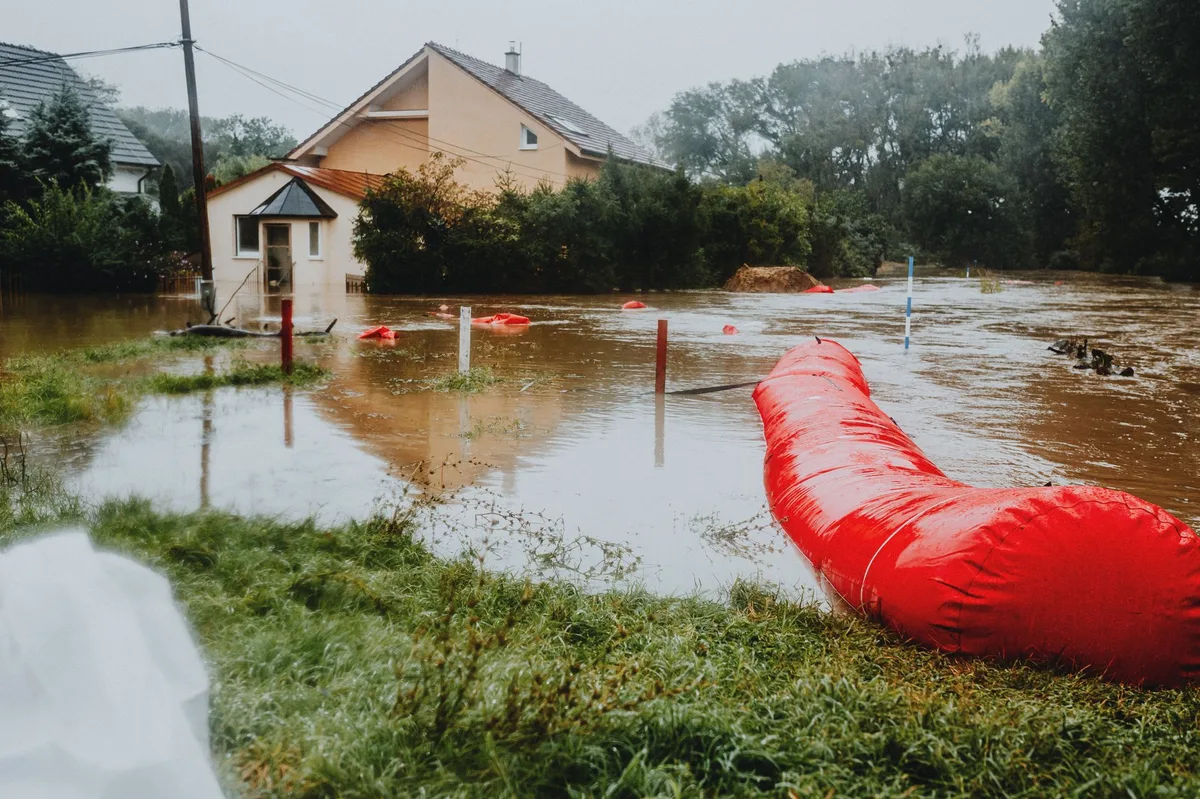
South Florida homeowners face mounting flood risks as hurricane season approaches, making the flood insurance decision critical for protecting property and finances.
A practical checklist to help you select auto insurance coverage that protects you financially while fitting your budget and driving profile.
Learn the step-by-step process to switch Medicare plans during enrollment periods while maintaining continuous coverage.
Term life covers you for a set period at lower cost, while whole life lasts your lifetime and builds cash value. Learn which fits your needs.
Medigap can fill costly Medicare gaps, but premiums vary widely. Learn when supplemental coverage pays off and when you may not need it.
Understanding how to designate beneficiaries and how life insurance payouts work ensures your loved ones receive the financial protection you intend.
Learn the proven method to compare auto insurance quotes fairly, avoid common pitfalls, and choose coverage that protects you without overpaying.
Practical strategies to reduce your auto insurance costs while maintaining the protection you need.
Learn what renters insurance covers, why first-time renters need it, and how to calculate the right coverage amount for your personal property and liability protection.
Learn how insurance deductibles work and their direct impact on premium costs across auto, home, and health coverage.
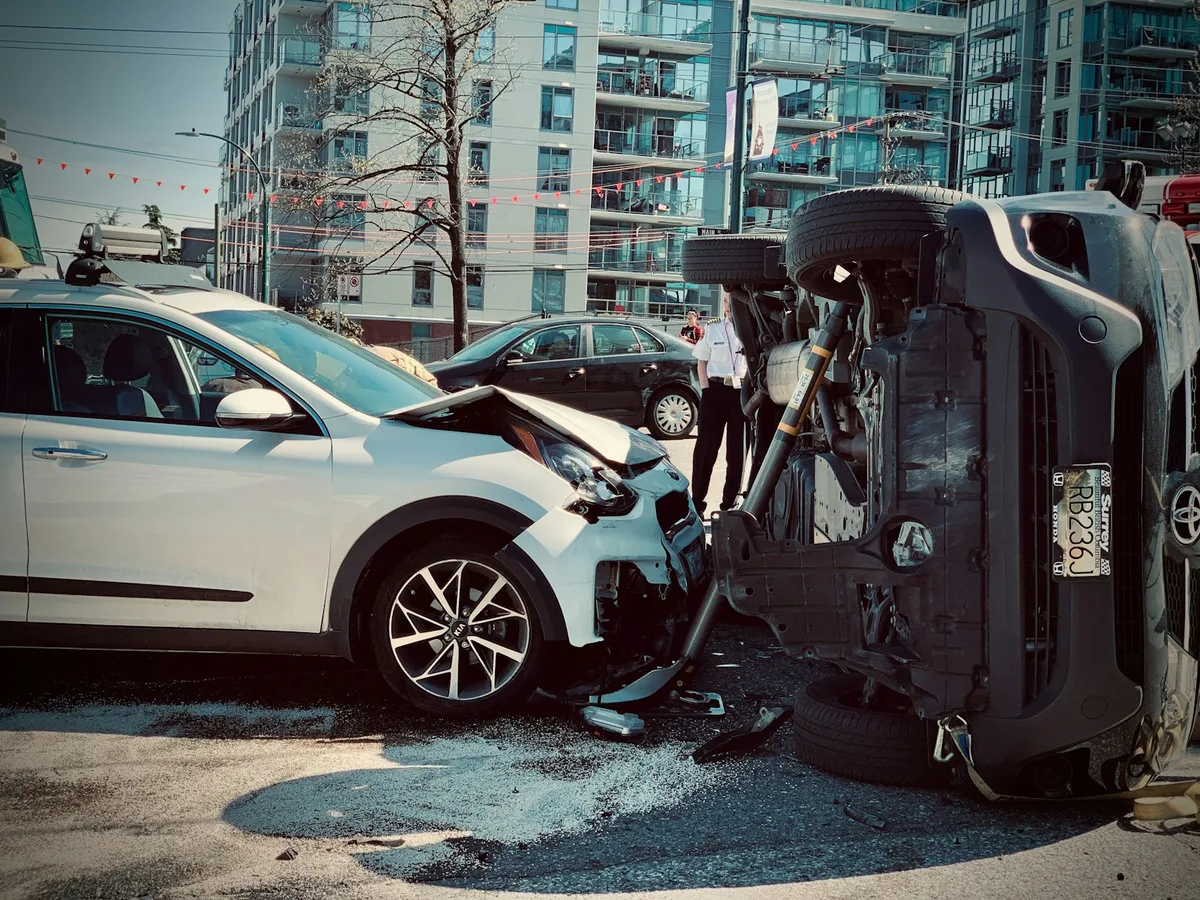
Step-by-step guide to filing an auto insurance claim after an accident, from documenting the scene to working with adjusters and getting your vehicle repaired.
Learn how to calculate the right amount of homeowners insurance coverage for your dwelling, personal property, and liability needs based on replacement cost and risk factors.
NFIP flood insurance comes with a mandatory 30-day waiting period before coverage starts, leaving you unprotected if you wait until storms approach.
Prepare your home for winter and close critical insurance coverage gaps before the first freeze hits.
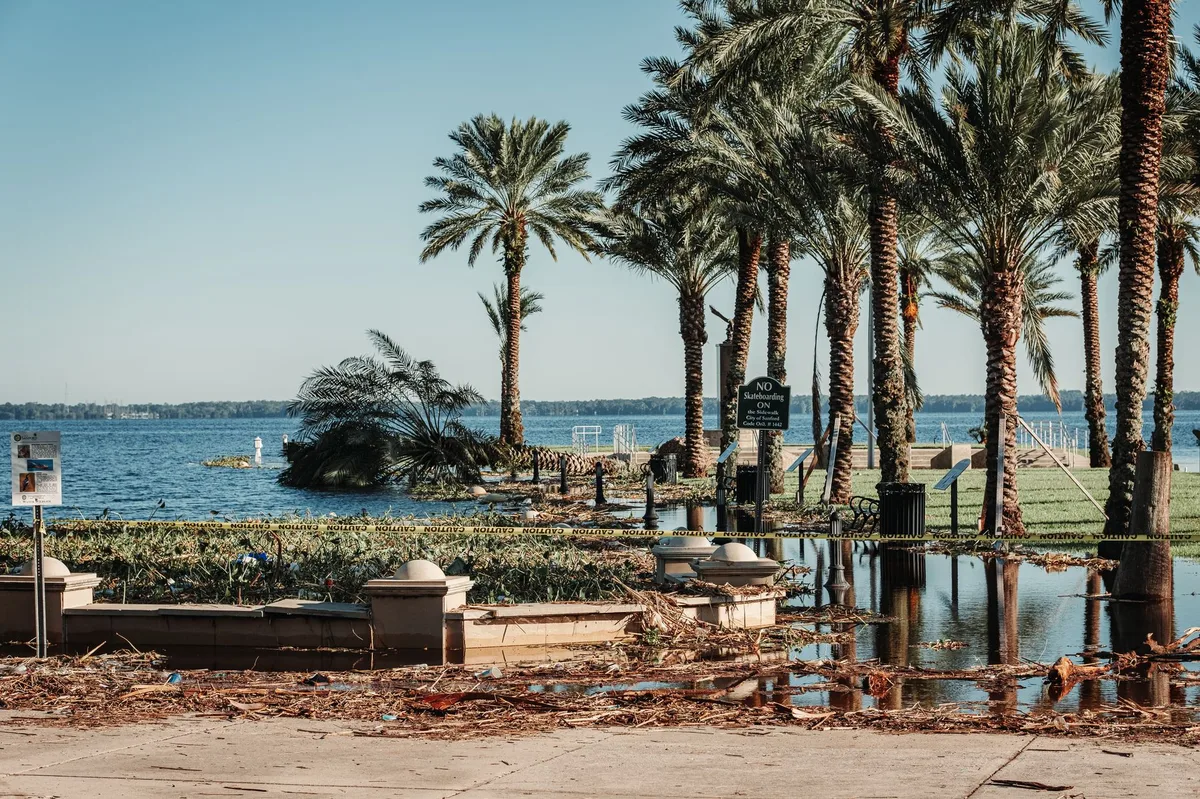
After a hurricane passes, filing an insurance claim quickly and correctly helps you recover faster. Learn the essential steps to document damage and work with your insurer.
Open enrollment is your chance to review and adjust your workplace life insurance. Here is what to verify before the deadline.
A practical checklist to review your auto insurance coverage before winter weather arrives, ensuring you have the right protection for hazardous driving conditions.
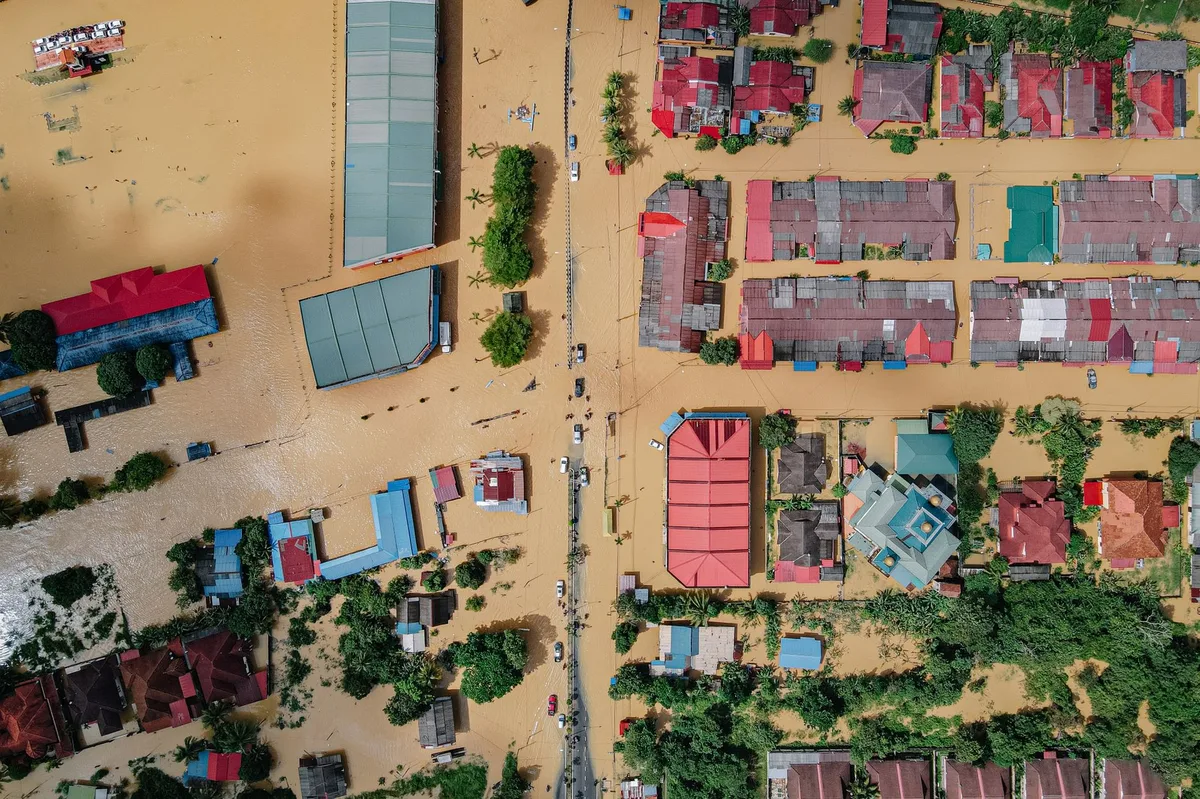
Standard homeowners insurance excludes flood damage. Learn what flood insurance covers, why you need separate protection, and how to get NFIP or private flood coverage.
Gap insurance covers the difference between what you owe on a car loan and the vehicle's actual cash value if it's totaled or stolen.
Most identity theft insurance policies offer limited value because they reimburse costs you can already dispute for free. Here's what coverage is worth having and what you can skip.
August marks peak hurricane season in the US. Use this checklist to verify your home insurance coverage is ready before the next storm.
Key person insurance helps businesses survive the financial impact of losing a critical owner, executive, or employee through life insurance coverage.
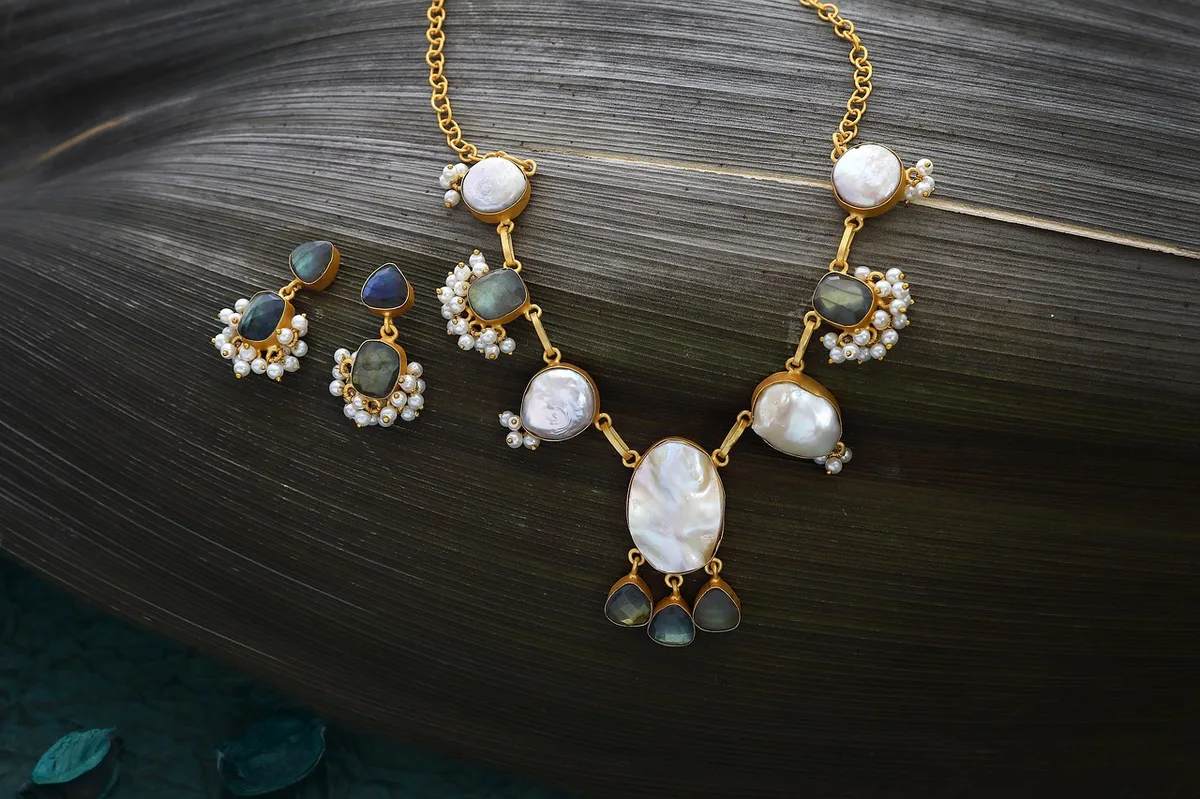
Standard homeowners and renters policies cap coverage for jewelry, art, and collectibles. Learn how scheduled personal property endorsements and appraisals protect your valuables.
Learn how auto, home, and other insurance claims impact your premium when your policy renews, and what you can do to minimize rate increases.
The coinsurance clause can reduce your home insurance payout if you under-insure. Learn how it works and how to avoid claim penalties.
Learn the key differences between joint and separate life insurance policies for married couples in the United States, including costs, coverage options, and how to decide which approach fits your family's financial goals.
Learn when cancelling your US insurance policy mid-term makes financial sense despite short-rate penalties, and get a practical checklist for managing the switch.
Personal auto insurance typically excludes business use, leaving drivers unprotected when using their vehicle for work. Understanding the line between personal and commercial coverage is critical for compliance and financial protection.
E&O insurance covers professional mistakes and advice, while general liability protects against physical injury and property damage. Most US freelancers need both for complete protection.
Your first hire triggers mandatory workers compensation coverage in most states, bringing new compliance duties, premium costs, and legal obligations you did not face as a sole proprietor.
Compare the accelerated death benefit (ADB) rider most US life insurance policies include against viatical settlements and cash value loans when facing a terminal diagnosis.
Learn how an ILIT removes life insurance from your taxable estate and protects what your heirs receive.
Usage-based car insurance can cut premiums by monitoring your driving, but sharing detailed location and behavior data raises privacy concerns worth weighing before you enroll.
Compare low, medium, and high deductibles to understand how your choice affects what you pay monthly and what you owe when you file a claim.
Learn how non-owner car insurance provides liability coverage when you regularly drive cars you don't own, and estimate whether you need this specialized policy.
Safe-driver discounts reward clean driving records with lower premiums, but violations and accidents can erase savings quickly.
Essential insurance reviews college students and families should complete before heading to campus, from health coverage to renters policies.
Long-term care can cost $100,000 or more per year in the US. Learn how to estimate nursing home, assisted living, and home care expenses for your situation.
Use a calculator-based approach to determine the right amount of life insurance coverage to protect your family's financial future if you pass away.
Learn how to determine the right monthly disability insurance benefit amount to protect your income if illness or injury keeps you from working.
Understand how FEMA flood zones determine your National Flood Insurance Program premium and use our calculator to estimate your annual cost.
Learn how to determine the right amount of personal property coverage for your renters insurance policy using proven estimation methods.
Calculate and compare your total out-of-pocket costs under Medicare Supplement Plans G, N, and F to find the best coverage for your budget and healthcare needs.
Long-term care insurance helps cover nursing home, assisted living, and in-home care costs that Medicare does not pay for. Planning early can save thousands and protect your assets.
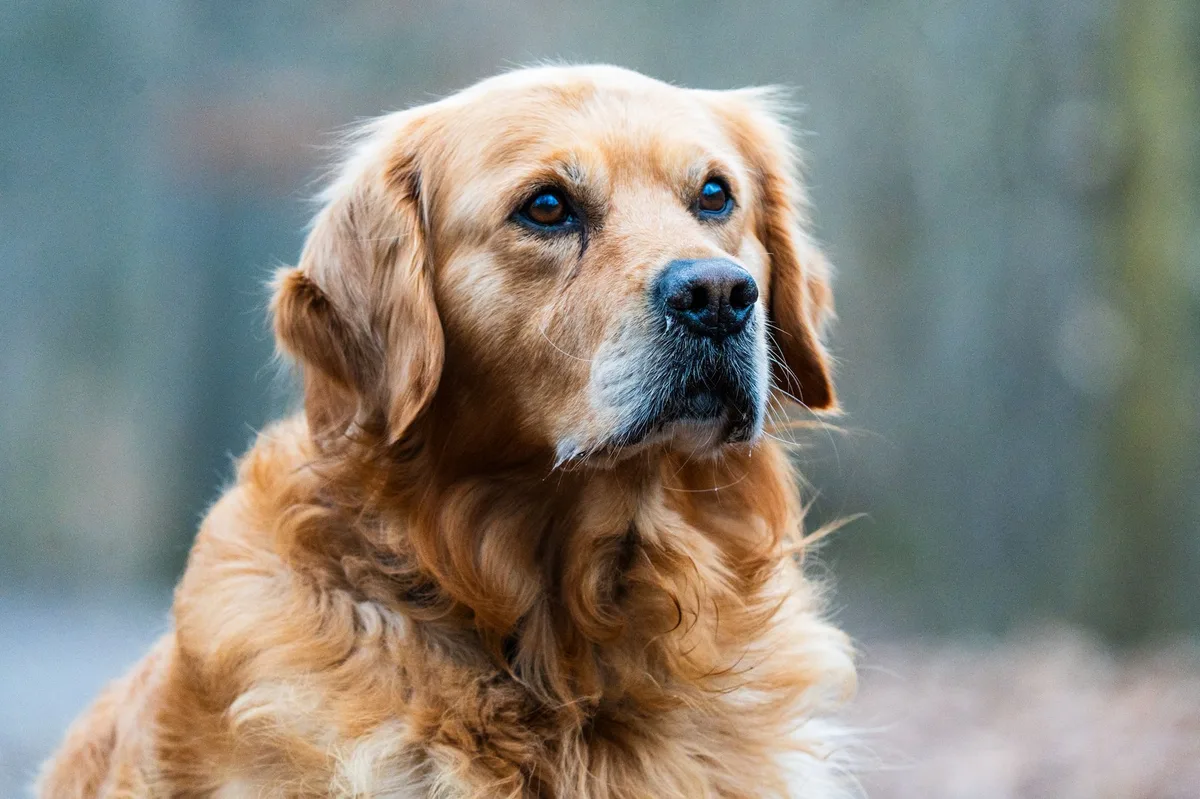
Understand the factors that determine pet insurance premiums for dogs and cats, from breed and age to coverage level and location.
Learn how to use a travel insurance calculator to determine the right coverage amount for your trip based on trip cost, destination, activities, and health needs.
Learn how to determine the right monthly disability benefit to protect your salary if illness or injury prevents you from working.
Understand the key differences between Medicare supplement Plan G, Plan N, and Plan F to choose the right coverage for your healthcare needs.
Understand the factors insurers use to calculate your car insurance premium and get a personalized estimate.
Travel insurance protects against trip cancellation, medical emergencies, and travel delays, but coverage varies widely and may duplicate benefits you already have.
Learn how to determine the right amount of personal umbrella liability coverage based on your assets, risks, and financial situation.
The income replacement formula estimates life insurance needs by multiplying annual income by years of support needed, adjusted for debts and savings.
Learn how to calculate the right amount of life insurance coverage for your family's financial security based on income, debts, and future expenses.
Disability insurance and critical illness insurance both offer financial protection, but they work in fundamentally different ways and serve different purposes for US workers.
Understand the key differences between Medicare Advantage and Original Medicare to make an informed coverage decision for 2027.
Long-term care insurance helps cover the cost of custodial care when you can no longer perform daily activities independently. Here is when to buy it and how to size your coverage.
Learn when bundling home and auto insurance saves money and when separate policies might be better for your coverage needs.
Major life changes require immediate insurance updates to protect what matters most.
Compare ACA marketplace plans and COBRA continuation coverage after losing your job, including costs, subsidies, and enrollment timelines.
Learn the key differences between term and whole life insurance to choose the best coverage for your family's financial protection needs.
Understanding the difference between actual cash value and replacement cost coverage can save you thousands when filing a homeowners insurance claim.
Understand the key differences between HMO, PPO, and HDHP health plans to choose the coverage that fits your medical needs and budget.
Bundling home and auto insurance with one carrier typically cuts your combined premiums by 15% to 25%, with additional benefits like simplified billing and a single point of contact for claims.
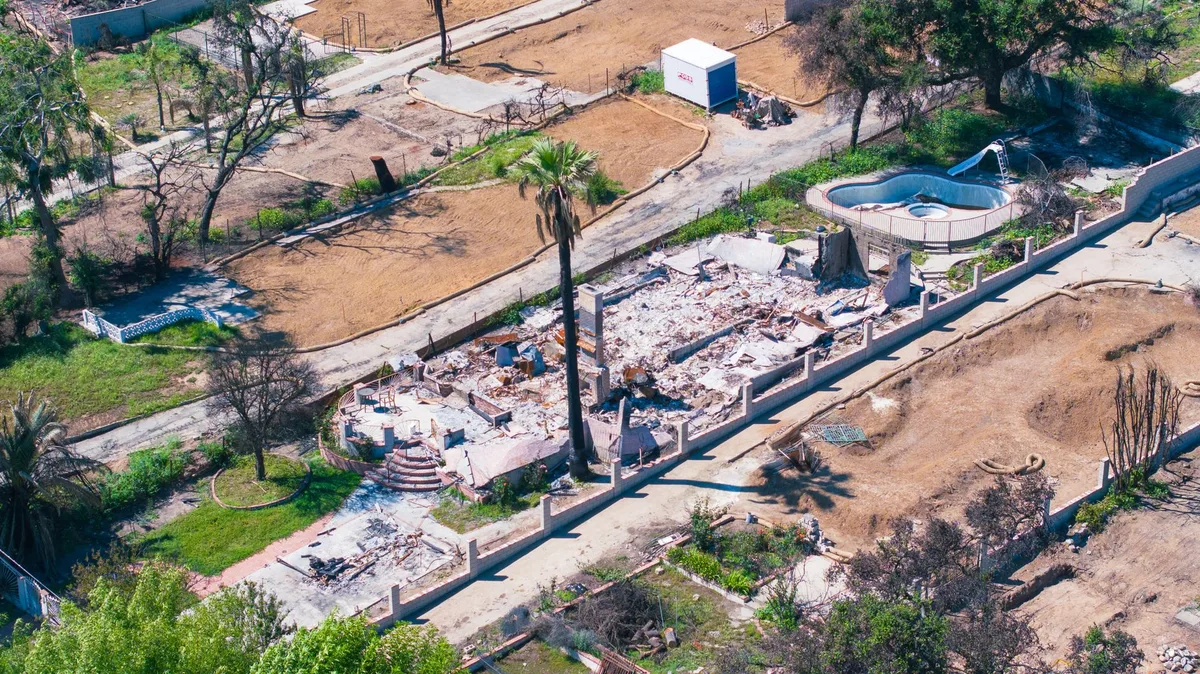
California homeowners face serious wildfire coverage gaps as insurers retreat. State programs offer limited help, but costs are rising and options are shrinking.
Off-campus students need renters insurance to protect belongings and cover liability. Learn what coverage to buy, what it costs, and whether your homeowners policy already extends to your student.
Learn the key differences between BOP and general liability coverage, and find out which protection your small business actually needs.
Pet insurance can cost $30 to $100+ per month - learn when the coverage pays off and when you are better off self-insuring.
Learn what disability insurance covers, how much you need, and how to choose between short-term and long-term policies to protect your income.
Compare umbrella liability coverage levels and learn which amount fits your assets, risk exposure, and budget.
Summer brings unique driving hazards, from road trips to extreme heat. Learn how to protect your auto insurance coverage during the season's peak driving months.
Hurricane season reveals critical flood coverage gaps that catch many homeowners off guard. Learn the seven most common shortfalls before disaster strikes.
Boat insurance protects your watercraft and liability exposure during summer recreation. Learn what coverage you need, typical costs, and when it's required.
Learn the essential steps to document storm damage, contact your insurer, work with adjusters, and get your claim processed successfully.
Hurricane season 2026 is here. Use this checklist to review your homeowners and flood coverage before a storm hits your area.
Understanding the difference between a Business Owners Policy and Commercial General Liability is crucial for protecting your US-based business.
Learn when pet insurance makes financial sense for US pet owners and how to evaluate coverage options against out-of-pocket veterinary costs.
Learn how to safely reduce your auto insurance premiums in the US by adjusting deductibles and claiming discounts without sacrificing essential coverage.
Learn how your insurance deductible directly affects your premium costs and how to choose the right balance for your budget.
Renters insurance protects your personal belongings, covers liability claims, and pays for temporary housing after a covered loss.
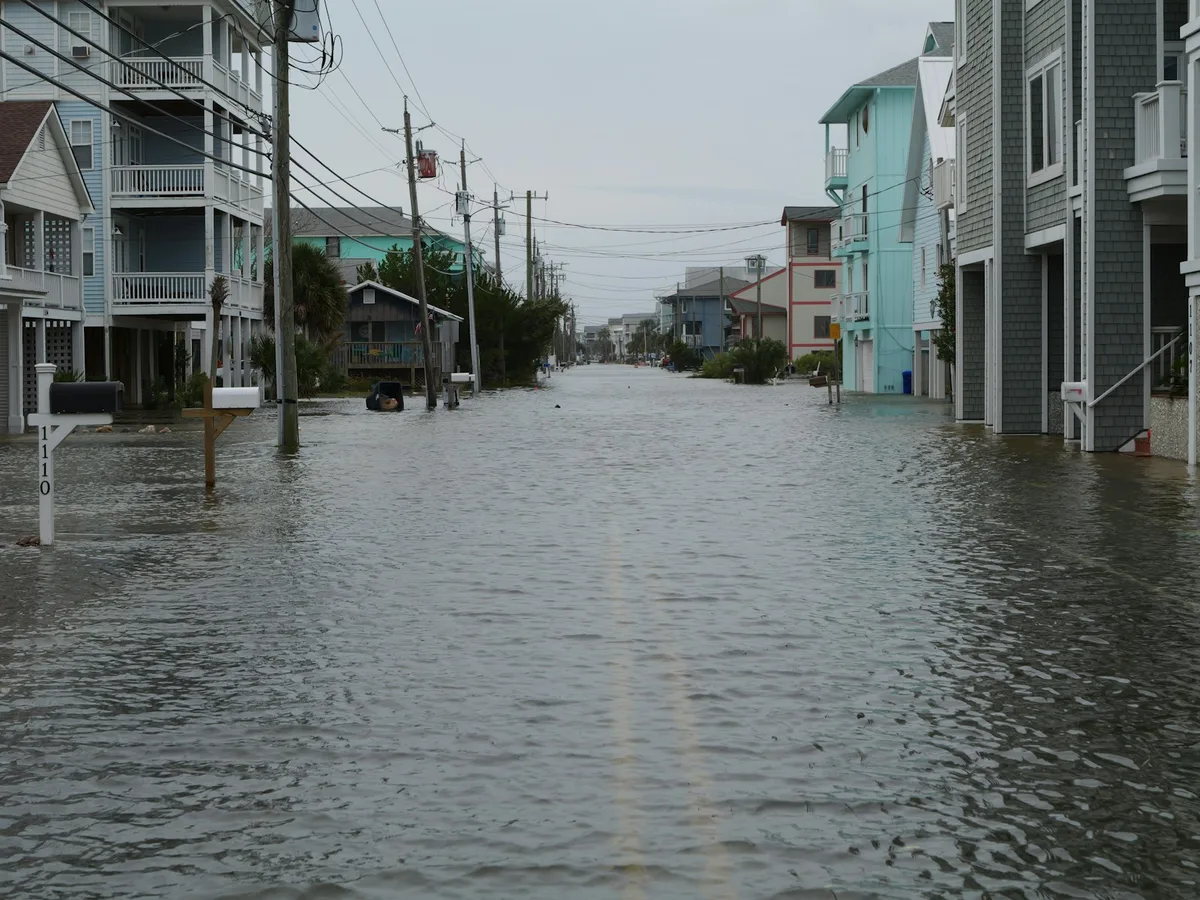
Standard homeowners insurance excludes flood damage. Learn what federal flood insurance covers and why you need separate protection.
Thousands of Louisiana homeowners remain unable to find affordable coverage as the 2026 Atlantic hurricane season gets underway, with the state's insurance market still recovering from years of catastrophic losses and carrier withdrawals.
Compare term and whole life insurance to understand costs, coverage duration, and cash value so you can choose the right policy for your family.
ACA marketplace enrollment has dropped as premium increases outpace subsidies, leaving millions uninsured or seeking alternative coverage options.
Summer driving can raise your exposure to crashes, theft, weather damage, and liability claims. Use this checklist to spot auto coverage gaps before a road trip, teen driving season, or severe weather event.
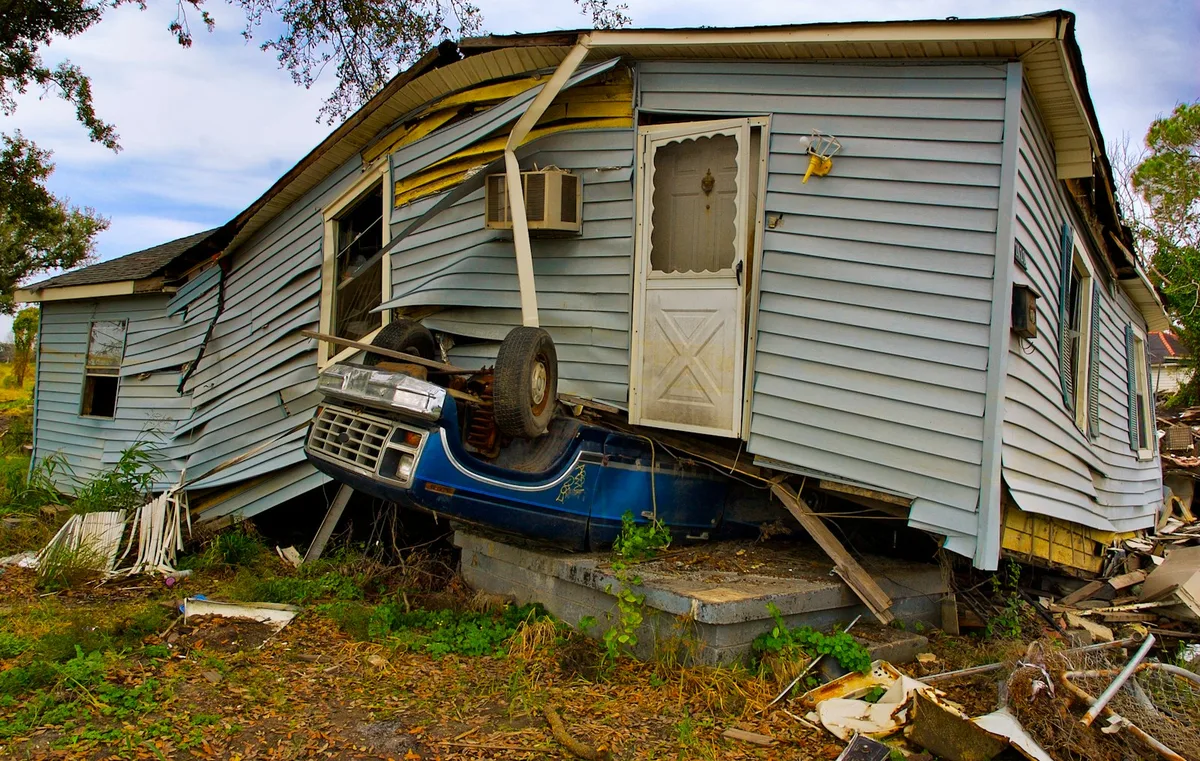
Cutting homeowners insurance before hurricane season can create serious financial risk. Review limits, deductibles, exclusions, and flood coverage before reducing protection.
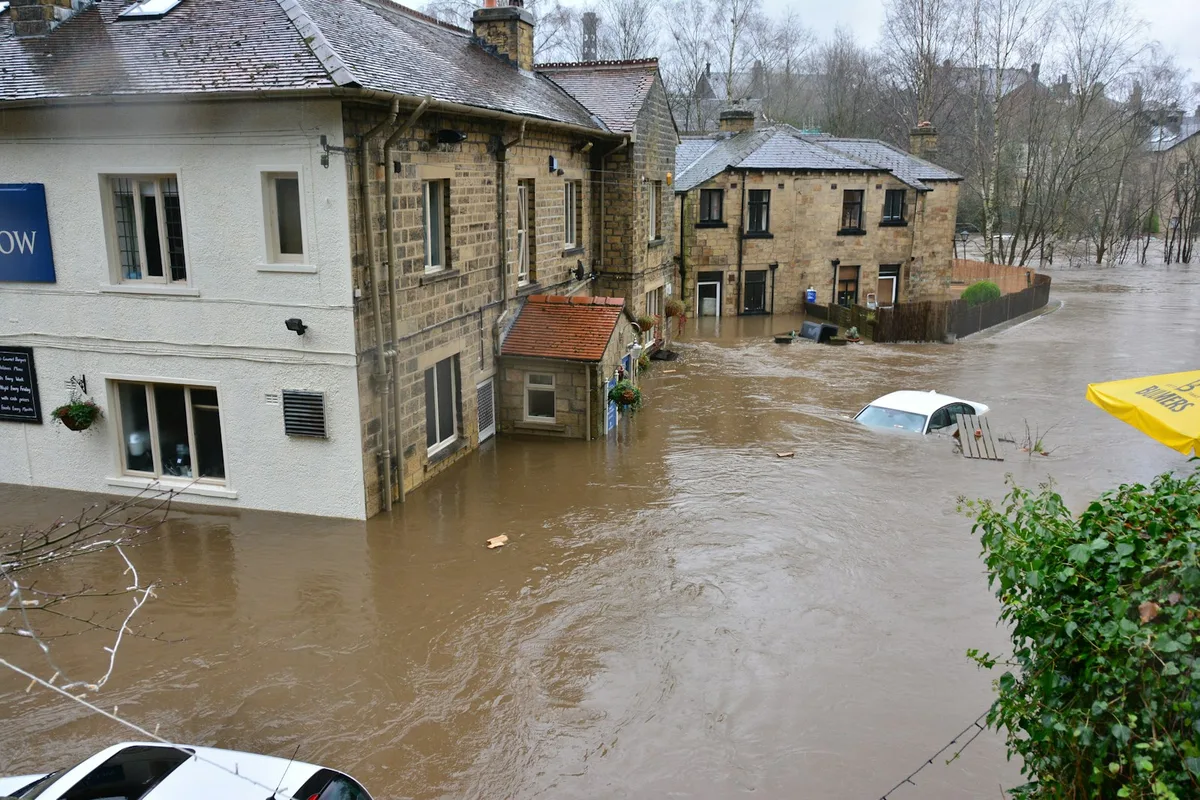
Many homeowners find out too late that standard home insurance does not cover flood damage. Use a flood insurance estimate to see where your hurricane-season protection may be thin.
Review your homeowners insurance before a storm is named. Wind, flood, deductibles, temporary housing, and claim documentation all need separate attention.
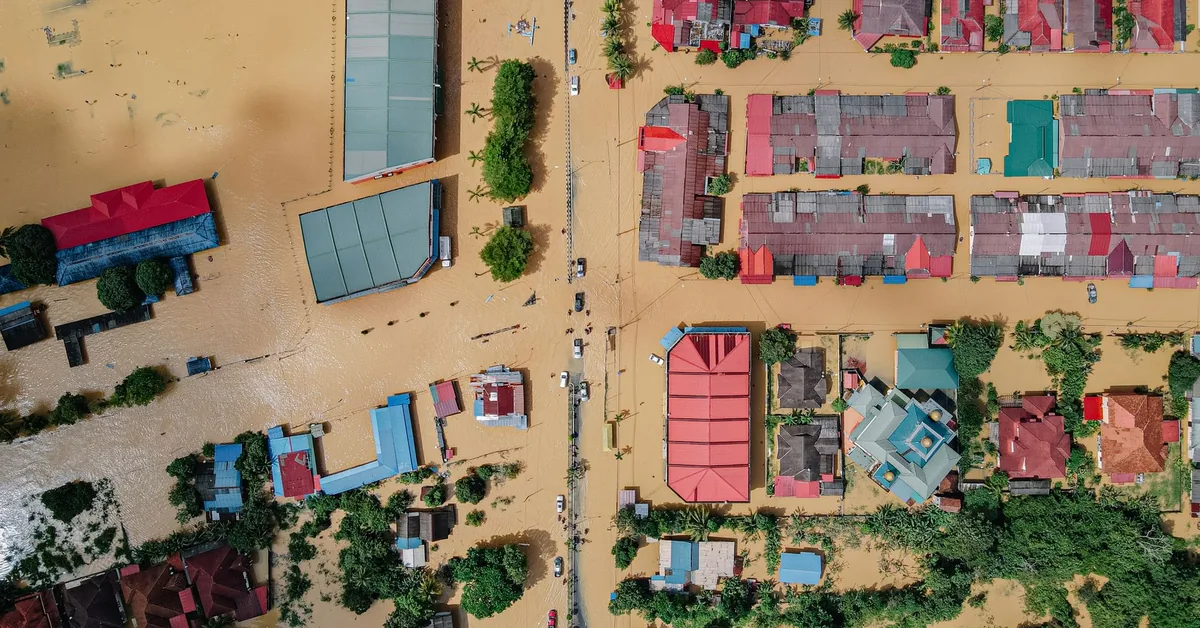
Federal flood insurance can reduce financial shock after a hurricane, but it can also create uneven incentives. The biggest risk for you depends on whether you can afford to rebuild, relocate, or absorb uncovered losses.
A quiet hurricane forecast is not a reason for Florida homeowners to wait. Use this checklist to review coverage, document property, and prepare before a storm is named.

Houston homeowners can usually buy flood insurance before a storm, but coverage rarely starts right away. The standard NFIP waiting period is usually 30 days, so buying during hurricane season may not protect against an imminent storm.
Florida homeowners should check Citizens eligibility, flood insurance requirements, and policy renewal notices before peak storm risk. The biggest 2026 change affects many Citizens policyholders with homes insured for $400,000 or more.
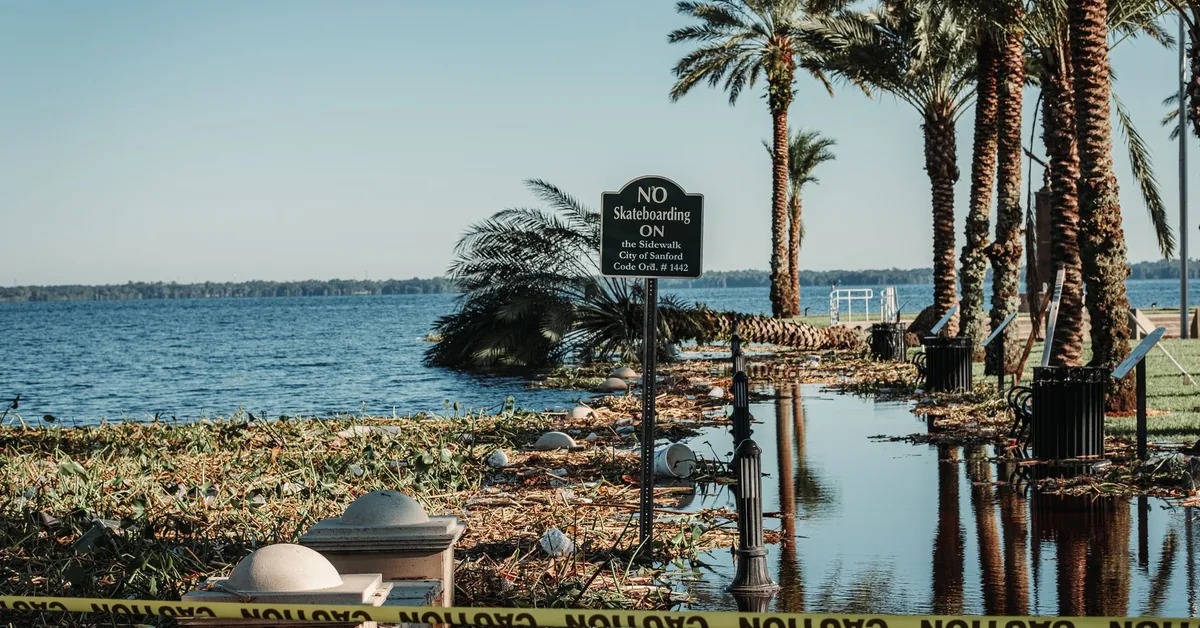
Many Florida residents should consider flood insurance before hurricane season, even outside high-risk flood zones. Standard homeowners and renters policies usually do not cover flood damage.
Rising flood insurance cancellations in Texas are a warning sign for homeowners before hurricane season. The bigger issue is whether households understand the flood gap in standard home insurance.
US citizens traveling abroad should check medical, evacuation, cancellation, baggage, and rental car coverage before buying a summer travel insurance policy.
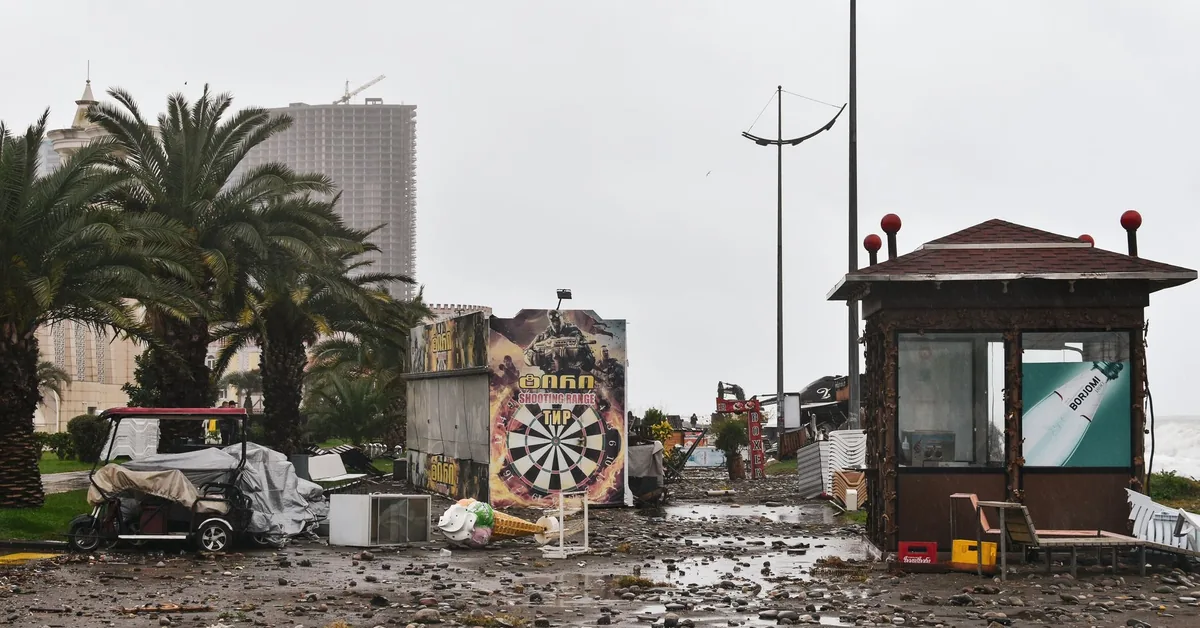
Cutting homeowners insurance before hurricane season can create expensive gaps. Review deductibles, dwelling limits, wind coverage, and flood insurance before reducing protection.
Standard homeowners and renters policies leave major gaps for home-based businesses and remote workers, from business property to professional liability.
Pet insurance premiums depend on your pet, ZIP code, deductible, reimbursement rate, and annual limit. Here is the math behind dog and cat premiums before you use the estimator.
Estimate a disability insurance benefit by starting with essential monthly expenses, subtracting reliable income, and adjusting for taxes. The goal is income continuity, not replacing every dollar you earn.

Get the official 2026 Medicare and ACA Marketplace open enrollment dates in the US to secure your health insurance on time.
Learn how credit-based insurance scores impact your auto and home insurance premiums at renewal and what you can do about it.
Hurricane season is the right time to review homeowners, flood, wind, and evacuation coverage before a storm is named. This guide explains what US households should check before June 1, 2027.
Hurricane season brings heightened flood risk to North Carolina. Learn why standard homeowners insurance won't cover flood damage and how to protect your property.
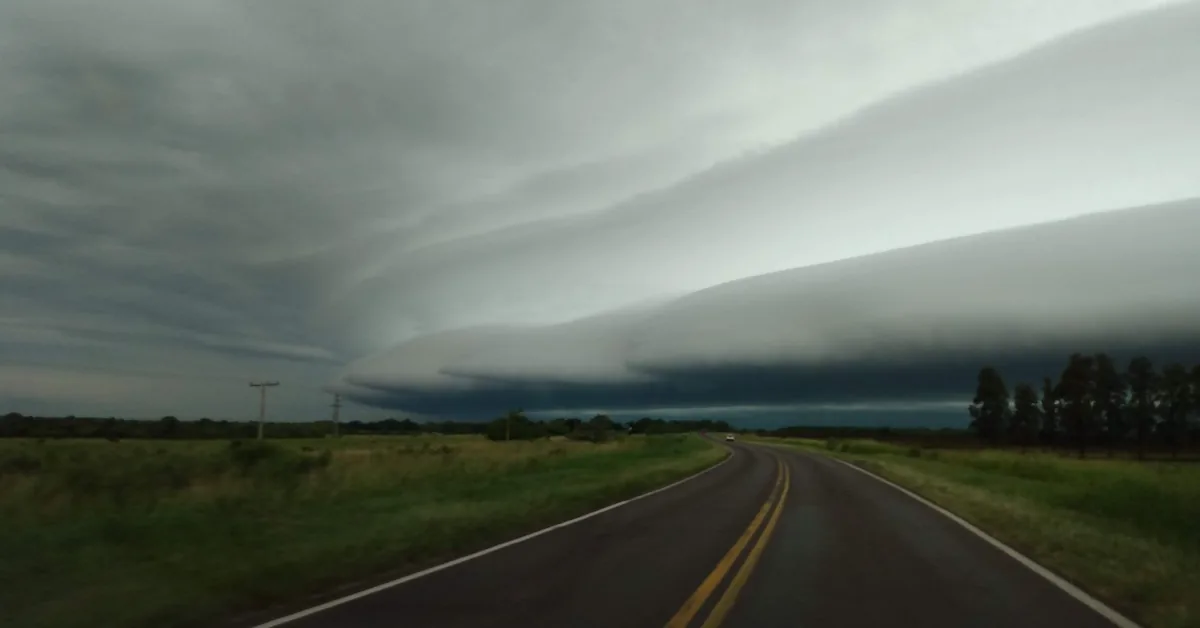
Texas officials are calling on homeowners to secure flood insurance ahead of the Atlantic hurricane season, which runs from June through November.

Texas enrolled over 4.2 million residents in ACA marketplace health plans during the latest open enrollment period, setting a new state record and reflecting growing demand for affordable coverage.
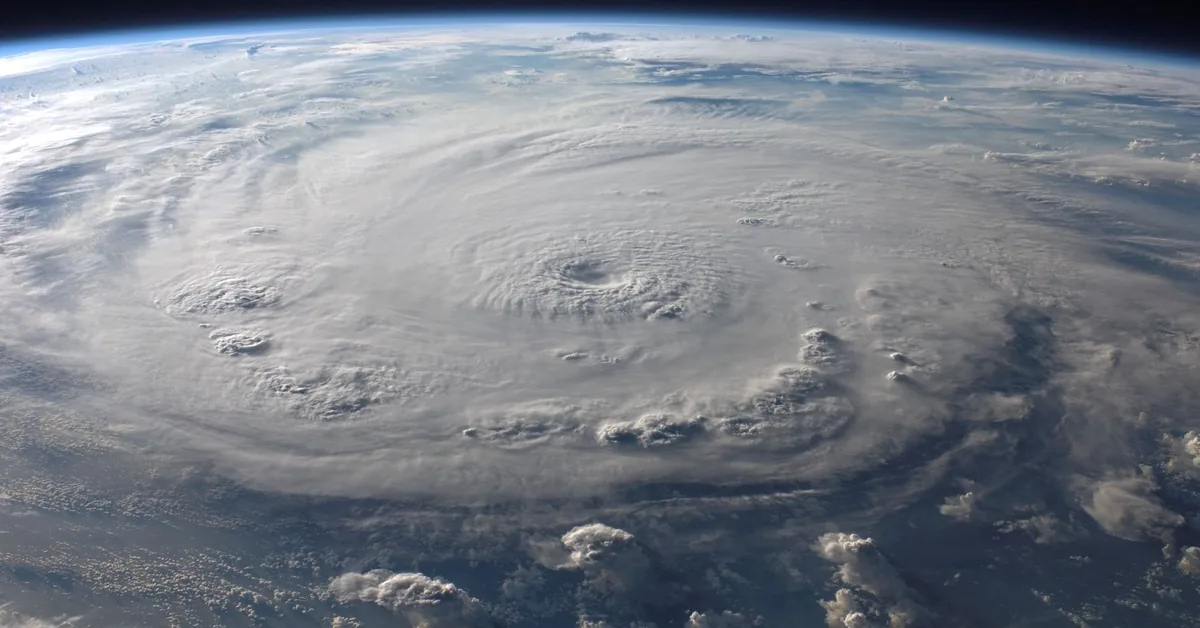
Below-average 2026 hurricane predictions are unlikely to immediately reduce Florida home insurance premiums due to market conditions, prior losses, and regulatory lag.
As hurricane season approaches, South Florida homeowners face critical decisions about flood insurance coverage and financial protection.
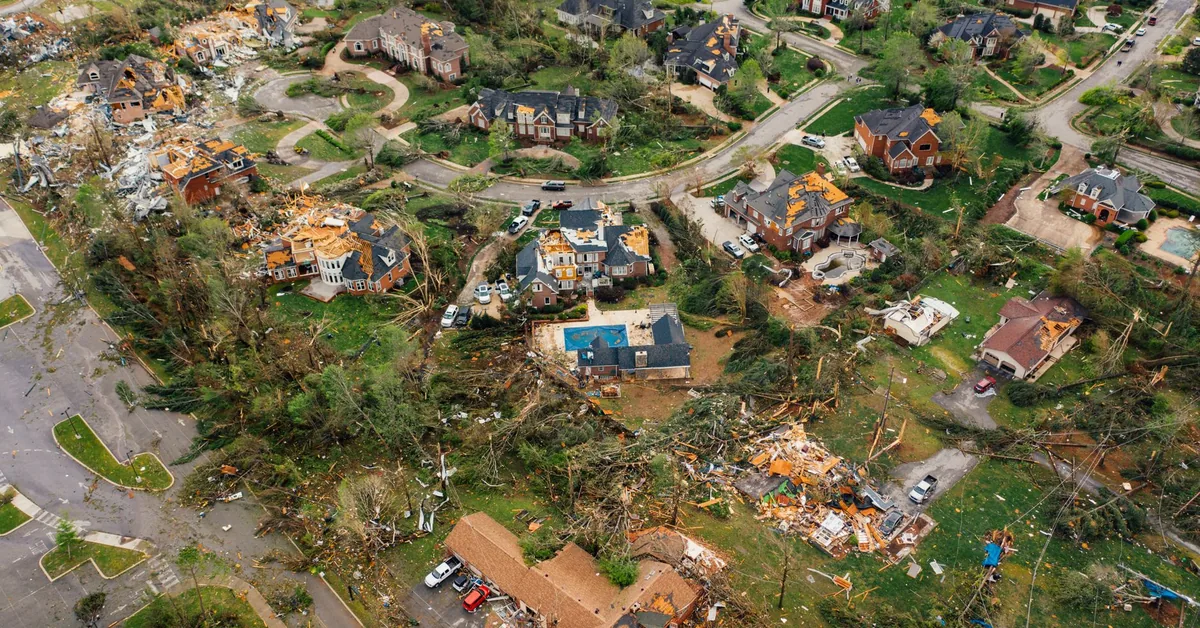
Rising hurricane insurance premiums and reduced coverage options are forcing thousands of Florida homeowners to drop or reduce their policies, leaving properties underinsured as climate risk intensifies.
Recent open enrollment data reveal Maryland families are struggling with premium increases, but state assistance programs offer substantial relief for eligible households.
Texas officials urge homeowners to purchase flood insurance ahead of hurricane season due to the 30-day waiting period that could leave properties unprotected.
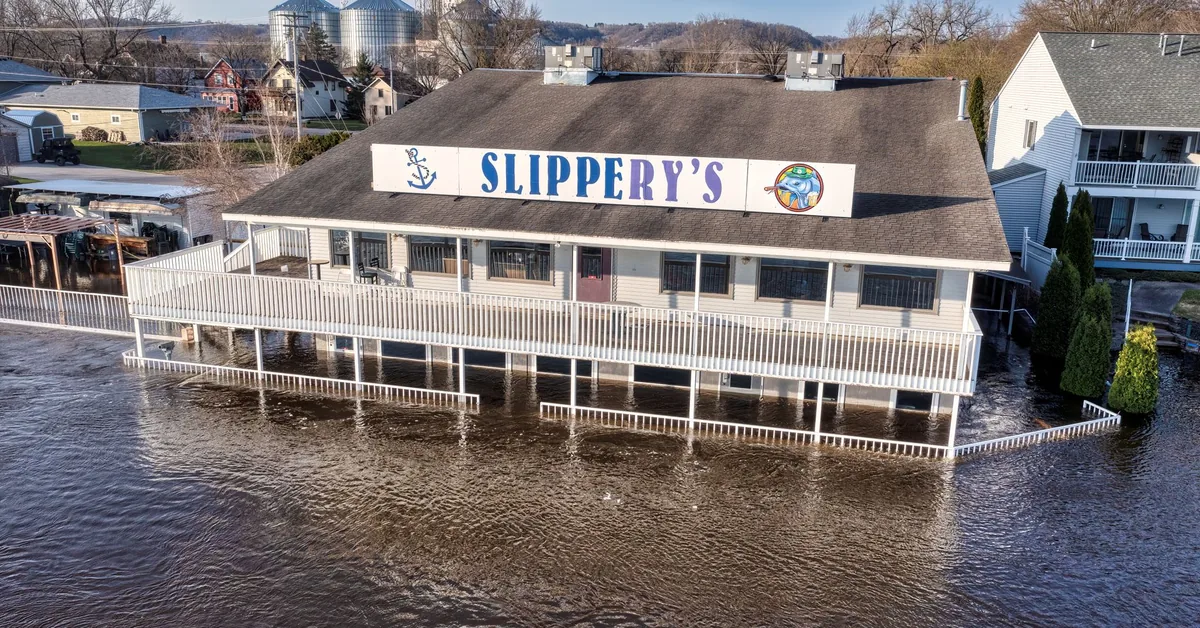
Most homeowners policies exclude flood damage. Whether you need separate flood insurance depends on your location, mortgage requirements, and personal risk tolerance.
Florida homeowners face potential shifts in federal flood insurance coverage and pricing as Congress considers NFIP reforms ahead of the 2026 Atlantic hurricane season.
Gap insurance covers the difference between what you owe on your car and its actual cash value if totaled. Learn when it's worth buying and when to skip it.
Renters insurance protects your belongings and liability as a tenant - learn what it covers and whether you need it.
Umbrella insurance provides extra liability protection beyond your auto and home policies when you are sued for damages.
Long Island's coastal location puts homeowners at significant flood risk, making separate flood insurance essential protection.
Houston homeowners face a critical 30-day waiting period for flood coverage. Learn how to secure protection before the next storm hits.
Learn how to properly insure expensive jewelry, art, and collectibles with specialized homeowners insurance riders that go beyond standard policy limits.
Flood insurance is federally mandated for mortgages on properties in high-risk flood zones, but not all homes need it.
State minimum car insurance requirements vary across the United States, but nearly all states mandate liability coverage to protect others if you cause an accident.
Learn how choosing the right deductible can lower your homeowners insurance premium while maintaining adequate financial protection for your property.
Your credit history plays a significant role in determining what you pay for auto and home insurance across most US states.
June marks the halfway point of the year and an ideal time to review your insurance coverage. Learn which six policies deserve a closer look and what to adjust.
Learn how to calculate, build, and maintain an emergency fund that works alongside your insurance coverage to protect your finances from unexpected expenses.
Learn the key steps to compare ACA marketplace plans with employer-sponsored coverage and make the right health insurance choice for your situation.
Learn how to evaluate health insurance plans by comparing costs, coverage, networks, and benefits to find the right option for your medical needs and budget.
Hurricane season starts June 1, 2027. Review your homeowners and flood insurance now to ensure you have adequate protection before the first storm hits.
With the US hurricane season ending, learn how to navigate insurance claims and prepare your home's policy for next year's storms.

A step-by-step guide to understanding and selecting the right auto insurance policy in the United States, from state minimums to optional coverages.
Learn what a car insurance deductible is, how it interacts with your premium, and how to pick the right amount for your budget and risk tolerance.
A clear comparison of term life and whole life insurance for US buyers, covering cost, coverage length, cash value, and who each policy fits best.
A plain-English guide to what a standard US homeowners policy covers, the gaps it leaves, and the extra coverage you may need for floods and earthquakes.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
