What to Do After a Car Accident to File an Insurance Claim in the US
Step-by-step guide to filing an auto insurance claim after an accident, from documenting the scene to working with adjusters and getting your vehicle repaired.
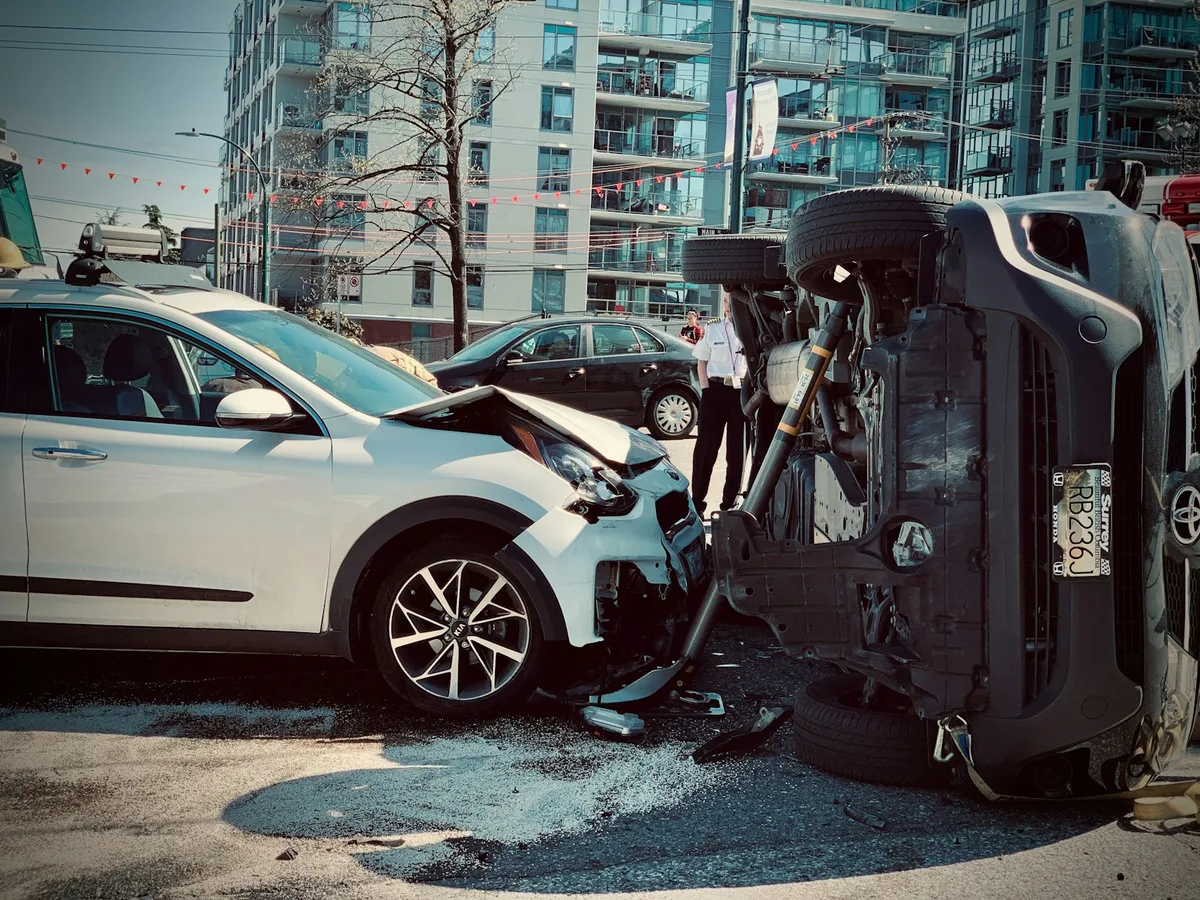
Pexels - Jorge Romero · original
In this article
Key Takeaway
After a car accident, immediately check for injuries and call 911 if needed. Document the scene with photos, exchange insurance information with other drivers, file a police report, and notify your insurance carrier within 24 hours. Your insurer will assign a claims adjuster, assess damage, and process payment for covered repairs minus your deductible.
Introduction
Filing a car insurance claim after an accident can feel overwhelming, especially when you are dealing with vehicle damage, potential injuries, and time pressure. Knowing the correct steps to take at the scene and in the days that follow protects your claim and helps you recover costs quickly. According to the Insurance Information Institute, over 5.3 million police-reported crashes occur annually in the United States, and understanding the claims process ensures you navigate your specific situation efficiently (III, 2024).
This guide walks you through each action required to file a successful auto insurance claim in the US, from the moment of the accident through final settlement.
Step 1: Ensure Safety and Call Authorities
Immediately after an accident, check yourself and all passengers for injuries. If anyone is hurt or if the accident involves significant property damage, call 911 right away. In most states, you are legally required to report accidents that result in injury, death, or property damage above a certain threshold (typically $500 to $2,500, depending on the state).
Move your vehicle to the side of the road if it is safe and drivable, and turn on hazard lights to prevent further collisions. Do not leave the scene until you have exchanged information and, if required, until police arrive. Leaving the scene of an accident can result in criminal charges and denial of your insurance claim.
Step 2: Document the Scene Thoroughly
Gather as much evidence as possible while you are still at the accident location. Use your smartphone to take clear photos of all vehicle damage from multiple angles, the position of the vehicles, skid marks, traffic signals, road conditions, and any visible injuries. Photograph license plates, street signs, and the surrounding area to establish context.
Exchange the following information with all other drivers: full name, phone number, insurance company name, policy number, driver’s license number, and vehicle make, model, and license plate. If there are witnesses, ask for their contact information and request a brief statement about what they saw. This documentation becomes critical if there is a dispute about fault later.
Step 3: File a Police Report
Even if the accident seems minor, file an official police report. Many insurance carriers require a police report number to process a claim, and the report serves as an independent, third-party account of the accident. In some states, you must report any accident that meets certain damage or injury thresholds to your state Department of Motor Vehicles (DMV) within a specific time frame (often 10 days).
Request a copy of the police report or note the report number and the name of the responding officer. You can typically obtain the full report from the local police department or online portal within a few days. The report will include officer observations, statements from involved parties, and often a preliminary determination of fault.
Step 4: Notify Your Insurance Company Immediately
Contact your insurance carrier within 24 hours of the accident, even if you believe the other driver was at fault. Most auto insurance policies require prompt notification, and delaying your report can result in a denied claim. Your insurer will open a claim file, assign a claim number, and provide instructions for the next steps.
When you call, provide the claim representative with all the information you gathered: police report number, photos, witness contact details, and a clear account of how the accident occurred. Be honest and factual. Do not admit fault or speculate about what happened, only describe what you observed. The National Association of Insurance Commissioners notes that timely reporting and accurate information are essential to a smooth claims process (NAIC, 2024).
Step 5: Work with the Claims Adjuster
Your insurance company will assign a claims adjuster to investigate the accident and assess the damage to your vehicle. The adjuster may inspect your car in person, request additional photos, or arrange for a repair estimate from an approved body shop. If the other driver was at fault and you are filing a claim through their liability insurance, their carrier will assign an adjuster to handle your claim.
The adjuster determines whether the damage is covered under your policy (collision, comprehensive, or liability) and calculates the payout based on repair costs or the actual cash value of your vehicle if it is totaled. You are responsible for paying your deductible before the insurer covers the remaining repair costs. Coverage limits, deductibles, and claim procedures vary by state, so confirm your specific policy terms with a licensed agent (OpenStax, 2022).
Step 6: Get Repairs and Close the Claim
Once the adjuster approves your claim, you can proceed with repairs. Some insurers have a network of preferred repair shops that guarantee their work and streamline the payment process, while others allow you to choose any licensed repair facility. Obtain at least two estimates to ensure fair pricing.
Read also: Summer Driving Risks in the US: An Auto Insurance Checklist
After repairs are complete, submit the final invoice to your insurer. The carrier will issue payment directly to the repair shop or reimburse you, minus your deductible. If you have rental car coverage, your policy may reimburse rental expenses while your vehicle is in the shop. Keep all receipts and documentation until the claim is fully closed.
Practical Tips
- Keep a copy of your insurance card, policy number, and emergency contact information in your vehicle at all times.
- Use a smartphone app or a printed checklist to guide you through the accident documentation process.
- If you are unsure whether to file a claim for minor damage, compare the repair cost to your deductible. Filing a claim for damage below your deductible may not be worthwhile and could affect your future premiums.
- Review your coverage limits annually and adjust your policy to reflect the current value of your vehicle and your financial situation.
Common Mistakes to Avoid
- Failing to document the scene or exchange information with other drivers can weaken your claim and make it harder to prove fault.
- Admitting fault or apologizing at the scene may be interpreted as an admission of liability, even if the other driver was primarily responsible.
- Delaying notification to your insurer or missing deadlines for filing a police report can result in claim denial.
- Accepting a settlement offer without reviewing the full scope of damage or consulting with your insurer or a licensed professional can leave you undercompensated.
Frequently Asked Questions
What if the other driver does not have insurance?
If the at-fault driver is uninsured, you can file a claim under your uninsured motorist (UM) coverage if you carry it. UM coverage is required in many states and pays for your injuries and, in some states, vehicle damage when the other driver lacks insurance. Confirm your policy details with your carrier.
How long does it take to settle a car insurance claim?
Simple claims with clear liability and minor damage can settle in a few days to two weeks. Complex claims involving injuries, disputes over fault, or totaled vehicles may take several weeks or months. Stay in regular contact with your adjuster for updates.
Will filing a claim raise my insurance premium?
Filing an at-fault claim typically increases your premium at renewal, especially if you have filed multiple claims in recent years. The exact increase depends on your insurer, state regulations, your driving history, and the severity of the accident. Not-at-fault claims may have a smaller impact or none at all, but policies vary.
Conclusion
Filing a car insurance claim after an accident requires prompt action, careful documentation, and clear communication with your insurer. By following these steps, you protect your financial interests, speed up the claims process, and ensure you receive the coverage you are entitled to under your policy. For personalized guidance on your specific situation, consult a licensed insurance agent or your state Department of Insurance.
Financial Disclaimer: This article provides educational information about auto insurance claims in the United States and is not personalized insurance, legal, or financial advice. Coverage requirements, claim procedures, and policy terms vary by state and carrier. Verify current rules and options with a licensed insurance agent or your state Department of Insurance before making coverage decisions.
Sources
- What Is Covered by a Basic Auto Insurance Policy (accessed )
- Auto Insurance Consumer Information (accessed )
- Principles of Finance (accessed )
Related articles
Summer Driving Risks in the US: An Auto Insurance Checklist
Use this US summer driving checklist to review liability, collision, comprehensive, rental car, and uninsured motorist coverage.
How to Choose the Right Auto Insurance Coverage for Your Needs in the US
Follow this checklist to choose auto insurance coverage that protects your finances and meets your state's requirements.
How to Compare Auto Insurance Quotes the Right Way in the US
Compare auto insurance quotes accurately by matching coverage limits, deductibles, and discounts. Avoid the trap of comparing price alone.
