Winter Home Damage in Canada: What Your Policy Covers and What It Does Not
Understanding which types of winter damage are covered by your home insurance policy and which you'll pay for out of pocket can save you thousands in unexpected repair costs.
Articles about home under Insurance.

Understanding which types of winter damage are covered by your home insurance policy and which you'll pay for out of pocket can save you thousands in unexpected repair costs.

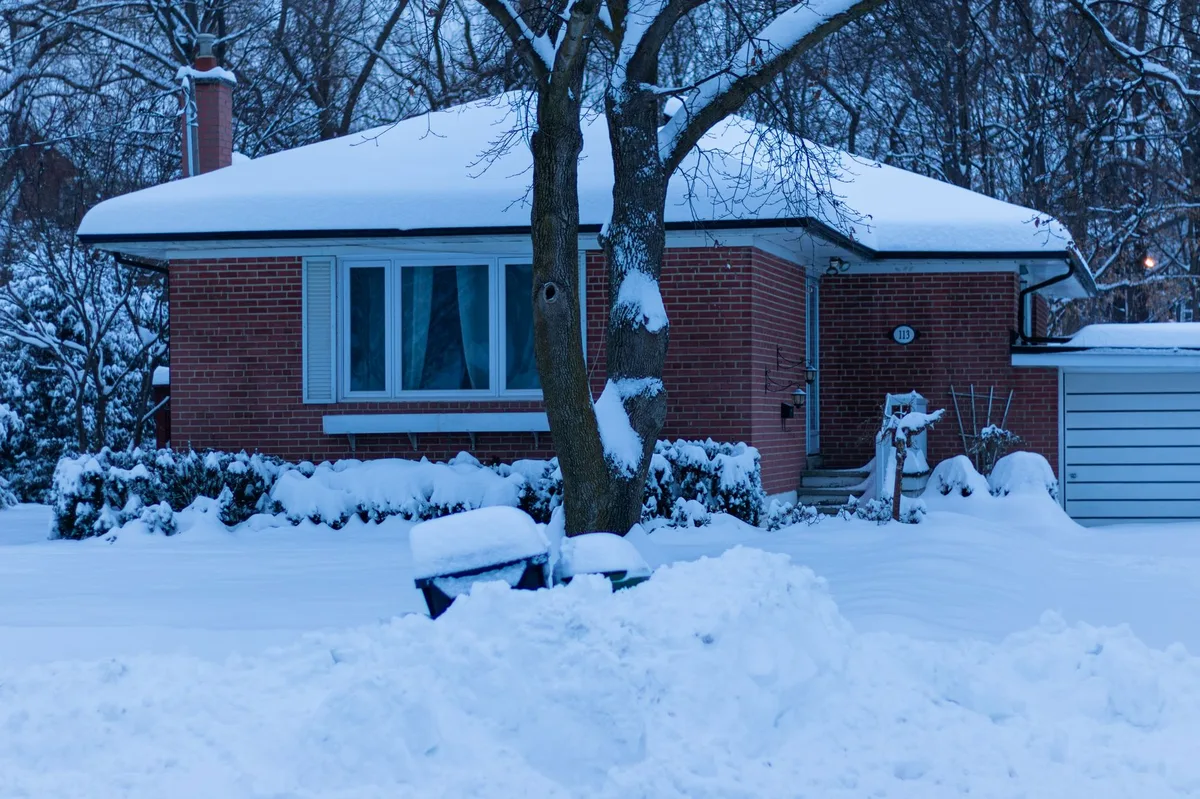
Extreme cold can damage your home in ways you might not expect. Understanding what your home insurance policy covers during harsh Canadian winters helps you protect your property and avoid costly surprises.

Compare the three core components of Canadian home insurance to understand what each protects and how they work together to cover your property and financial risk.

Canadian homeowners face a double squeeze in 2026 as mortgage renewals coincide with rising home insurance premiums, creating new affordability pressures across provinces.

Power outages can cause thousands in damage, from spoiled food to flooded basements. Learn what your Ontario home insurance policy covers and what it doesn't when the lights go out.

Statistics Canada reports home insurance premiums jumped 45% between 2017 and 2023, driven primarily by extreme weather events and rising climate-related claims.

Learn which types of nor'easter damage your Canadian home insurance policy covers, what exclusions apply, and when you need additional protection.

Inflation has driven home insurance premiums significantly higher across Canada through increased replacement costs, rising claims expenses, and more frequent severe weather events.

Home insurance costs vary dramatically across Canada, with some provinces facing premiums two to three times higher than others due to natural disaster risk, property values, and regional climate patterns.

Climate change is driving home insurance costs higher across Canada through increased claims from floods, wildfires, and severe weather, with premiums rising fastest in high-risk regions.

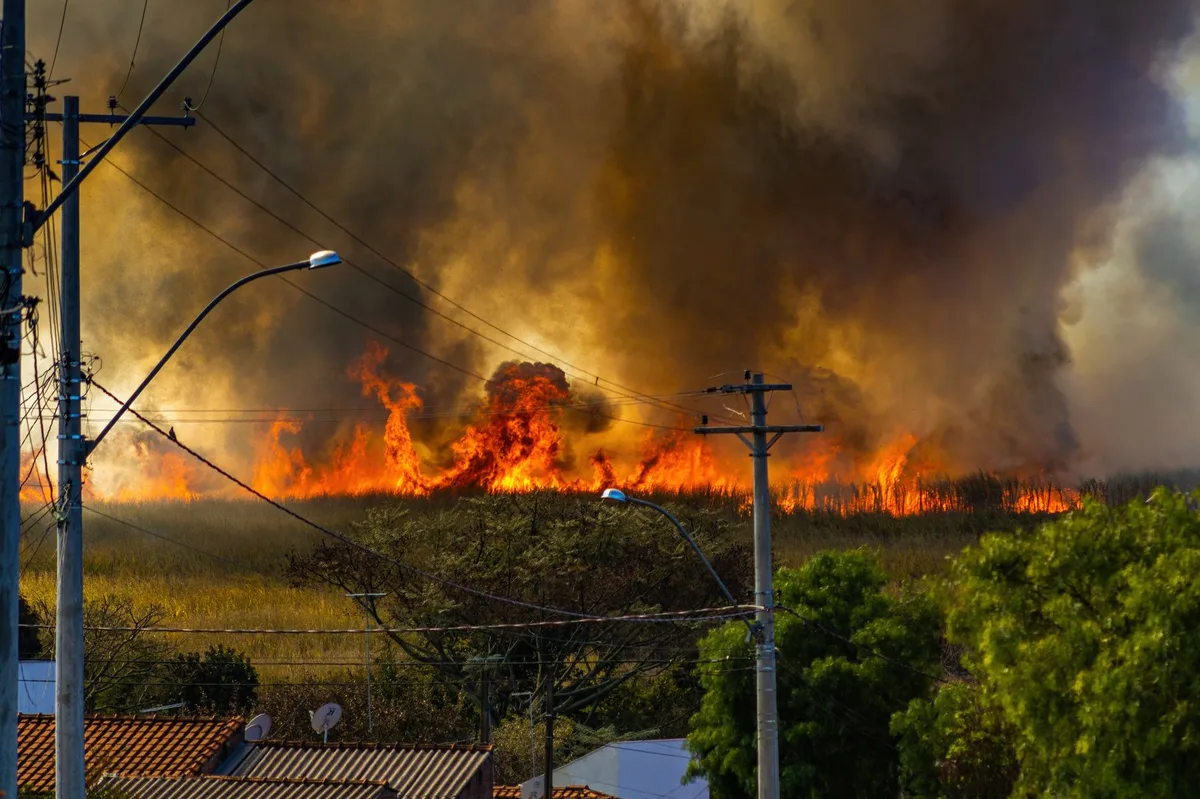
Wildfires are reshaping Canada's insurance landscape, driving premium increases, coverage restrictions, and fundamental changes in how insurers assess and price risk across fire-prone regions.

Learn how Canadian home insurance protects your dwelling, belongings, and liability exposure, with coverage details that vary by province.

Power outages can cause expensive damage to your home and belongings. Learn which types of power outage damage your Canadian home insurance covers and what typically requires additional protection.

Learn when and how to notify your home insurance provider about a fire, what information to gather, and why prompt reporting protects your claim.

Home insurance premiums across Canada have climbed sharply in recent years. Understanding what coverage you're actually paying for helps you assess whether you're getting fair value.

Ontario home insurance premiums rose 6.2% year-over-year in 2026, driven by climate risk, construction costs, and regional exposure patterns across the province.

Statistics Canada data reveals extreme weather events are pushing Canadian home insurance claims to unprecedented levels, reshaping coverage and costs across the country.

Home insurance premiums differ significantly across Canadian provinces due to weather risk, construction costs, and local regulations. Learn which regions pay more and how to find the best rates.

For most Canadian homeowners, home insurance premiums are not tax deductible. Learn when exceptions apply and how to claim eligible expenses.

Compare the major home insurance providers across Canada to find the right coverage for your property, from national carriers to regional specialists.
Wildfire coverage under Canadian home insurance policies, deductibles, and steps to protect your home and maximize your claim if disaster strikes.

Standard home insurance in Canada typically covers wildfire damage to your dwelling and belongings under comprehensive coverage, but exclusions and provincial differences apply.

A practical guide to winterizing your home insurance coverage by protecting pipes, inspecting your roof, and maintaining your heating system before cold weather arrives.

Understanding what your home insurance policy covers and excludes helps you identify gaps and choose the right protection for your property.

A systematic checklist of coverage, premium, and policy details to review before you sign your home insurance renewal this autumn.

Prepare your home for winter with this essential checklist to protect your property and maintain your home insurance coverage across Canadian provinces.

Learn the key steps to compare home insurance quotes accurately across Canadian insurers and find the best coverage for your needs.

Under-insuring your home triggers the coinsurance clause, which can slash your claim payout even for partial losses. Here's what every Canadian homeowner needs to know.

Learn how scheduling protects valuables beyond standard policy sub-limits and why professional appraisals matter for home insurance claims in Canada.

Learn how to determine the right amount of dwelling, liability, and loss-of-rental-income coverage for your rental property in Canada.

Learn exactly what standard home insurance covers in Canada, common exclusions, and how to identify gaps in your coverage.

Standard home insurance in Canada covers wildfire damage but typically excludes overland flooding - you need separate coverage for floods and other climate risks.

Canada's record insured disaster losses are putting pressure on home insurance renewals. Here is what homeowners should check before accepting a higher premium.

Wildfires are increasing property claim costs, changing underwriting, and putting pressure on home insurance availability in parts of Canada. Here is what that means for insurers and households.

While weather forecasts and disaster predictions inform long-term risk modeling, they do not directly reduce home insurance premiums in Canada; rates are primarily set using historical claims data and actuarial analysis.

Rising premiums driven by floods, wildfires, and severe weather are pushing some Canadian homeowners to reduce or drop insurance coverage, leaving them exposed to major financial losses.

Standard home insurance has limits on jewelry and valuables. Learn how to protect high-value items with riders and scheduled personal property endorsements.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.