Understanding the 40.6% Home Insurance Premium Rise in the UK
Home insurance premiums in the UK jumped by 40.6% year-on-year in January, marking one of the steepest increases in recent years. This sharp rise reflects growing claims costs, more frequent weather events, and inflation across the insurance sector.
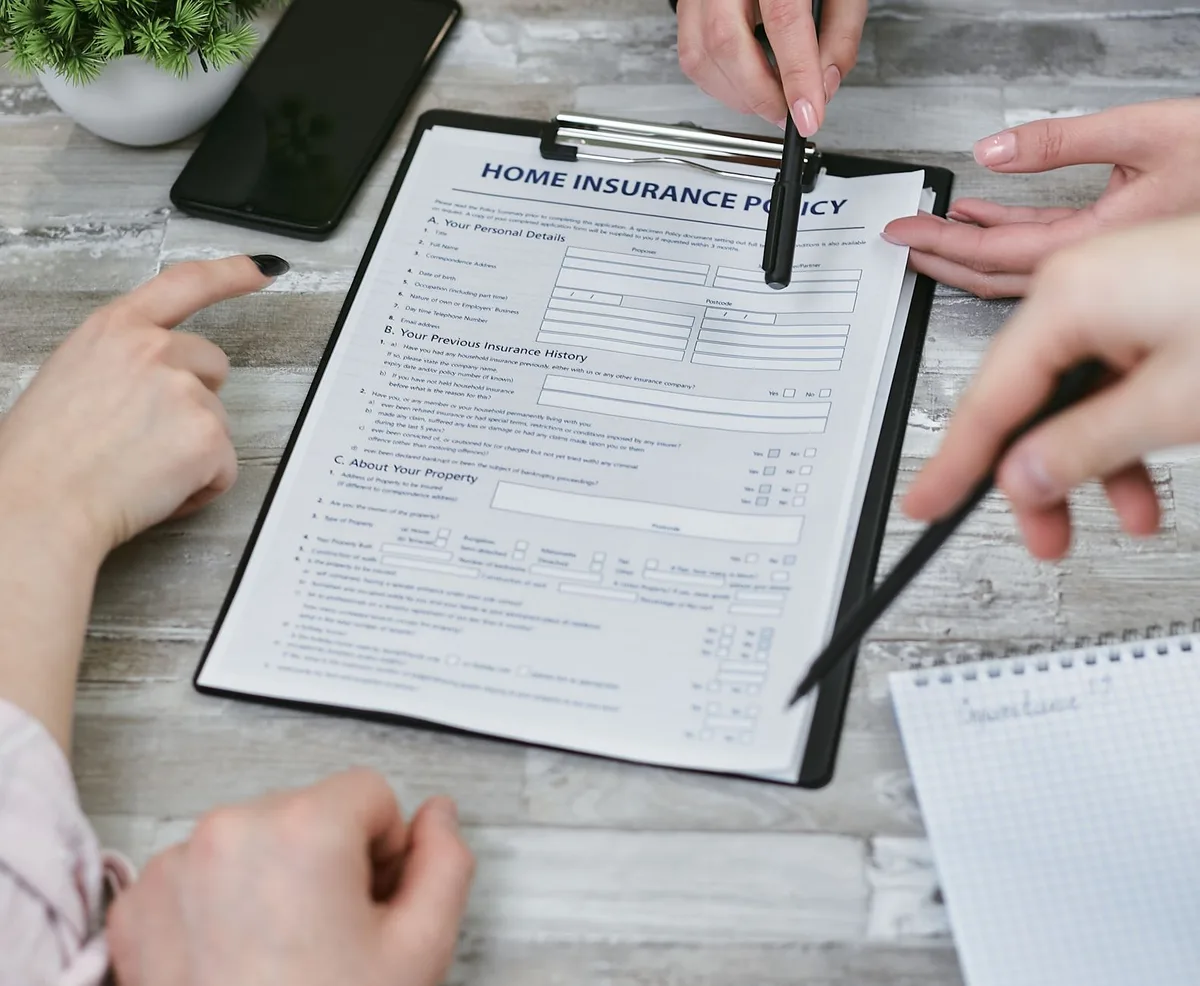
Pexels - Mikhail Nilov · original
In this article
Quoted home insurance premiums in the UK jumped by 40.6% year-on-year in January, one of the steepest increases recorded in recent years. This sharp rise affects both buildings and contents cover, driven by higher claims costs, more frequent severe weather events, and broader inflation across repair and replacement costs. For homeowners renewing policies or shopping around, this means significantly higher quotes than the previous year.
What’s Behind the Premium Increase
The 40.6% rise reflects multiple pressures on insurers. Repair and rebuild costs have climbed steeply due to inflation in building materials, labour shortages, and supply chain disruption. Severe weather events, including storms and flooding, have become more frequent and costly, pushing claims volumes higher. Insurers have also faced increased costs for reinsurance (the cover they buy to protect themselves against large losses), and these costs are passed on to policyholders through higher premiums.
According to the Association of British Insurers, the home insurance market has seen sustained upward pressure on premiums as insurers adjust pricing to reflect the true cost of claims (ABI, 2026). Inflation in construction costs alone has added significant expense to rebuilding claims, while the rising cost of household goods has driven up contents claims settlements.
What This Means for Homeowners
If your home insurance is due for renewal, expect a noticeably higher quote than last year. A policy that cost £300 in January 2025 could now be quoted at over £420, purely from the annual rise. The increase applies to both buildings insurance (covering the structure of your home) and contents insurance (covering your possessions), whether you buy them separately or as a combined policy.
The higher premiums are not uniform across all areas or property types. Homes in flood-risk zones or areas with higher crime rates may see steeper rises, as insurers adjust pricing based on local claims data. Newer properties with modern materials and security features may face smaller increases than older homes requiring specialist rebuilding methods.
How to Manage Rising Costs
Start by shopping around well before your renewal date. Loyalty does not pay in home insurance, and switching provider can often secure a better deal even in a rising market. Use comparison sites to gather multiple quotes, but also check directly with insurers, as not all appear on every comparison platform.
Read also: Home Insurance Premiums Fall 4.4% in the UK - What It Means for You
Review your cover carefully. Check that your buildings sum insured (the rebuild cost, not the market value) is accurate; over-insuring wastes money on higher premiums, while under-insuring can leave you seriously short if you need to claim. For contents cover, reassess the total value of your possessions and adjust your cover limit accordingly. Consider whether optional add-ons such as accidental damage cover or home emergency cover are worth the extra cost for your situation.
Increasing your voluntary excess (the amount you pay towards a claim) can reduce your premium, but only do this if you could afford the higher excess in the event of a claim. Improving home security, such as fitting approved locks and alarms, may also qualify you for a discount with some insurers.
What to Do Next
Compare quotes from at least three insurers or brokers before renewing. Read the policy wording and the key facts document to understand what is and is not covered, including any exclusions. If you are uncertain about the level of cover you need or the best policy for your circumstances, consider speaking to an FCA-authorised insurance adviser who can provide tailored guidance (FCA, 2026). MoneyHelper also offers free, impartial guidance on choosing and managing home insurance (MoneyHelper, 2026).
Disclaimer: This article provides general information only and is not regulated financial advice. We are not authorised by the Financial Conduct Authority. Home insurance cover, premiums, and exclusions vary by insurer and by individual policy. Always read the policy wording and key facts document, and consider speaking to an FCA-authorised insurance adviser for guidance tailored to your personal circumstances. Verify current terms and pricing directly with insurers before making a decision.
Sources
- Products and Issues - Home Insurance (accessed )
- Insurance - MoneyHelper (accessed )
- Consumer Guidance (accessed )
Related articles
Home Insurance Premiums Fall 4.4% in the UK - What It Means for You
UK home insurance premiums fell 4.4% in September 2026. Discover what Defaqto's data means for your buildings and contents cover.
Why Home Insurance Premiums Have Risen 25% in the UK
UK home insurance premiums have risen 25% in three years. Learn why costs have soared and what homeowners can do to manage rising cover expenses.
How to Get a Cheap Home Insurance Deal in the UK
UK home insurance premiums hit seven-year highs. Discover 7 proven ways to cut costs on buildings and contents cover without losing protection.
