Cyclone Season Insurance Checklist for Australian Homeowners
The Australian cyclone season begins November 1. Use this checklist to review your home, contents, and flood cover before the first storm arrives.
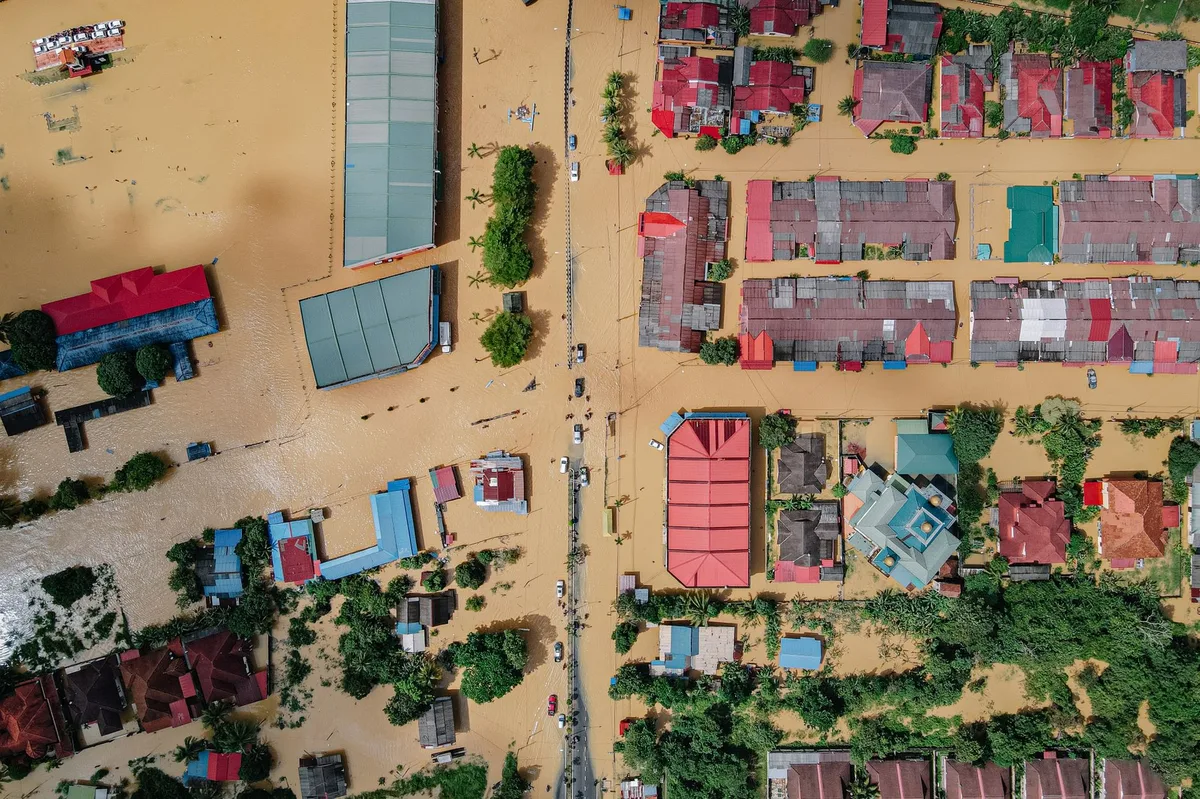
Pexels - Pok Rie · original
In this article
The Australian cyclone season begins today, November 1, and runs through April 30. Most home insurance policies cover cyclone and storm damage, but flood cover is typically separate and not automatic. Contents insurance is also separate from building cover. Use this checklist now to confirm you have the right protection before the first severe weather arrives.
Why Review Your Cover Now
Cyclone season brings heavy rain, storm surge, and destructive winds to coastal and northern Australia. Damage from these events can run into tens of thousands of dollars for a single property. According to the Insurance Council of Australia, many homeowners discover gaps in their cover only after they lodge a claim.
Waiting until a cyclone warning is issued is too late. Most insurers will not allow you to add or change cover once a cyclone has been named or a severe weather warning is active for your region. That window closes fast, so review your policies today.
Your Cyclone Season Insurance Checklist
1. Confirm You Have Home (Building) Insurance
If you own your home, building insurance covers the structure itself: the walls, roof, fixed fittings, and permanently attached items such as built-in wardrobes. Standard home insurance policies in Australia typically include cyclone and storm damage as part of the base cover, but check your Product Disclosure Statement (PDS) to confirm.
Verify that your sum insured is enough to rebuild your home at current construction costs. Building costs have risen sharply in recent years, and underinsurance is common. The Insurance Council recommends reviewing your sum insured annually.
2. Check Your Contents Insurance Separately
Contents insurance is a separate policy (or can be added to a combined home and contents policy). It covers your belongings: furniture, clothing, electronics, appliances, and personal items. Storm and cyclone damage to contents is usually covered, but only if you hold a contents policy. Many homeowners assume their building insurance covers everything and discover too late that it does not.
If you rent, you need contents insurance. Your landlord’s building insurance does not cover your belongings.
3. Verify Flood Cover Is Included
Flood cover is the most critical gap. Many home and contents policies exclude flood damage unless you have specifically added flood cover. Cyclones bring heavy rainfall and storm surge, both of which can cause flooding. According to ASIC MoneySmart, flood is defined as the covering of normally dry land by water that has overflowed from a river, creek, lake, or dam, or by rainwater runoff.
Check your PDS under the definitions section. If flood is listed as an exclusion, contact your insurer today to add it. Flood cover usually increases your premium by 5 to 15 per cent, but the cost of flood damage to a home can exceed A$100,000.
Some policies distinguish between flood (water from external sources) and rainwater runoff or stormwater inundation. Read the definitions carefully and ask your insurer to clarify if you are uncertain.
4. Review Your Excess Amount
Your excess is the amount you pay out of pocket when you lodge a claim. Standard excesses for home and contents claims typically range from A$500 to A$2,500, but many policies impose a separate, higher cyclone excess in cyclone-prone regions (northern Queensland, the Northern Territory, and parts of Western Australia).
A cyclone excess can be A$5,000, A$10,000, or even a percentage of the sum insured (such as 1 or 2 per cent). Check your policy schedule now so you know what you would need to pay in the event of a claim. If the excess is unaffordable, consider whether you can reduce it by increasing your premium, or set aside emergency savings to cover it.
5. Understand What Is Excluded
Even comprehensive policies have exclusions. Common exclusions for cyclone and storm claims include:
- Damage caused by lack of maintenance (such as a roof that was already deteriorating before the storm).
- Damage to fences, gates, and retaining walls (some policies exclude these or limit cover to a set amount, such as A$1,000).
- Damage to swimming pools, spas, and landscaping.
- Damage that occurs while the property is unoccupied for more than a set number of consecutive days (often 60 or 90 days).
Read also: Cyclone Season 2027: Your Essential Insurance Coverage Review Guide
Read the exclusions section of your PDS and ask your insurer if you are unsure whether specific items or scenarios are covered.
6. Document Your Belongings Now
If you need to lodge a contents claim, you will need to prove what you owned and its value. Take photos or video of each room in your home, including inside cupboards and wardrobes. Keep receipts for high-value items (electronics, jewellery, appliances, furniture) and store them digitally in a cloud service or email them to yourself so they are accessible even if your home is damaged.
An up-to-date inventory makes the claims process faster and reduces disputes with your insurer.
7. Check Your Policy Is Current and Paid
Confirm your policy has not lapsed. If you have missed a premium payment or your direct debit has failed, your cover may have been cancelled. Log in to your insurer’s online portal or call them to verify your policy is active.
If you have moved house or made structural changes (such as a renovation or extension), notify your insurer. Failing to disclose material changes can void your cover.
8. Prepare Your Property Before a Storm
While not strictly an insurance task, securing your property reduces the likelihood of damage and supports any future claim. Clear gutters and downpipes, trim overhanging branches, secure outdoor furniture, and check that your roof is in good condition. Insurers can deny claims if damage results from poor maintenance.
Common Mistakes to Avoid
The biggest mistake is assuming you have flood cover when you do not. The second is underinsuring your building. The third is waiting until a cyclone is named before checking your policy. By then, insurers will not allow changes.
Do not rely on memory or assumptions. Read your PDS and policy schedule now, and if anything is unclear, call your insurer and ask direct questions. As foundational texts such as Principles of Finance explain, insurance transfers financial risk, but only if the contract covers the specific event that occurs.
Take Action Today
Cyclone season has begun. Set aside 30 minutes today to locate your home and contents insurance documents, read the flood and cyclone sections of your PDS, and confirm your cover is adequate. If you identify a gap, contact your insurer immediately to add the missing cover or increase your sum insured.
If you do not have flood cover and you live in a cyclone-prone or flood-prone region, adding it now could save you from catastrophic financial loss in the months ahead. Check your policy, update your inventory, and secure your property. The first storm of the season can arrive within weeks.
General Advice Warning: This article provides general information only and does not take into account your objectives, financial situation, or needs. Before acting on this information, consider whether it is appropriate for you and read the relevant Product Disclosure Statement (PDS). Consider obtaining personal advice from a licensed insurance adviser. Coverage, exclusions, excesses, and availability vary by insurer and by state or territory. Verify current terms in the PDS and with a licensed adviser before deciding. Premium costs and policy terms are indicative as of November 2026 and may change.
Sources
- Insurance for your home (accessed )
- Consumer resources and information (accessed )
- Australia.gov.au (accessed )
- Principles of Finance (accessed )
Related articles
Cyclone Season 2027: Your Essential Insurance Coverage Review Guide
Complete guide to reviewing home and contents insurance before Australian cyclone season. Check flood cover, sum insured, excess levels, and exclusions.
Preparing for Cyclone Season in Australia: Your Home Insurance Checklist
Cyclone season starts November 1 in Australia. Use this checklist to review your home and contents insurance, verify storm cover, and protect your property.
Home and Contents Insurance in Australia: What's Covered and What's Not
Compare what home and contents insurance covers in Australia. Learn about standard coverage, common exclusions, and how to choose the right policy.
