Wildfire and Home Insurance Cover in the UK: What You Need to Know
With wildfires becoming more common in the UK, find out whether your buildings and contents insurance will cover fire damage to your home and what exclusions might apply.
Pexels - Serhii Bondarchuk · original
In this article
Key Takeaway
Most UK buildings insurance policies cover fire damage, including damage caused by wildfires. Buildings insurance typically pays to repair or rebuild your home’s structure, while contents insurance covers your possessions inside. However, you must check your policy wording for specific exclusions, cover limits, and excess amounts, and verify current terms with an FCA-authorised insurance adviser before relying on any policy in the event of a wildfire.
What Standard Home Insurance Covers for Wildfire Damage
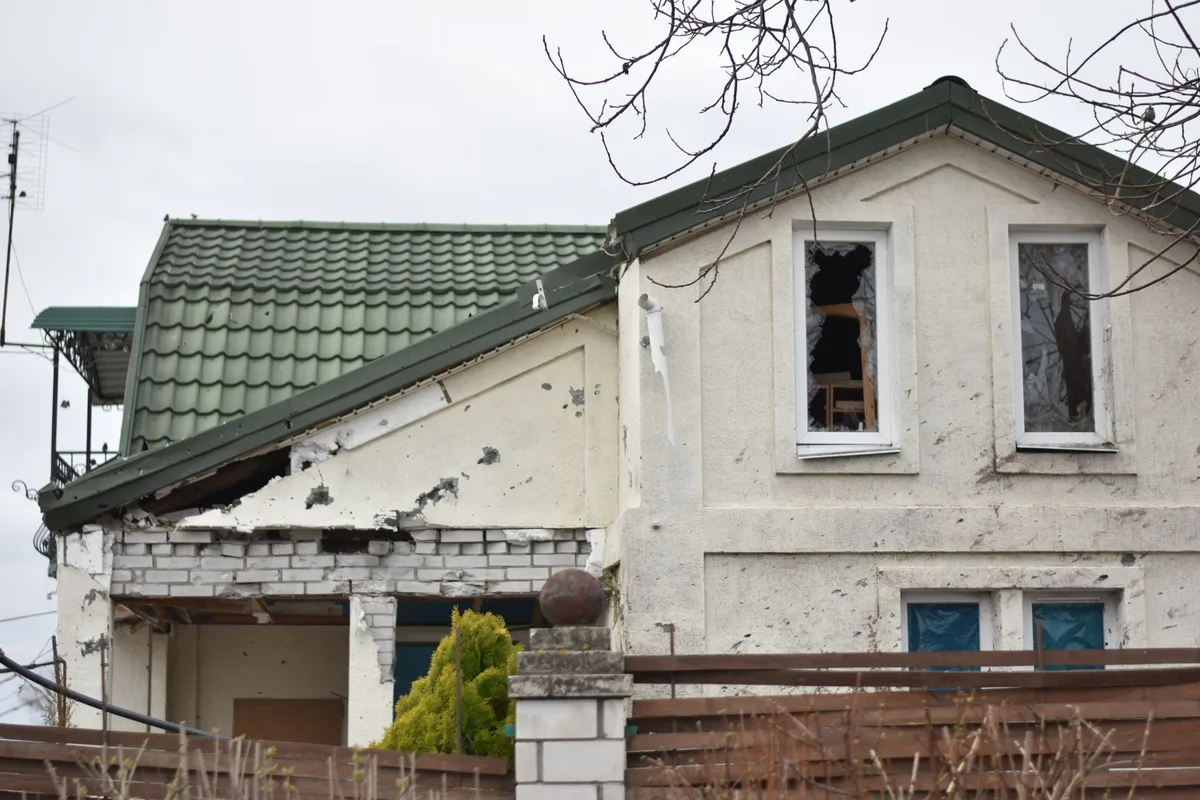
Fire damage is one of the core perils included in the vast majority of UK buildings insurance policies. According to the Association of British Insurers, fire cover is a standard element of buildings insurance, whether the fire originates inside your home (such as an electrical fault or cooking accident) or outside (such as a spreading wildfire) (ABI, 2026).
Buildings insurance covers the permanent structure of your home: walls, roof, floors, fitted kitchens and bathrooms, and fixtures such as central heating systems. If a wildfire destroys or damages these elements, your buildings policy should pay to repair or rebuild them up to your sum insured (the maximum amount the insurer will pay). You remain responsible for paying the excess (the first portion of any claim).
Contents insurance, sold separately or as part of a combined buildings and contents policy, covers your personal possessions: furniture, clothing, electronics, and other movable items. If a wildfire destroys the contents of your home, your contents policy should pay to replace them, subject to the policy’s cover limit and any single-item limits for high-value possessions.
Alternative Accommodation and Additional Costs
Many buildings insurance policies include alternative accommodation cover. If your home becomes uninhabitable due to wildfire damage, the insurer typically pays the reasonable cost of temporary accommodation (a rental property or hotel) while repairs are carried out. This element is sometimes listed as “loss of use” or “temporary rehousing” in the policy wording. The cover usually lasts until your home is habitable again or until you reach the policy’s time or monetary limit, whichever comes first.
Some policies also cover additional costs such as emergency repairs to prevent further damage (boarding up broken windows, securing the roof), removal of debris, and professional fees (surveyors, architects) needed to settle the claim and complete repairs.
Outbuildings, Gardens, and Boundaries
Buildings insurance typically extends to permanent outbuildings on your property: garages, sheds, greenhouses, and garden walls. If a wildfire damages these structures, they should be covered under the buildings element, though some insurers impose sub-limits (a lower maximum payout) for outbuildings, so check your policy schedule.
Garden plants, lawns, trees, and shrubs are generally excluded from buildings insurance, or covered only up to a small limit (often £500 or £1,000 in total). If a wildfire destroys your garden, you will likely need to replant at your own cost. Fences and gates are usually covered as part of buildings insurance, subject to the policy terms.
Common Exclusions and Conditions to Check
While fire damage is a standard peril, certain exclusions or conditions might apply in wildfire scenarios. Some policies exclude or limit cover for damage caused by:
- Wilful acts or neglect: if you failed to take reasonable steps to protect your property (for example, ignoring an evacuation order or leaving flammable materials near the house during a wildfire warning), the insurer might reduce or refuse the claim.
- Failure to maintain the property: if your home was already in disrepair and the wildfire damage was worsened by pre-existing problems, the insurer may dispute the extent of the claim.
- Excess: you must pay the policy excess (typically £100 to £500 or more) before the insurer settles the remainder of the claim. Voluntary excess (an amount you chose to reduce your premium) and compulsory excess (set by the insurer) apply together.
Read also: Under-Insurance and the Average Clause: Why Your UK Claim Could Be Cut in Half
Some policies also cap the total sum insured or impose specific limits on high-value items (jewellery, art, electronics). If your possessions exceed these limits, you may need to arrange additional cover or schedule individual items separately.
The Claims Process and Documentation
If a wildfire damages your home, contact your insurer as soon as it is safe to do so. The insurer will open a claim, assign a loss adjuster if the damage is extensive, and arrange an inspection of the property. Keep all evidence: photographs of the damage, receipts for emergency repairs, and lists of damaged or destroyed items (with purchase receipts or proof of value where possible).
The insurer will assess the claim against your policy terms and issue a settlement. For buildings damage, the insurer may pay you directly to arrange repairs, or instruct approved contractors to carry out the work. For contents, the insurer typically offers a cash settlement or arranges replacement items through its approved suppliers. Settlement is on an “indemnity” basis (current value, taking account of wear and tear) unless you have “new for old” or “replacement as new” cover, which pays the cost of a new equivalent item without deduction for age.
As covered in Introduction to Business (OpenStax, 2018), insurance is a risk-pooling mechanism: policyholders pay premiums into a collective fund, and those who suffer covered losses draw from that fund. The policy wording and the claims process are the formal expressions of this agreement.
UK Context: Wildfires and Climate Patterns
Wildfires are relatively rare in the UK compared to countries such as Australia or the western United States, but they have become more frequent in recent summers, particularly during heatwaves and prolonged dry periods. Moorland fires, grassland fires, and forest fires have damaged homes and infrastructure in affected areas. MoneyHelper advises homeowners to review their insurance cover regularly and confirm that their sum insured reflects the current rebuild cost of their home, not the market value (MoneyHelper, 2026).
If you live in an area at higher risk of wildfire (near moorland, forests, or grassland), speak to an FCA-authorised insurance adviser or broker to confirm that your policy provides adequate cover and to understand any exclusions or conditions that might apply. The Financial Conduct Authority regulates insurance firms and intermediaries in the UK and sets conduct standards to protect consumers (FCA, 2026).
Conclusion
UK home insurance typically covers wildfire damage to your building and contents, with buildings insurance paying to repair or rebuild the structure and contents insurance replacing your possessions. Most policies also include alternative accommodation cover while your home is uninhabitable. However, cover limits, excesses, and exclusions vary by insurer and policy, so read your policy wording carefully and verify current terms with an FCA-authorised adviser before relying on any coverage. If you have not reviewed your home insurance recently, check that your sum insured is adequate and that you understand what is and is not covered in the event of a wildfire.
Financial Disclaimer: This article provides general information only and does not constitute regulated financial advice. We are not authorised by the Financial Conduct Authority. Insurance cover, exclusions, and terms vary by insurer and by individual policy. Always read your policy wording, key facts document, and policy schedule, and consider speaking to an FCA-authorised insurance adviser or broker for advice tailored to your personal circumstances before making any insurance decision.
Sources
- Products and Issues - Choosing the Right Insurance (accessed )
- Insurance - MoneyHelper (accessed )
- FCA Consumer Guidance (accessed )
- Introduction to Business (accessed )
Related articles
Under-Insurance and the Average Clause: Why Your UK Claim Could Be Cut in Half
Under-insurance triggers the average clause in UK home policies, cutting your claim payout proportionally. Learn how it works and how to avoid it.
Most Common Home Insurance Claims in the UK
The most common UK home insurance claims include escape of water, theft, storm damage, and accidental damage. Learn what to watch for and how to prevent costly claims.
Home Insurance in the UK: Buildings, Contents and Liability Cover Explained
Buildings, contents and liability cover form UK home insurance. Learn what each protects, how they work together, and which you need.
