Does Your Home Insurance Cover Weather Damage in the UK?
Understanding which types of weather damage are covered by UK home insurance policies and what exclusions typically apply.
Pexels - Helena Jankovičová Kováčová · original
In this article
Key Takeaway
Most UK buildings and contents insurance policies cover damage from storms, high winds, and heavy rain, but flood damage often requires specific cover that may carry higher premiums in flood-risk areas. Standard policies typically exclude damage from poor maintenance, gradual deterioration, and certain weather conditions that fall below the insurer’s definition of a storm. Always read your policy wording and key facts document to confirm exactly which weather perils are covered and what excess applies.
Understanding Weather Damage and UK Home Insurance
Weather damage is one of the most common causes of home insurance claims in the United Kingdom, from winter storms tearing roof tiles to summer flooding damaging carpets and furniture. Whether your policy covers the damage depends on the type of peril, the policy you hold, and how the damage occurred.
UK home insurance is generally split into buildings insurance (covering the structure) and contents insurance (covering possessions). Many homeowners hold a combined policy that covers both. The extent of weather damage cover varies between insurers and policy tiers, so understanding what is and is not included is essential.
What Counts as Weather Damage?
Weather damage refers to physical harm to your property caused by natural weather events. Common examples include:
- Storm damage: high winds lifting roof tiles, breaking windows, or felling trees onto the property
- Rain and water ingress: rainwater entering through storm-damaged roofs or windows
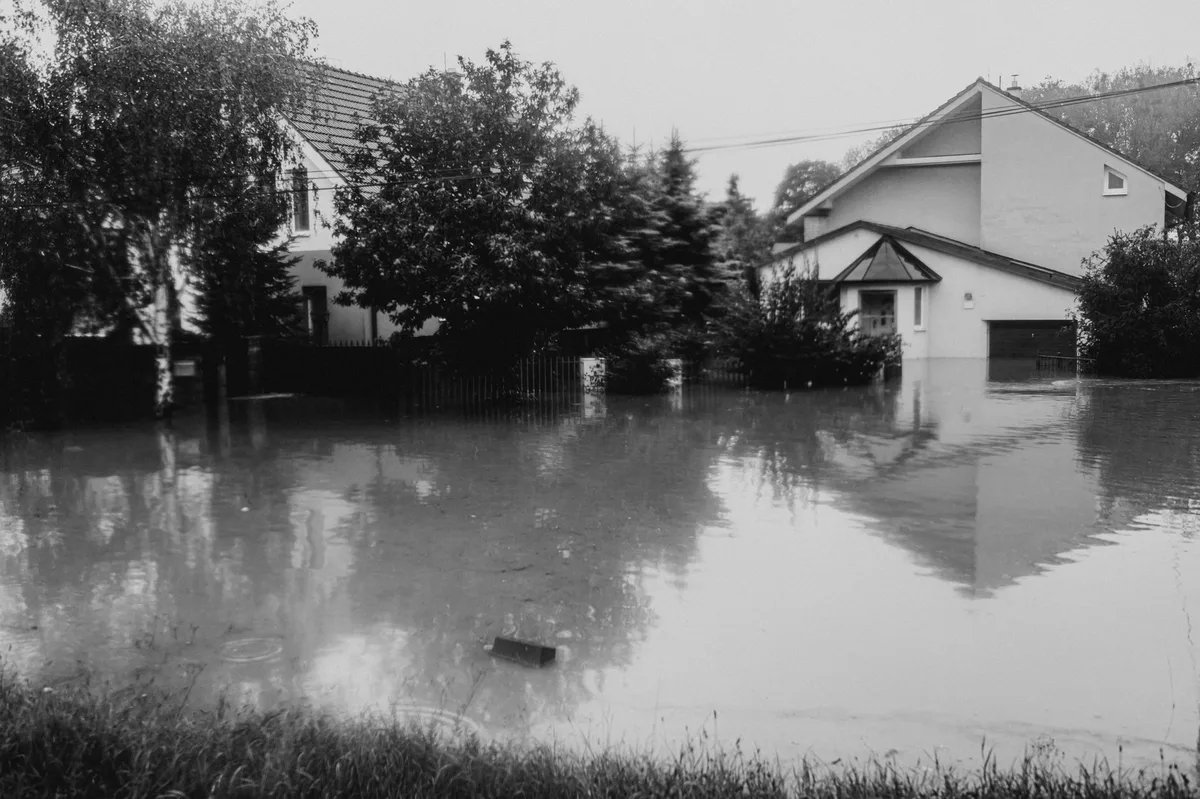
- Flooding: surface water, river flooding, or coastal flooding entering the property
- Snow and ice: roof collapse from snow weight, burst pipes from freezing, or ice damage to gutters
- Hail: broken windows, damaged roof tiles, or dented external fixtures
- Lightning: fire or electrical damage from a direct strike
According to the Association of British Insurers, the definition of a storm typically requires wind speeds exceeding a certain threshold (often around 55 mph) or exceptional rainfall (ABI, 2026). Light rain or gusty conditions that do not meet this threshold may not be covered as storm damage.
Buildings Insurance and Weather Cover
Buildings insurance covers the physical structure of your home: walls, roof, windows, permanent fixtures, and outbuildings. Most standard buildings policies include cover for:
- Storm and wind damage to the structure
- Damage caused by falling trees or branches during a storm
- Water damage resulting from storm-related ingress (such as rainwater through a damaged roof)
- Lightning strikes that cause fire or structural damage
- Weight of snow causing roof or outbuilding damage
Flood cover is often included in buildings insurance but may be subject to higher excess (the amount you pay towards a claim) if your property is in a flood-risk area. In high-risk postcodes, insurers may use the Flood Re scheme, a government-backed reinsurance programme that makes flood cover more affordable and available for eligible properties (Flood Re, 2026).
Contents Insurance and Weather Damage
Contents insurance covers your possessions: furniture, electronics, clothing, and personal items. Weather-related contents cover typically includes:
- Damage to belongings caused by rainwater entering through storm damage
- Flood damage to carpets, furniture, and appliances
- Damage from a storm-related roof leak
- Items damaged by a fallen tree
Contents policies do not usually cover items damaged by gradual damp, condensation, or leaks from poor maintenance. The damage must result from a sudden, insured weather event.
Common Exclusions and Limitations
Even comprehensive policies exclude certain types of weather-related damage. Typical exclusions include:
- Gradual damage: wear and tear, rot, corrosion, or slow leaks not caused by an insured event
- Poor maintenance: damage resulting from failure to maintain the property (such as a roof in disrepair that leaks during normal rain)
- Frost damage to outbuildings: some policies exclude frost damage to unoccupied or unheated structures
- Coastal erosion and subsidence: often excluded or subject to additional terms
- Damage below the storm threshold: wind or rain that does not meet the insurer’s definition of a storm
Insurers assess claims based on the policy wording and the specific circumstances. If damage results from a combination of storm and pre-existing poor maintenance, the claim may be reduced or declined.
Flood Cover and Flood Re
Flooding is a significant risk in parts of the UK, and flood damage can be costly. Most buildings and contents policies include flood cover, but properties in high-risk areas (identified by postcode and flood maps) may face higher premiums or excess amounts.
Flood Re is a joint government and insurance industry scheme that limits the flood-risk element of premiums for eligible homes built before 2009. If your property qualifies, your insurer can pass the flood risk to Flood Re, making cover more affordable. Not all properties are eligible, and Flood Re does not cover businesses or homes built after 1 January 2009 (Flood Re, 2026).
According to MoneyHelper, if you live in a flood-risk area, it is essential to compare policies and confirm the flood excess before purchasing cover, as this can vary from £100 to over £1,000 depending on the risk level (MoneyHelper, 2026).
Making a Claim for Weather Damage
If your property suffers weather damage, take the following steps:
- Make the property safe: prevent further damage by covering broken windows or holes in the roof with temporary repairs (keep receipts, as reasonable costs are often reimbursed).
- Document the damage: photograph the damage and the weather conditions if possible, and keep any damaged items until the claim is assessed.
- Contact your insurer promptly: notify your insurer as soon as possible, as most policies require claims to be reported within a set period.
- Obtain quotes: your insurer may ask for repair quotes or send a loss adjuster to assess the damage.
- Pay the excess: you will need to pay the policy excess (the agreed amount you contribute towards the claim) before the insurer settles the remainder.
Citizens Advice recommends keeping a record of all correspondence with your insurer and escalating to the Financial Ombudsman Service if the claim is unfairly declined or delayed (Citizens Advice, 2026).
Conclusion
UK home insurance policies generally cover a wide range of weather damage, including storms, wind, rain ingress, and flooding, but the extent of cover depends on your specific policy, the cause of the damage, and whether the property has been properly maintained. Flood cover is widely available but may carry higher costs in high-risk areas, and schemes such as Flood Re can help make cover more affordable for eligible properties. Always read your policy wording, confirm your excess, and verify that your cover matches the weather risks relevant to your location. For personalised advice on your circumstances, consider speaking to an FCA-authorised insurance adviser.
Disclaimer: This article provides general information only and is not regulated financial advice. We are not authorised by the Financial Conduct Authority (FCA). Insurance cover, exclusions, and availability vary by insurer and by policy. Before purchasing or relying on any insurance product, read the policy wording and key facts document carefully and consider speaking to an FCA-authorised insurance adviser for guidance tailored to your personal situation.
Sources
- Insurance Products and Issues (accessed )
- Flood Re (accessed )
- Insurance Guidance (accessed )
- Consumer Insurance Help (accessed )
Related articles
Does Home Insurance Cover Weather Damage in the UK? Understanding Storm, Flood and Wind Claims
UK home insurance covers storm and wind damage but typically excludes flood. Learn what weather perils are included, how Flood Re works, and when to buy extra cover.
Storm Season Preparation: Your Home Insurance Coverage Review Checklist
Essential checklist to review your UK home insurance before storm season. Check buildings, contents, flood cover and exclusions.
How Birmingham's Weather Affects Home Insurance Premiums in the UK
Learn how Birmingham's rainfall, flooding and weather patterns influence home insurance premiums and cover in the UK, plus what homeowners can do.
