How the Cyclone Reinsurance Pool Affects Home Insurance Premiums in Australia
The Australian Government's Cyclone Reinsurance Pool aims to reduce insurance costs in cyclone-prone regions. Learn how this scheme works and whether it lowers premiums in high-risk areas.
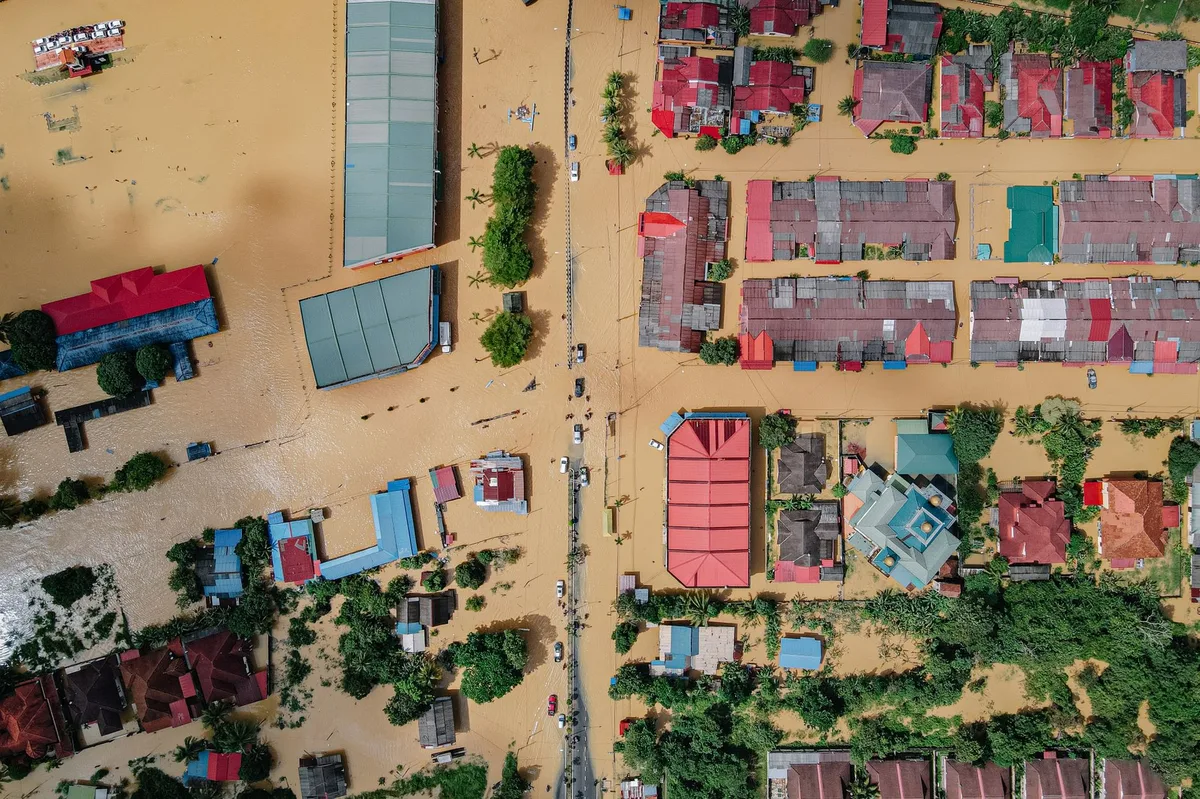
Pexels - Pok Rie · original
In this article
The Australian Government’s Cyclone Reinsurance Pool, established in 2022, reduces reinsurance costs for home and strata insurers in cyclone-prone regions across northern Australia. By capping the price insurers pay to transfer cyclone risk, the scheme aims to lower premiums for households and strata buildings in high-risk areas where cover has become unaffordable or unavailable. Early results show premium reductions for many policyholders, though the impact varies by insurer, location, and property characteristics.
What Is the Cyclone Reinsurance Pool
The Cyclone Reinsurance Pool is a government-backed reinsurance scheme administered by the Australian Reinsurance Pool Corporation (ARPC). Reinsurance is the insurance that insurers buy to protect themselves against large losses. When a cyclone causes widespread damage, insurers must pay many claims at once. To manage this risk, they purchase reinsurance from global markets, and in cyclone-prone areas, reinsurance costs have historically been very high.
The pool functions as a collective risk-sharing mechanism. As explained in foundational insurance texts such as Principles of Finance, pooling spreads risk across a larger base, reducing the cost for individual participants (Principles of Finance, OpenStax). Under the pool, participating insurers pay the ARPC a set reinsurance premium for cyclone-related claims, rather than negotiating individually with reinsurers in the private market. The government guarantees the pool and can draw on up to A$10 billion in support if claims exceed the pool’s reserves.
According to the Australian Reinsurance Pool Corporation, the scheme covers eligible residential, strata, and small business property insurance in declared cyclone-risk postcodes across northern Australia (ARPC, 2026).
How the Pool Affects Premiums in High-Risk Regions
The pool’s core aim is to reduce the reinsurance component of insurance premiums. For properties in high-risk cyclone areas, reinsurance often accounted for a significant portion of the total premium before the pool’s introduction. By capping reinsurance costs at rates below the private market, the pool creates a potential saving that insurers can pass on to policyholders.
However, the size of the premium reduction depends on several factors. Insurers must choose to participate in the pool, and they determine how much of the reinsurance saving flows through to customers. Some insurers passed on substantial reductions immediately, while others adjusted premiums more gradually. The Insurance Council of Australia notes that premium impacts vary by insurer and by the specific risk profile of the property (Insurance Council of Australia, 2026).
Properties at highest risk (those closest to the coast, older construction, or lacking cyclone-resistant features) may see smaller reductions because their total premium reflects not just reinsurance costs but also the insurer’s own risk assessment, claims history, and operating costs. Conversely, newer homes built to modern cyclone standards may benefit more significantly.
The pool does not cap the premium you pay. It caps the reinsurance cost the insurer pays, which is only one component of your final premium. Excess, sum insured, claim history, and building characteristics still influence the total cost.
Which Regions Are Covered
The pool applies to residential properties in postcodes declared as cyclone-risk areas by the Australian Government. These regions span northern Western Australia, the Northern Territory, Queensland, and northern New South Wales. Specific postcodes are listed in the scheme’s eligibility guidelines, and the ARPC maintains the authoritative list.
Regions that typically qualify include coastal areas from Exmouth in Western Australia through Darwin and across to Cairns, Townsville, the Whitsundays, and parts of southeast Queensland. Some inland areas with cyclone exposure are also included. The pool covers home (building) insurance, contents insurance, combined home and contents, and strata insurance (body corporate) for eligible properties.
Read also: How the Cyclone Reinsurance Pool Cuts Premiums in Australia
If your property is outside a declared cyclone postcode, you are not covered by the pool, and your insurer will continue to purchase reinsurance on the private market.
Limitations and What the Pool Does Not Cover
The Cyclone Reinsurance Pool covers cyclone-related perils only. These typically include wind damage, storm surge, and rain or flooding directly associated with a cyclone event. It does not cover standalone flood (from riverine flooding unrelated to a cyclone), earthquake, bushfire, or other perils. Your standard home or contents policy covers these separately, and their premiums are not affected by the pool.
The pool applies to residential and strata property only. Commercial properties, large apartment complexes beyond the strata threshold, and other non-residential risks are excluded.
Premium reductions are not guaranteed. While the pool lowers reinsurance costs for insurers, each insurer decides its own pricing. Some policyholders report significant savings, while others see modest reductions or no change if other risk factors (such as a recent claim or ageing construction) offset the reinsurance benefit.
Always compare quotes from multiple insurers. The pool’s impact varies, and shopping around remains the best way to secure competitive cover. ASIC’s MoneySmart service provides guidance on comparing home insurance policies and understanding what drives premiums (MoneySmart, 2026).
What to Do Next
If you live in a cyclone-prone region, check whether your postcode is covered by the pool. Contact your current insurer and ask how the pool affects your premium, or request quotes from insurers who participate in the scheme. Compare the premium, excess, sum insured, and exclusions across multiple policies.
Review your Product Disclosure Statement (PDS) to understand what cyclone damage is covered and any specific conditions or excess that apply to cyclone claims. If you are buying or building in a high-risk area, consider construction features that reduce cyclone risk (such as rated windows, secure roofing, and elevated floor levels), as these may lower your premium further.
Speak with a licensed insurance adviser if you have difficulty obtaining cover or if your premium remains unaffordable despite the pool’s introduction. An adviser can help you assess your options and may identify insurers or products suited to high-risk properties.
Disclaimer
This article provides general information only and does not take into account your personal objectives, financial situation, or needs. Before making any decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD). For advice specific to your circumstances, consult a licensed insurance adviser or financial adviser. Coverage, premiums, and the impact of the Cyclone Reinsurance Pool vary by insurer, property, and location. Always confirm current terms and eligibility with your insurer or a licensed adviser before purchasing or renewing a policy.
Sources
- Principles of Finance (accessed )
- Cyclone Reinsurance Pool (accessed )
- Consumer Resources (accessed )
- Insurance (accessed )
Related articles
How the Cyclone Reinsurance Pool Cuts Premiums in Australia
The ACCC confirms Australia's cyclone reinsurance pool has reduced home insurance premiums in high-risk northern areas. Learn how it works.
Understanding the Cyclone Reinsurance Pool and Premium Relief in Australia
The Australian Cyclone Reinsurance Pool has reduced premiums in cyclone-prone areas, but affordability pressures persist for many northern households.
Why Northern WA Has the Highest Home Insurance Premiums in Australia
Northern WA home insurance premiums are the highest in Australia due to cyclone risk, flood exposure, and remote building costs. Understand the drivers and your options.
