How Australia's Cyclone Reinsurance Pool Keeps Home Insurance Affordable
The Australian Reinsurance Pool Corporation's cyclone pool helps homeowners in storm-prone areas maintain affordable home insurance by spreading catastrophic cyclone risk across the market.
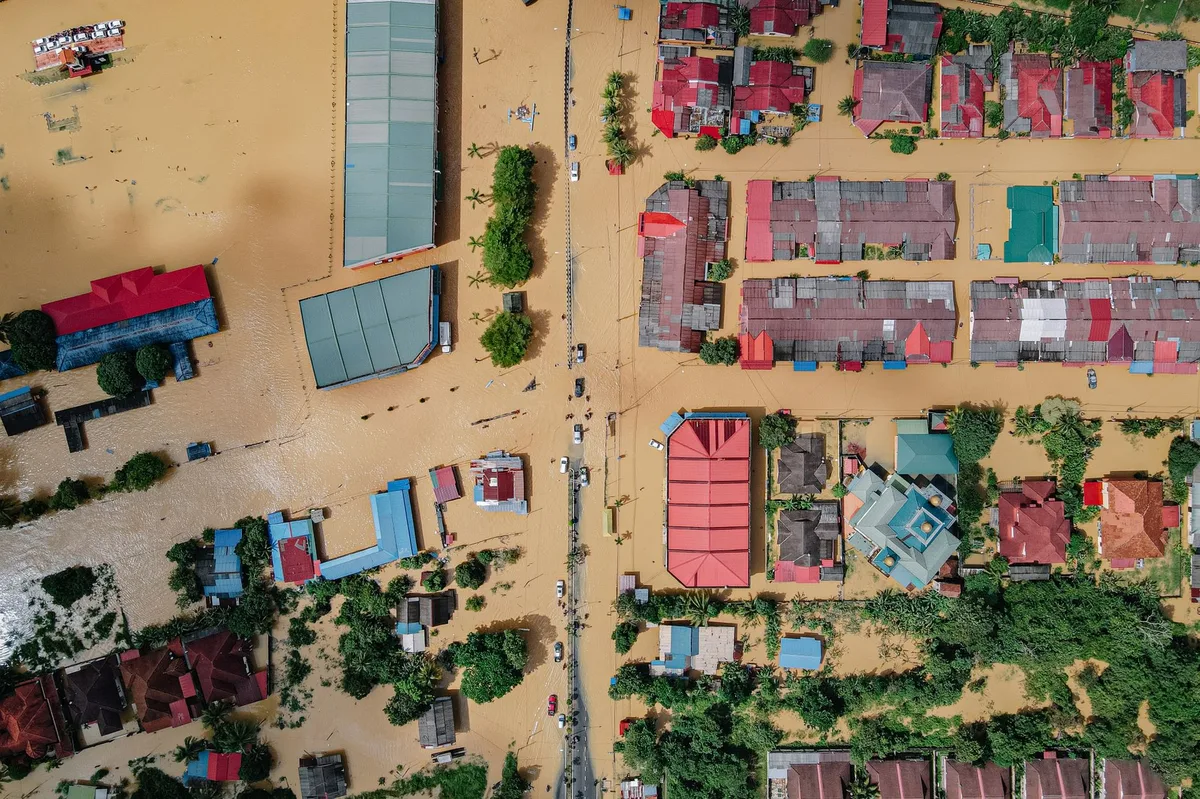
Pexels - Pok Rie · original
In this article
Australia’s cyclone reinsurance pool, operated by the Australian Reinsurance Pool Corporation (ARPC), reduces home insurance premiums in cyclone-prone regions by sharing catastrophic storm risk across insurers through government-backed reinsurance. The scheme has cut premiums by an average of 23% (and up to 46% in high-risk areas) since launching in July 2022, making home and contents cover affordable for homeowners and landlords in northern Australia and other storm-exposed zones.
What the Cyclone Pool Is
The Australian Reinsurance Pool Corporation cyclone pool is a government-backed reinsurance scheme that helps insurers manage the cost of catastrophic cyclone damage. When insurers write home, contents or strata insurance policies in cyclone-prone areas, they can transfer a portion of their cyclone risk to the pool. If a major cyclone causes widespread claims, the pool pays out to insurers, which keeps individual insurers’ losses manageable and prevents them from withdrawing from high-risk markets or charging unaffordable premiums (ARPC, 2026).
The pool operates on reinsurance principles covered in foundational finance texts such as Principles of Finance: insurers pay premiums into the pool, and the pool assumes the catastrophic tail risk (the chance of extreme, industry-threatening losses from a single event). The Australian Government guarantees the pool, backing it with up to A$10 billion in the event of a disaster that exceeds the pool’s own reserves.
Why It Was Created
Before the cyclone pool launched, homeowners in cyclone-prone regions (particularly northern Queensland, the Northern Territory and parts of Western Australia) faced a home insurance affordability crisis. Insurers priced cyclone risk individually, and in high-risk postcodes, annual home insurance premiums sometimes exceeded A$10,000 or A$15,000. Some properties became effectively uninsurable at any price. The crisis forced many households to go without cover or to underinsure, leaving them financially exposed to cyclone damage (Insurance Council of Australia, 2026).
The cyclone pool spreads the risk across the entire Australian insurance market rather than concentrating it in the regions where cyclones occur. This pooling mechanism lowers premiums in cyclone zones and stabilises the market.
Who Benefits and How Much Premiums Fall
The cyclone pool applies to residential home insurance, contents insurance, combined home and contents policies, and strata insurance for units and apartments. Landlord insurance for investment properties in cyclone zones also benefits. According to the Australian Reinsurance Pool Corporation, around 880,000 policies across the eligible regions have accessed premium relief since the scheme began (ARPC, 2026).
Premium reductions vary by postcode and insurer. The Australian Government reported average premium savings of 23% in the first year, with some high-risk areas seeing reductions of up to 46%. Insurers pass the savings through to policyholders when they renew or take out new cover. The reduction appears as a line item or a lower total premium on your renewal notice.
What Cover the Pool Includes
The cyclone pool covers damage from cyclones and cyclone-related perils: wind, storm surge, heavy rainfall and flooding that occurs as part of a cyclone event. It does NOT cover flood damage from non-cyclone weather systems, earthquakes, or tsunami. If your area experiences a flood unrelated to a cyclone, the pool does not apply, and your standard flood cover (if you have it) responds instead.
The pool reinsures the buildings portion of home insurance, the contents portion, or both, depending on your policy type. Check your Product Disclosure Statement (PDS) to confirm which perils your policy covers and whether the cyclone pool applies to your premium.
Read also: Preparing for Cyclone Season in Australia: Your Home Insurance Checklist
What You Should Do
If you live in a cyclone-prone area and your current home insurance premium feels unaffordable, compare quotes from multiple insurers. Insurers participate in the pool voluntarily, and not all pass savings through at the same rate or at the same time. Shop around at renewal to ensure you benefit from the scheme (ASIC MoneySmart, 2026).
Read your PDS carefully. The cyclone pool does not change your policy’s excess, exclusions, or sum insured. You still need to choose appropriate cover limits for your building and contents, maintain your property to your insurer’s standards, and disclose all material facts when applying.
If you are unsure whether your postcode qualifies for the cyclone pool or whether your policy type is eligible, contact your insurer or a licensed insurance adviser. Eligibility depends on your location and the type of cover; strata policies and landlord policies benefit, but some commercial and industrial covers do not.
Limitations and What the Pool Does Not Solve
The cyclone pool reduces premiums, but it does not eliminate cyclone risk or guarantee that cover will be available at any price. If your property sits in an extreme-risk location or has a claims history, insurers may still decline cover or apply high excesses. The pool also does not cover damage from non-cyclone floods, so if your area floods regularly from summer storms unrelated to cyclones, you need separate flood cover.
Cover, exclusions, and pricing vary by insurer and by individual property risk. Always read the PDS and the Target Market Determination (TMD), and verify current premium quotes and terms before deciding.
General advice warning: This article provides general information only. It does not take into account your objectives, financial situation or needs. Before acting on this information, consider whether it is appropriate for you. Read the relevant Product Disclosure Statement (PDS) and consider seeking personal advice from a licensed insurance adviser about your circumstances. Cover, premiums and eligibility for the cyclone pool vary by insurer, postcode and property. Premium figures and savings are indicative as of October 2026; verify current terms in the PDS or with your insurer before deciding.
Sources
- Australian Reinsurance Pool Corporation (accessed )
- Insurance Consumer Resources (accessed )
- Insurance Guide (accessed )
- Principles of Finance (accessed )
Related articles
Understanding the Cyclone Reinsurance Pool and Premium Relief in Australia
The Australian Cyclone Reinsurance Pool has reduced premiums in cyclone-prone areas, but affordability pressures persist for many northern households.
Understanding Rising Home Insurance Premiums in Australia
Why Australian home insurance premiums are rising sharply in 2026. Understand the climate, reinsurance, and regional factors driving higher costs.
How the Cyclone Reinsurance Pool Cuts Premiums in Australia
The ACCC confirms Australia's cyclone reinsurance pool has reduced home insurance premiums in high-risk northern areas. Learn how it works.
