Insurance
Autumn Car Insurance Review in Canada: Preparing for Winter Driving
Review your auto insurance this fall to ensure you have the right coverage for winter road conditions and avoid coverage gaps.
Author
Quebec-based bilingual insurance writer specialising in auto and property coverage, guiding readers through the provincial differences in deductibles, mandatory minimums, and no-fault rules.
Review your auto insurance this fall to ensure you have the right coverage for winter road conditions and avoid coverage gaps.
Critical illness insurance pays a lump sum if you are diagnosed with a covered serious illness. Learn which conditions qualify and whether this coverage fits your financial protection plan.
Term and permanent life insurance serve different needs. Learn how to evaluate coverage duration, premium costs, and cash value features to pick the right policy for your situation.
Major life changes often mean your insurance needs have shifted. Learn which life events should trigger a coverage review and what to update.
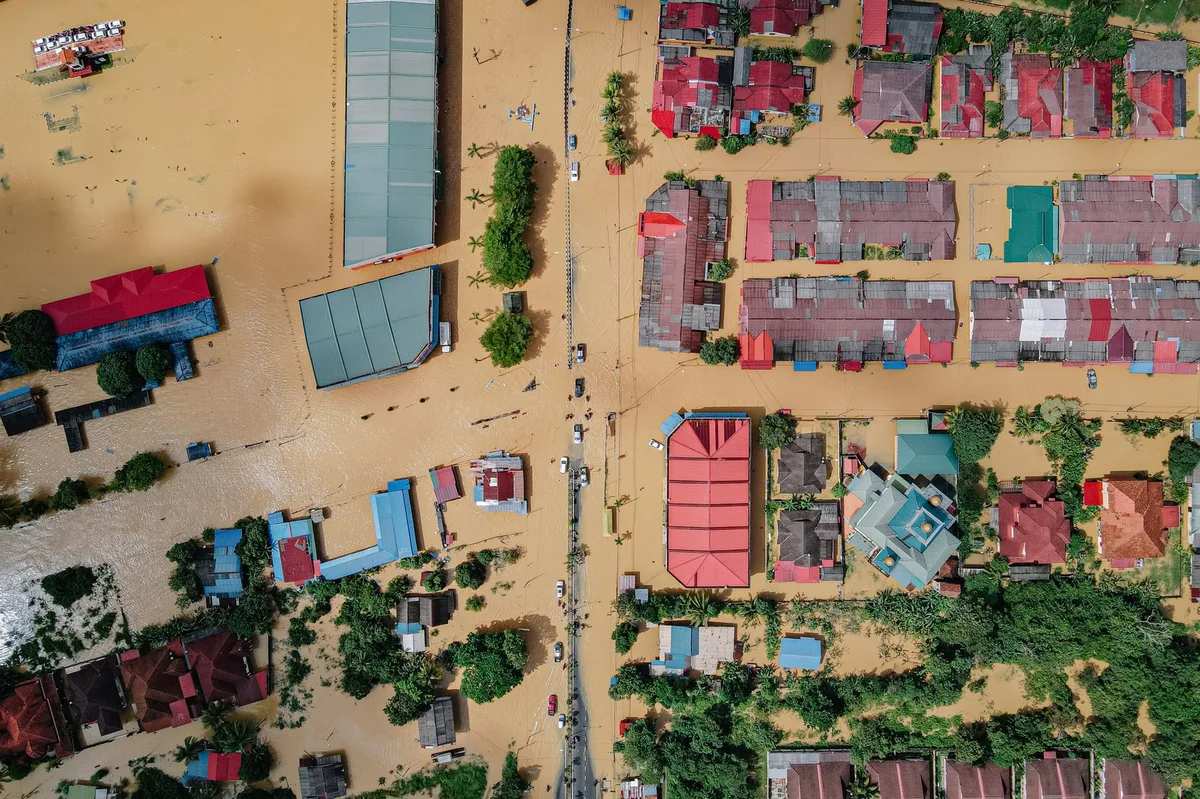
Understanding the difference between standard home insurance exclusions and optional overland water coverage can save Canadian homeowners from unexpected financial losses.
Pet insurance can cost C$30 to C$150 per month, but a single emergency can run thousands. Find out when coverage pays off and when you're better saving on your own.
Under-insuring your home triggers the coinsurance clause, which can slash your claim payout even for partial losses. Here's what every Canadian homeowner needs to know.
Using your personal car for business purposes can void your auto insurance coverage, leaving you exposed to claim denials and out-of-pocket costs.
E&O insurance covers professional mistakes and advice, while CGL protects against bodily injury and property damage. Most Canadian freelancers need one or both depending on their work.
Key person insurance protects Canadian businesses from the financial impact of losing a critical owner or executive. Learn what it covers, how it works, and whether your business needs it.
Learn how the calculator method helps you estimate the life insurance coverage needed to replace your income and protect your family's financial future in Canada.
Mortgage life insurance and term life insurance both protect your family if you pass away, but they work differently and offer different value. Term life usually provides more flexibility, lower premiums, and better coverage for your money.
Your condo corporation's master policy covers the building structure, but not your personal belongings, improvements, or liability. Here's what coverage you need as a Canadian condo owner.
Compare employer group life insurance and individual policies to understand which provides better protection for Canadian families.

Compare Canada's leading home insurance providers by coverage options, customer service, and value to find the right policy for your property.
High claims satisfaction is encouraging, but Canadian drivers should still compare price, coverage, service, and provincial rules before renewing.
Kin's U.S. auto insurance launch is not a Canadian product update, but the bundling idea is relevant for Canadian homeowners. Compare the total price, coverage wording, deductibles, and provincial rules before moving home and car insurance to one provider.
Canadian extended health insurance enrollment has hit an all-time high, with over 2.3 million individuals enrolling in supplementary coverage plans in 2026, driven by rising healthcare costs and expanded employer benefits.
Overland water coverage protects Canadian homeowners from flood damage that standard home insurance excludes. Learn how to secure flood insurance before spring runoff and storm season begins.
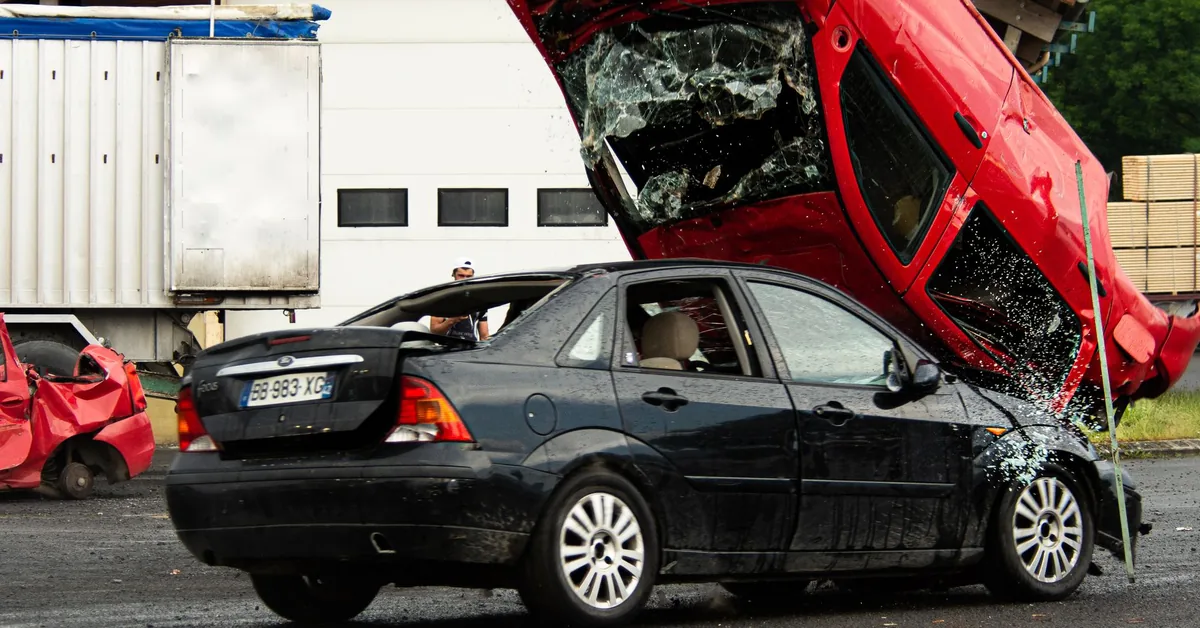
Third party liability insurance covers bodily injury and property damage you cause to others in a car accident, and it is mandatory in every Canadian province and territory.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.