Insurance
Home Insurance Winterization Checklist for Canadian Homeowners
Protect your home insurance coverage this winter with essential maintenance steps that prevent costly claims and keep your policy valid.
Author
Writes about auto, home, and travel insurance across Canadian provinces. Explains no-fault systems, replacement-cost riders, and the provincial differences that affect what coverage costs and what it pays out.
Protect your home insurance coverage this winter with essential maintenance steps that prevent costly claims and keep your policy valid.
Compare essential business insurance coverage options for small businesses and self-employed professionals in Canada, from general liability to cyber protection.
Bundling home and auto insurance can save Canadian drivers 10 to 25 percent on premiums, but separate policies sometimes offer better coverage or lower total cost.
Understand what your employer's group benefits package covers and where gaps may exist in your life, disability, and health insurance protection.
Provincial health plans offer limited coverage abroad. Learn what travel insurance should include and where your provincial plan falls short.
Most Canadian life insurance policies include a terminal illness benefit at no extra cost, but understanding how it compares to standalone critical illness coverage can help you make informed decisions about your protection.
Learn how joint first-to-die life insurance compares to separate policies for Canadian couples, including cost differences, coverage trade-offs, and when each option makes sense for your family.
Non-owner car insurance provides liability coverage when you regularly drive vehicles you don't own, though most Canadians are already covered under the owner's policy.
Learn how scheduling protects valuables beyond standard policy sub-limits and why professional appraisals matter for home insurance claims in Canada.
A claims-free discount rewards drivers who avoid filing auto insurance claims. One at-fault accident can erase years of savings.
Group disability insurance through your employer offers convenient coverage but may have gaps, while individual policies provide portable, customizable protection you control directly.
Income protection replaces lost earnings when illness or injury stops you from working. Long-term care insurance pays for custodial care when you need help with daily activities. Each fills a distinct financial gap.
Learn how trip length, age, destination, and coverage type determine your travel insurance premium, and use our calculator to estimate costs for snowbird stays or international trips.
Provincial health plans offer limited or no coverage outside Canada. Learn what travel insurance covers, when OHIP and other provincial plans are not enough, and how to estimate the right coverage for your trip.
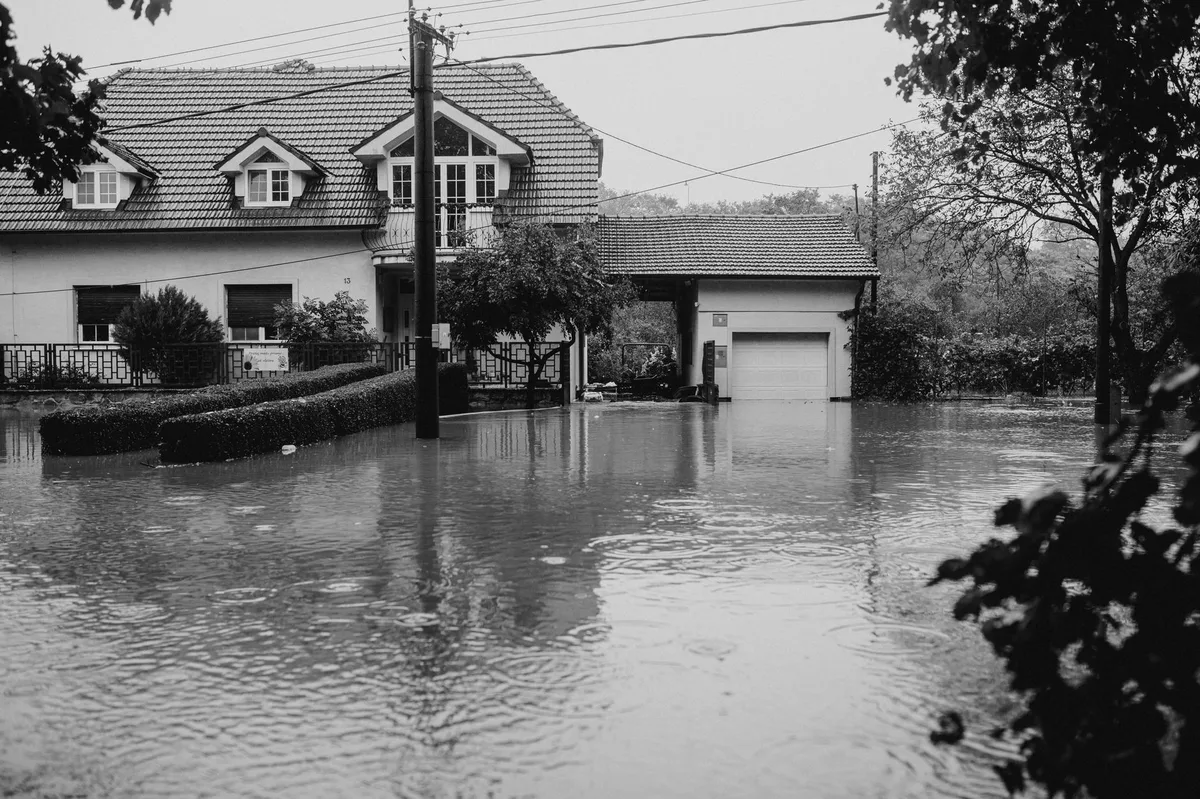
Standard home policies exclude flood and sewer backup. Here's what you need to know about adding this optional coverage in Canada.
Understand the key differences between group and individual supplementary health and dental coverage in Canada and how to choose the right plan for your situation.
Understand the key differences between employer-sponsored group disability coverage and individual disability insurance policies in Canada, and learn which option best protects your income.
Wildfire damage is typically covered under standard home insurance in Nova Scotia, but coverage limits, deductibles, and claim documentation requirements vary by policy and insurer.
A BMO Insurance life insurance claim usually starts with confirming the policy, contacting the insurer, and submitting proof of death plus beneficiary documents. This checklist explains what to prepare before relying on a payout.
Income replacement insurance can help replace part of your paycheque if illness or injury keeps you from working. The right monthly benefit starts with your real after-tax spending, not just your gross salary.
Canadian homeowners face increasing flood risk from spring melt, heavy rain, and coastal storms. Here's when to buy overland flood coverage and why timing matters.
As severe weather risks increase across Canada, homeowners face important decisions about overland water and flood coverage.
Standard home insurance does not cover overland flooding in Canada. Learn what overland water coverage protects, how to get it, and what limits apply.
CTP (third-party liability) coverage is the mandatory component of auto insurance in Canada that pays for damage and injuries you cause to others.

Professional liability insurance protects Canadian small businesses and self-employed professionals from claims of negligence, errors, or omissions in their professional services.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.