Insurance
Most Common Home Insurance Claims in the UK
Discover the most frequent home insurance claims UK households make, from escape of water to theft, and learn how to protect your property.
Car, life, and home insurance guidance for UK households.
Discover the most frequent home insurance claims UK households make, from escape of water to theft, and learn how to protect your property.
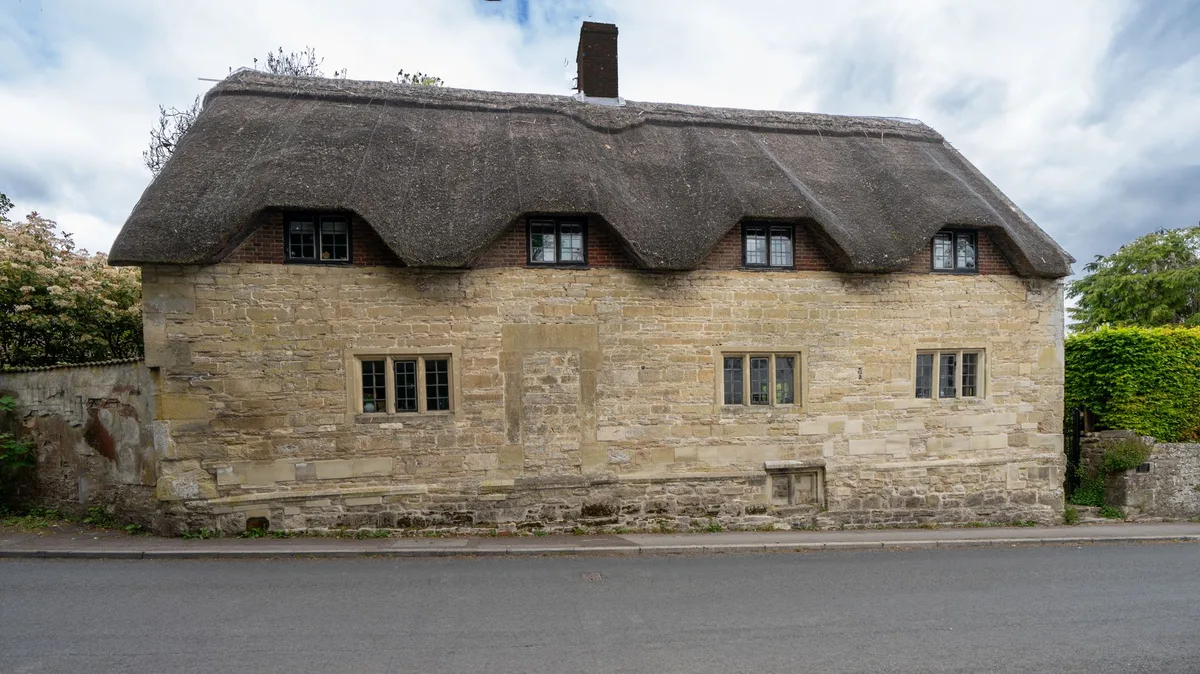
Major insurers are withdrawing from the thatched property market as claims costs and fire risks drive premiums higher, leaving UK homeowners with fewer specialist options.
Home insurance premiums in the UK jumped by 40.6% year-on-year in January, marking one of the steepest increases in recent years. This sharp rise reflects growing claims costs, more frequent weather events, and inflation across the insurance sector.
Practical strategies to reduce your home insurance costs without sacrificing essential cover.
Learn how to earn and protect a no claims discount on your home insurance policy, potentially saving up to 50% on premiums by maintaining a claims-free record.
CCTV can reduce home insurance premiums by 5-10%, though the actual discount varies by insurer and system specification. Learn whether the savings justify the installation cost.
UK car insurance premiums have surged significantly in recent years, driven by rising vehicle theft, repair costs, and claims frequency.
Motor insurance premiums in the UK rose in 2025 due to claims inflation, repair costs, and market conditions - discover what drove these increases and how to manage your costs.
A practical checklist to help you decide between comprehensive and third-party car insurance cover, based on your vehicle value, budget, and risk profile.
Winter brings higher risks on UK roads. Check your cover, excess, and breakdown protection before the season starts.
Practical strategies to reduce your motor insurance costs when your policy comes up for renewal, from comparing quotes to protecting your no-claims bonus.
Autumn brings a surge in UK car insurance renewals. Learn why millions of policies renew in this period and how switching insurers can save you hundreds of pounds.
British insurers paid out a record £8 billion in protection claims, marking the highest annual payout for life, critical illness and income protection cover.
Aviva data reveals suicide is the primary cause of life insurance claims for men under 40. Understanding how policies handle suicide and the mental health context behind these statistics.
Employer group life insurance during open enrollment typically covers death in service benefits, but coverage amounts and optional add-ons vary by scheme.
Critical illness cover pays a lump sum if you are diagnosed with a serious condition listed in your policy. Learn which illnesses are typically covered and what to check before you buy.
Understanding the key differences between term assurance and whole of life policies to choose the right life insurance for your needs and budget.
Understand the key factors that determine life insurance premiums in the UK and how to compare quotes effectively to find the best cover for your needs.
UK car and home insurance premiums continue to stay elevated despite hopes for relief, with drivers and homeowners facing ongoing price pressure.
Homeowners are three times more likely to hold life insurance than income protection, yet both cover different financial risks.
Keep records of business insurance premiums for at least five years after the January 31 deadline to claim tax deductions and satisfy HMRC requirements.
Major life changes often require updates to your insurance cover. Learn which policies to review and how to ensure your protection stays current.
Compare essential business insurance types for UK small businesses and sole traders, from legally required employers' liability to optional professional indemnity cover.
Most UK insurers charge cancellation fees when you switch mid-policy, but switching can still save money if the new premium is significantly lower.
Flood risk is one of the most significant factors insurers use to calculate home insurance premiums, with properties in high-risk areas often facing substantially higher costs or limited cover options.
Flood cover in the UK is not automatic. Understand when you need it, how Flood Re helps, and what standard home insurance actually covers for flood damage.
Discover who needs flood insurance in the UK, how the Flood Re scheme helps high-risk homes get affordable cover, and what you need to know about protecting your property from flood damage.
Flood cover in the UK works differently from standard home insurance and availability depends on your property's flood risk, but the Flood Re scheme helps keep it affordable for high-risk homes.
With flood season approaching, UK homeowners should review their insurance cover to ensure they are protected against the rising risk of property damage from flooding.
UK authorities recommend arranging flood insurance ahead of the autumn and winter flood season, when claims rise sharply and cover can be harder to secure.
Contents insurance protects your belongings as a tenant. Learn what's covered, why landlord insurance won't help, and how to calculate the right level of cover for your rental.
Christmas shopping can significantly increase the value of items in your home. Reviewing your contents insurance now ensures you have adequate cover if theft, fire, or damage strikes during the festive period.
Understanding how standard contents insurance caps payouts per item and when you need to declare valuables separately for full protection.
Compare contents insurance options for UK tenants, from basic cover to comprehensive policies with accidental damage protection.
Contents insurance protects your belongings inside your home. Learn what it covers and whether you need it.
Understand what drives contents insurance premiums for UK tenants and how to find cover that fits your budget.
The Association of British Insurers shares eight vital travel insurance tips backed by claims data, helping UK travellers understand what cover they need and how to avoid common pitfalls.
Essential guide to travel insurance for UK travellers heading abroad this Christmas, covering medical cover, winter weather protection, and what your EHIC or GHIC won't pay for.
The cheapest travel insurance policy rarely offers the best protection. This guide compares the key features that matter most when choosing travel cover in the UK.
The cheapest travel insurance policy may leave you underprotected. Learn what matters most when choosing cover for your trip.
Learn what drives travel insurance premiums and how to estimate the right cover cost for your trip before you buy.
Understand what UK travel insurance actually covers and whether a single-trip or annual policy offers better value for your travel plans.
Some UK home insurers accept 85% of claims whilst others accept as few as 45%, reflecting differences in policy terms, risk appetite, and claims handling practices that directly affect your likelihood of receiving a payout.
Understanding what winter weather damage is covered by your UK home and motor insurance policies, and when you might need to claim.
Learn the essential steps to file and settle a home insurance claim in the UK, from initial notification to final settlement.
Making a claim can push your premium up by 20% to 50% or more at renewal, even for small incidents. Understanding how insurers price risk helps you decide when to claim.
There is no single official UK league table for the best and worst claims insurers. Use complaints context, claims satisfaction, policy wording and settlement practice to judge the real risk.
A home or car insurance claim can raise your next premium, but there is no fixed UK-wide surcharge. The impact depends on the claim type, cost, fault, claims history and insurer.
Compare income protection and critical illness insurance for the autumn open season, with side-by-side analysis of cover, costs, and which policy suits your circumstances.
The NHS provides free healthcare, but private medical insurance can offer faster access and more choice. Find out when PMI is worth the cost.
Weighing up private medical insurance against relying solely on the NHS? We break down the real costs, benefits, and drawbacks to help you decide if PMI is worth it for your situation.
Private medical insurance uptake in the UK continues to grow as waiting times and NHS pressures drive more residents to consider additional health cover.
Rising private medical insurance premiums are stretching household budgets, but direct government assistance for PMI costs is limited in the UK. Here's what support exists and how to manage rising health cover expenses.
Compare lifetime and per-condition pet insurance to find the right cover for your dog or cat in the UK.
Learn the critical differences between lifetime and per-condition pet insurance policies in the UK, and which type of cover best protects your pet and your finances.
Work out how much landlord insurance cover you need with our calculator, from buildings and contents sums to loss of rent protection for your UK rental property.
Work out the right level of landlord insurance for your rental property with our UK-focused calculator and guide to buildings, contents, and liability cover.
Learn how income protection insurance replaces your income if you cannot work due to illness or injury, and discover who needs this cover in the UK.
Understand the key differences between professional indemnity and public liability cover, and which policy UK freelancers need to protect their business.
Learn how the FCA oversees insurers, protects policyholders, and maintains standards in the UK insurance market.
Pet insurance in the UK typically costs £200 to £800 per year, with premiums shaped by your pet's age, breed, location, and the level of cover you choose.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
